Chatha Foods (CHATHA) Q2 FY27 Swings to Loss as New Plants Drive Costs
Revenue grew 12% year-on-year, but a sharp rise in depreciation and employee costs from newly commissioned facilities pushed the company into a quarterly loss.
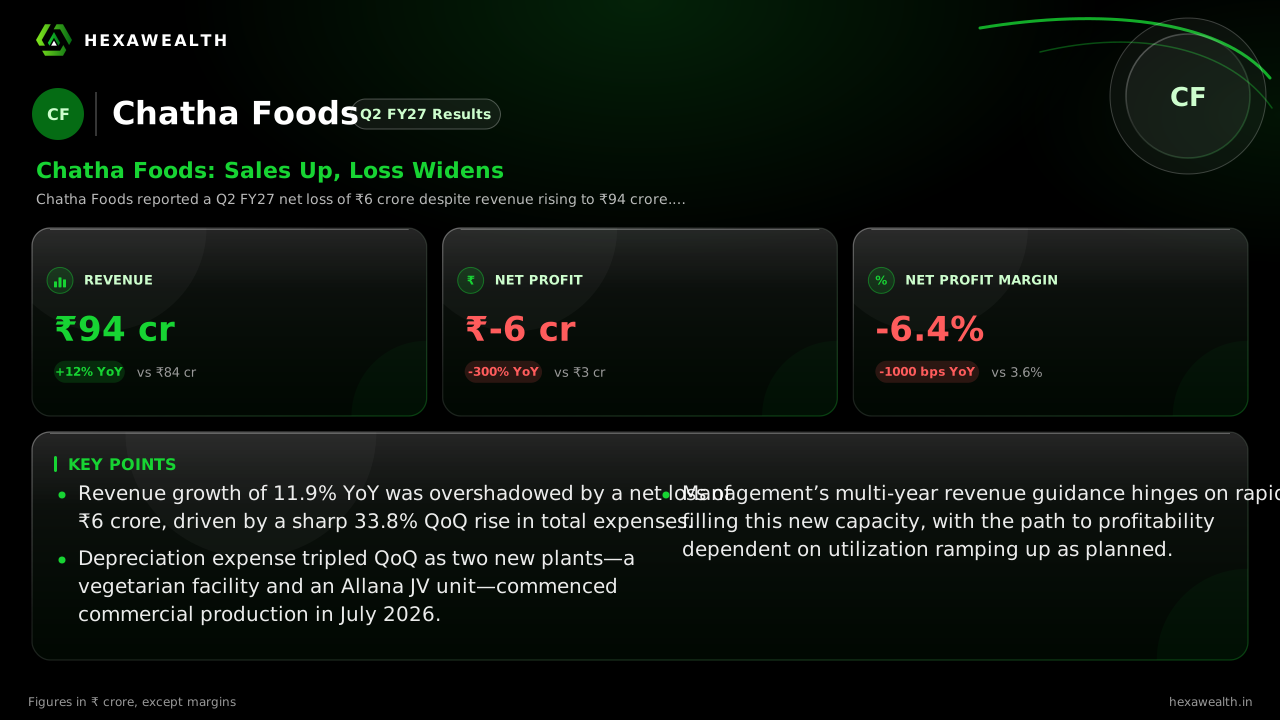
Chatha Foods reported a Q2 FY27 net loss of ₹6 crore despite revenue rising to ₹94 crore. The loss stems from the commercial start of its new vegetarian plant and Allana joint venture, which sharply increased operating expenses.
For Chatha Foods, this quarter was the moment its heavy investment in new capacity began to show up on the income statement. The frozen food processor’s revenue grew, but the cost of getting two new plants running wiped out its profit.
The numbers show the tension. Revenue for the September 2026 quarter was ₹94 crore, up 11.9% from a year ago and 14.6% from the prior quarter. Profit, however, swung to a loss of ₹6 crore, a sharp reversal from the ₹3 crore profit posted in both Q2 FY26 and Q4 FY26. The net profit margin collapsed to -6.4%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY25: 74.0
- Revenue (₹ Cr), Q4 FY25: 83.0
- Revenue (₹ Cr), Q2 FY26: 84.0
- Revenue (₹ Cr), Q4 FY26: 82.0
- Revenue (₹ Cr), Q2 FY27: 94.0
- Profit (₹ Cr), Q2 FY25: 3.0
- Profit (₹ Cr), Q4 FY25: 3.0
- Profit (₹ Cr), Q2 FY26: 3.0
- Profit (₹ Cr), Q4 FY26: 3.0
- Profit (₹ Cr), Q2 FY27: -6.0
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY25: 74.0
- Revenue (₹ Cr), Q4 FY25: 83.0
- Revenue (₹ Cr), Q2 FY26: 84.0
- Revenue (₹ Cr), Q4 FY26: 82.0
- Revenue (₹ Cr), Q2 FY27: 94.0
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY25: 3.0
- Profit (₹ Cr), Q4 FY25: 3.0
- Profit (₹ Cr), Q2 FY26: 3.0
- Profit (₹ Cr), Q4 FY26: 3.0
- Profit (₹ Cr), Q2 FY27: -6.0
Net Profit Margin (%)
- Net Profit Margin (%), Q2 FY25: 4.1
- Net Profit Margin (%), Q4 FY25: 3.6
- Net Profit Margin (%), Q2 FY26: 3.6
- Net Profit Margin (%), Q4 FY26: 3.7
- Net Profit Margin (%), Q2 FY27: -6.4
| Metric | CurrentQ2 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|
| Revenue (₹ Cr) | 94.0YoY +12% | 84.0 |
| Profit (₹ Cr) | -6.0YoY -300% | 3.0 |
| Net Profit Margin (%) | -6.4YoY -278% | 3.6 |
Why the new plants turned profitable sales into a loss
The driver is not a demand slump but a cost surge. Total expenses jumped 33.8% quarter-on-quarter and 28.8% year-on-year. According to a report by ForgeUp, this was primarily driven by a rise in the cost of materials consumed and employee benefits.
More telling is the leap in depreciation, which tripled sequentially and rose 50% year-on-year. A report from mcapital.in explains this was due to the new 16,000 MT vegetarian plant starting commercial production on 27 July 2026 and the Allana joint venture facility starting on 9 July 2026. These assets are now on the books and depreciating, but are yet to contribute meaningfully to sales volume.
The investment thesis is now a waiting game
Management’s ambitious guidance, noted in a concall summary from sovrenn.com, projects revenue to leap to ₹325 crore in FY27, ₹450 crore in FY28, and ₹550 crore by FY29. The current quarter’s loss is the price of that bet. The vegetarian plant is expected to run at 25-30% utilization in its first year.
Live Chart
· CHATHA
(BSE)
ISIN: INE0AH901011
The market’s reaction was muted on the results day, with the stock closing flat. Over the preceding three months, however, the stock had declined 19.7%, reflecting investor caution around the capital-intensive expansion. No major brokerages have published fresh ratings or targets following the results.
Key Points
- Revenue growth of 11.9% YoY was overshadowed by a net loss of ₹6 crore, driven by a sharp 33.8% QoQ rise in total expenses.
- Depreciation expense tripled QoQ as two new plants—a vegetarian facility and an Allana JV unit—commenced commercial production in July 2026.
- Management’s multi-year revenue guidance hinges on rapidly filling this new capacity, with the path to profitability dependent on utilization ramping up as planned.
Hexa Perspective
This quarter crystallizes the transition from a steady, low-margin kitchen for QSRs to a company betting on tripling its scale. The loss is not a surprise but a planned cost of the ramp-up phase. The investment case now rests entirely on execution: whether order books fill the new vegetarian and export lines fast enough to offset the fixed-cost burden. With raw material costs constituting 74% of revenue, as flagged by Flash Finance, the margin recovery will be a delicate balance between volume growth and input price management. Investors are paying for future sales today, with the stock trading at a slight discount to the industry PE.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.