Chatha Foods (CHATHA) Q4 FY26 Profit Stalls as Heavy Capex Fuels Future Growth
The frozen food supplier's profit held flat in Q4 FY26 despite a revenue dip, as a sharp increase in borrowings funded a massive capacity expansion aimed at tripling revenue by FY29.
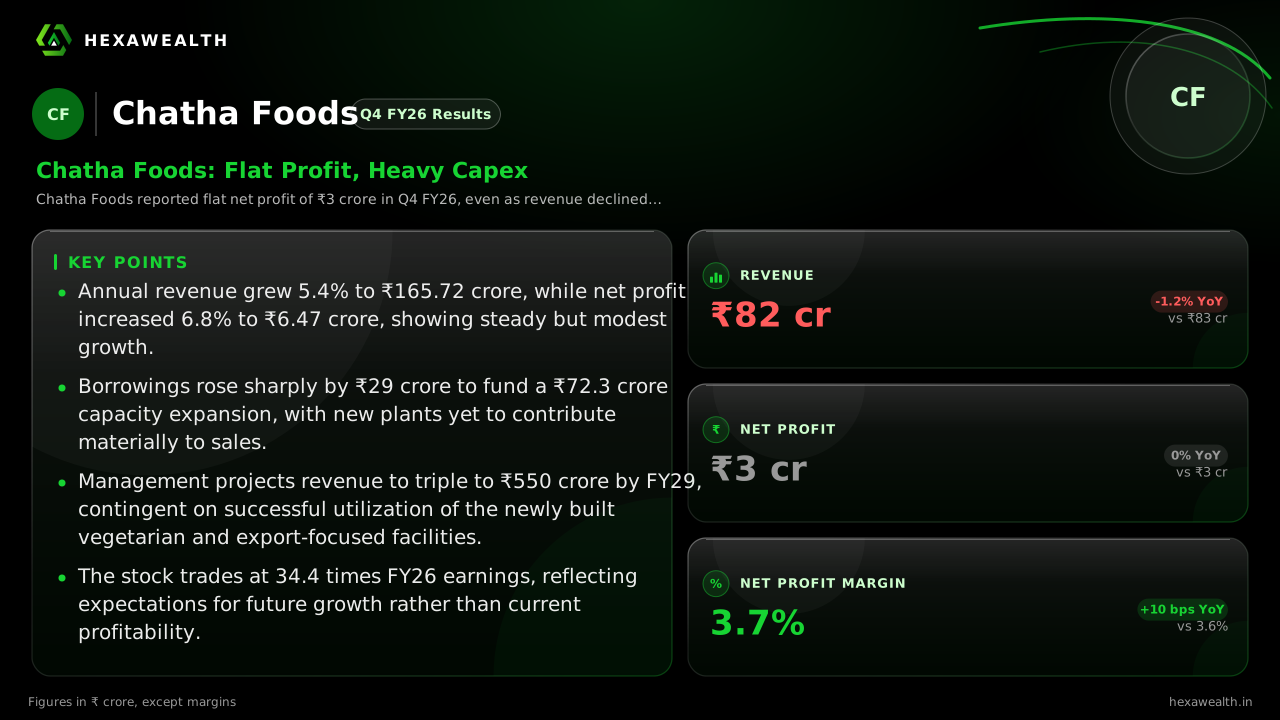
Chatha Foods reported flat net profit of ₹3 crore in Q4 FY26, even as revenue declined slightly. The quarter capped a year of heavy investment, with borrowings rising ₹29 crore to fund new plants that are yet to contribute meaningfully to sales.
For Chatha Foods, a key supplier to Domino's and Subway, the March quarter was a quiet end to a year of heavy lifting. Revenue dipped slightly, but profit held steady, a sign of modest efficiency gains in a period of transition. The real story, however, is playing out on the balance sheet, where a sharp rise in debt signals a high-stakes bet on future capacity.
The numbers show a company in a holding pattern. Revenue for Q4 FY26 was ₹82 crore, down 1.2% from the same quarter last year. Net profit remained flat at ₹3 crore, with the net profit margin inching up 10 basis points to 3.7%. For the full year, revenue grew 5.4% to ₹165.72 crore, while profit rose 6.8% to ₹6.47 crore.
Revenue & profit
Revenue (₹ Cr)
Net Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY25: 74.0
- Revenue (₹ Cr), Q4 FY25: 83.0
- Revenue (₹ Cr), Q2 FY26: 84.0
- Revenue (₹ Cr), Q4 FY26: 82.0
- Net Profit (₹ Cr), Q2 FY25: 3.0
- Net Profit (₹ Cr), Q4 FY25: 3.0
- Net Profit (₹ Cr), Q2 FY26: 3.0
- Net Profit (₹ Cr), Q4 FY26: 3.0
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY25: 74.0
- Revenue (₹ Cr), Q4 FY25: 83.0
- Revenue (₹ Cr), Q2 FY26: 84.0
- Revenue (₹ Cr), Q4 FY26: 82.0
Net Profit (₹ Cr)
- Net Profit (₹ Cr), Q2 FY25: 3.0
- Net Profit (₹ Cr), Q4 FY25: 3.0
- Net Profit (₹ Cr), Q2 FY26: 3.0
- Net Profit (₹ Cr), Q4 FY26: 3.0
Net Profit Margin (%)
- Net Profit Margin (%), Q2 FY25: 4.1
- Net Profit Margin (%), Q4 FY25: 3.6
- Net Profit Margin (%), Q2 FY26: 3.6
- Net Profit Margin (%), Q4 FY26: 3.7
| Metric | CurrentQ4 FY26 | Same quarter LYQ4 FY25 |
|---|---|---|
| Revenue (₹ Cr) | 82.0YoY -1.2% | 83.0 |
| Net Profit (₹ Cr) | 3.0YoY 0% | 3.0 |
| Net Profit Margin (%) | 3.7YoY +2.8% | 3.6 |
Why Profit Held While Sales Slipped
A closer look reveals how profit stayed level. Total expenses fell 2.5% year-on-year, according to the analysis, and depreciation was 50% lower than the previous quarter. This provided a small buffer against the revenue decline. The profit before tax actually rose 25% year-on-year, as reported by newboard.in, but a higher tax provision kept the final net profit unchanged.
The Capex That Changes Everything
The static quarterly performance belies a dramatic shift in the company's footprint. Borrowings surged by ₹29 crore in FY26 to ₹40.77 crore, funding an estimated ₹72.3 crore in fixed asset additions. This spending, noted by scanx.trade, was for a new 16,000 MT vegetarian plant and a joint venture facility with Allana aimed at exports. Most of this capital sat as work-in-progress at year-end, earning nothing yet.
This explains the wild swing in operating cash flow, which turned positive at ₹10 crore in FY26 from a negative ₹1.07 crore the year before. The improvement came from better working capital management, but the company's free cash flow remained deeply negative at -₹62 crore, as capital spending far outpaced operating cash generation.
Live Chart
· CHATHA
(BSE)
ISIN: INE0AH901011
A Future Built on New Plants
Management's guidance, detailed in a concall summary from sovrenn.com, paints an ambitious picture. They expect revenue to leap to ₹325 crore in FY27, ₹450 crore in FY28, and ₹550 crore in FY29 as the new plants ramp up. The targets hinge on filling the newly built capacity, with the vegetarian plant expected to run at 25-30% utilization in its first year.
The risk is clear: the company remains heavily reliant on a few large QSR customers, and the new plants must now find enough orders. The valuation, at 34.4 times FY26 earnings against a sector average of 35.8, already prices in significant growth. Investors are paying for the promise of the new facilities, not the current earnings.
Key Points
- Annual revenue grew 5.4% to ₹165.72 crore, while net profit increased 6.8% to ₹6.47 crore, showing steady but modest growth.
- Borrowings rose sharply by ₹29 crore to fund a ₹72.3 crore capacity expansion, with new plants yet to contribute materially to sales.
- Management projects revenue to triple to ₹550 crore by FY29, contingent on successful utilization of the newly built vegetarian and export-focused facilities.
- The stock trades at 34.4 times FY26 earnings, reflecting expectations for future growth rather than current profitability.
Hexa Perspective
The quarter itself was uneventful, but it closed a chapter defined by aggressive capital allocation. Chatha Foods has positioned itself for a much larger scale, funded by debt and retained earnings. The next few quarters will be a litmus test for execution.
The path forward depends entirely on filling the new capacity. Success would mean revenue growth accelerating sharply from the current 5% pace. Failure, or a delay, would leave the company with higher interest costs and underutilized assets. The flat profit in Q4 is a pause; the coming year will show whether the ambitious expansion was a masterstroke or a misstep.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.