Maiden Forgings (MAIDEN) Q2 FY27 Profit Jumps 250%, But It's From a Land Sale
Revenue grew 23% on better product mix, but the reported profit of ₹7 crore was entirely due to a one-time land sale gain, leaving core operations in the red.
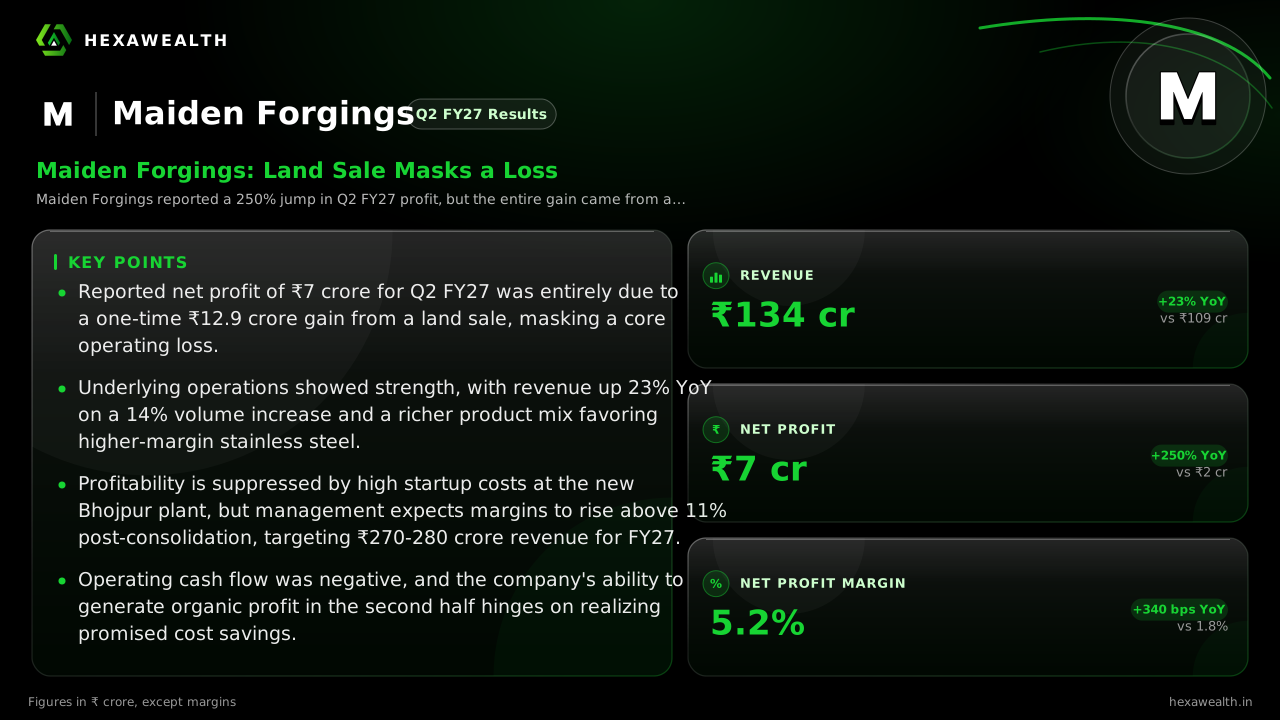
Maiden Forgings reported a 250% jump in Q2 FY27 profit, but the entire gain came from a one-time land sale. While revenue grew 23% on volume and mix, the core manufacturing business posted an operating loss.
For Maiden Forgings, a steel processor pivoting to higher-value products, the September quarter delivered a headline win that hid a more complex reality. Revenue grew a solid 23% year-on-year, but the reported profit was entirely propped up by a one-time land sale, leaving the core business still waiting for its promised efficiency gains.
The numbers show a company in transition. Revenue reached ₹134 crore, with profit before tax more than tripling to ₹9 crore. Yet the net profit margin of 5.2%, while improved, is flattered by a ₹12.9 crore gain from selling a vacant Ghaziabad land parcel, as management clarified on the earnings call.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY25 (Sep 2024): 109.0
- Revenue (₹ Cr), Q4 FY25 (Mar 2025): 104.0
- Revenue (₹ Cr), Q2 FY26 (Sep 2025): 109.0
- Revenue (₹ Cr), Q4 FY26 (Mar 2026): 122.0
- Revenue (₹ Cr), Q2 FY27 (Sep 2026): 134.0
- Profit (₹ Cr), Q2 FY25 (Sep 2024): 4.0
- Profit (₹ Cr), Q4 FY25 (Mar 2025): 2.0
- Profit (₹ Cr), Q2 FY26 (Sep 2025): 2.0
- Profit (₹ Cr), Q4 FY26 (Mar 2026): 3.0
- Profit (₹ Cr), Q2 FY27 (Sep 2026): 7.0
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY25 (Sep 2024): 109.0
- Revenue (₹ Cr), Q4 FY25 (Mar 2025): 104.0
- Revenue (₹ Cr), Q2 FY26 (Sep 2025): 109.0
- Revenue (₹ Cr), Q4 FY26 (Mar 2026): 122.0
- Revenue (₹ Cr), Q2 FY27 (Sep 2026): 134.0
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY25 (Sep 2024): 4.0
- Profit (₹ Cr), Q4 FY25 (Mar 2025): 2.0
- Profit (₹ Cr), Q2 FY26 (Sep 2025): 2.0
- Profit (₹ Cr), Q4 FY26 (Mar 2026): 3.0
- Profit (₹ Cr), Q2 FY27 (Sep 2026): 7.0
Net Profit Margin
- Net Profit Margin, Q2 FY25 (Sep 2024): 3.7%
- Net Profit Margin, Q4 FY25 (Mar 2025): 1.9%
- Net Profit Margin, Q2 FY26 (Sep 2025): 1.8%
- Net Profit Margin, Q4 FY26 (Mar 2026): 2.5%
- Net Profit Margin, Q2 FY27 (Sep 2026): 5.2%
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ4 FY26 (Mar 2026) |
|---|---|---|
| Revenue (₹ Cr) | 134.0 | 122.0 |
| Profit (₹ Cr) | 7.0 | 3.0 |
| Net Profit Margin | 5.2% | 2.5% |
The gap between headline and reality
Management, on the call transcribed by AlphaStreet and MarketPing, was upfront about the one-off. Excluding the land sale, the company's core operating profit was negative. The operational story, however, has genuine momentum. Sales volume grew 14.2%, and revenue grew faster at 22.4%, driven by a richer mix of stainless steel and alloy products.
This shift is central to the strategy. As per the earnings call, stainless steel now makes up 35-40% of revenue from just 15% of volume, carrying healthier margins. The raw material cost ratio also improved to 87% of sales from 90% a year ago.
The cost of consolidation
The path to sustainable profit runs through the new Bhojpur facility, which began operations in July. While it promises monthly savings of at least ₹50 lakh once fully consolidated, the transition is costly now. Other expenses ballooned to 51% of revenue due to shifting and startup costs, temporarily diluting profits.
Live Chart
· MAIDEN
(BSE)
ISIN: INE0O1T01010
Management expects operational margin to rise above 11% after consolidation, up from 6.8% in the first half excluding the land gain. The guidance, noted by MarketPing, targets FY27 revenue of ₹270-280 crore.
Cash flow and the road ahead
Execution is now the critical test. Operating cash flow was negative ₹14 crore in the first half, and management on the call would not commit to a positive H2, expecting it to be “around nil” as capex completes. The stock, as reported by Stockwatch.live, rose 5.3% the day after the earnings call, suggesting the market is betting on the operational turnaround story over the messy current profit.
Key Points
- Reported net profit of ₹7 crore for Q2 FY27 was entirely due to a one-time ₹12.9 crore gain from a land sale, masking a core operating loss.
- Underlying operations showed strength, with revenue up 23% YoY on a 14% volume increase and a richer product mix favoring higher-margin stainless steel.
- Profitability is suppressed by high startup costs at the new Bhojpur plant, but management expects margins to rise above 11% post-consolidation, targeting ₹270-280 crore revenue for FY27.
- Operating cash flow was negative, and the company's ability to generate organic profit in the second half hinges on realizing promised cost savings.
Hexa Perspective
Maiden Forgings is caught between a promising operational reset and a profitability timeline still months away. The quarter confirms the volume and mix story is real, but the bottom line remains entirely dependent on one-off asset sales. Investors are essentially funding a consolidation, with the payoff—sustainable profit from the Bhojpur facility's cost savings—now expected in the second half.
The stock's reaction, a gain against a falling market, prices in this execution bet. The risk is that any delay in realizing the ₹50 lakh monthly savings or a slowdown in the premium product mix push profitability further into FY28. The next few quarters will separate the operational promise from the profit delivery.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.