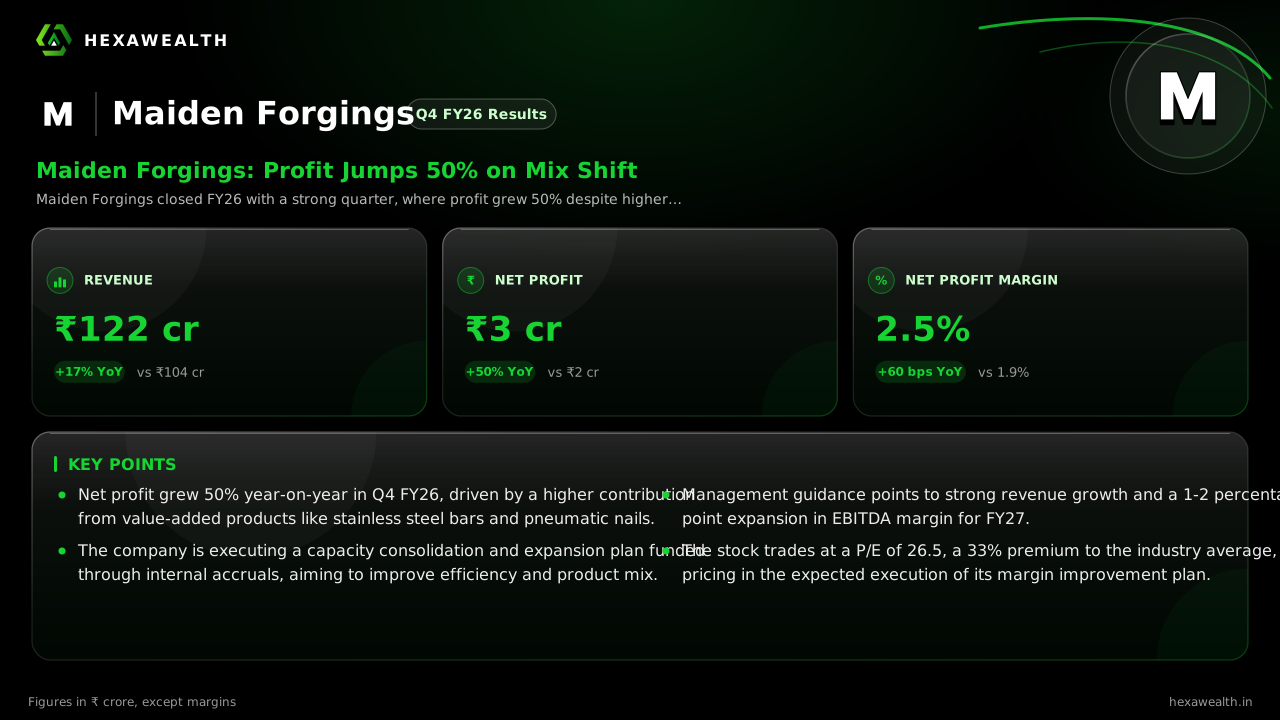
Maiden Forgings (MAIDEN) Q4 FY26 Profit Surges as Product Mix Sharpens Margins
A strategic pivot to higher-value products drove a 50% profit jump in Q4, setting the stage for a margin-led recovery in FY27.
Maiden Forgings closed FY26 with a strong quarter, where profit grew 50% despite higher interest costs. The improvement was powered by a shift towards high-margin stainless steel and alloy bars, a trend management expects to accelerate.
For a steel processor like Maiden Forgings, the story is always in the spread between raw material cost and finished product price. The fourth quarter showed that spread widening not from commodity bets, but from a deliberate climb up the value chain.
Revenue rose 17.3% year-on-year to ₹122 crore, while net profit jumped 50% to ₹3 crore. The net profit margin expanded by 60 basis points from a year ago, reaching 2.5%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q4 FY24: 121.0
- Revenue (₹ Cr), Q2 FY25: 109.0
- Revenue (₹ Cr), Q4 FY25: 104.0
- Revenue (₹ Cr), Q2 FY26: 109.0
- Revenue (₹ Cr), Q4 FY26: 122.0
- Profit (₹ Cr), Q4 FY24: 6.0
- Profit (₹ Cr), Q2 FY25: 4.0
- Profit (₹ Cr), Q4 FY25: 2.0
- Profit (₹ Cr), Q2 FY26: 2.0
- Profit (₹ Cr), Q4 FY26: 3.0
Revenue (₹ Cr)
- Revenue (₹ Cr), Q4 FY24: 121.0
- Revenue (₹ Cr), Q2 FY25: 109.0
- Revenue (₹ Cr), Q4 FY25: 104.0
- Revenue (₹ Cr), Q2 FY26: 109.0
- Revenue (₹ Cr), Q4 FY26: 122.0
Profit (₹ Cr)
- Profit (₹ Cr), Q4 FY24: 6.0
- Profit (₹ Cr), Q2 FY25: 4.0
- Profit (₹ Cr), Q4 FY25: 2.0
- Profit (₹ Cr), Q2 FY26: 2.0
- Profit (₹ Cr), Q4 FY26: 3.0
| Metric | CurrentQ4 FY26 | Same quarter LYQ4 FY25 |
|---|---|---|
| Revenue (₹ Cr) | 122.0YoY +17% | 104.0 |
| Profit (₹ Cr) | 3.0YoY +50% | 2.0 |
| Net Margin (%) | 2.5YoY +32% | 1.9 |
The Mix That Lifted Margins
The profit growth came despite a 33% sequential jump in interest expense. Management, in the earnings call covered by Arthneeti, attributed the margin resilience to a changing product mix. Sales of higher-margin pneumatic nails, stainless steel, and alloy bars increased their contribution from January 2026 onward.
This shift more than offset the pressure from volatile steel prices. The company hedges its basic processing margin by booking raw material against customer orders. The real earnings leverage is now coming from selling more sophisticated products.
A Year of Transition
The full-year picture reveals the transition. Annual revenue grew 8.8% to ₹231.6 crore, but profit fell 17% to ₹5.02 crore. Operating profit margin contracted by 200 basis points, as the benefits of the new product mix were concentrated in the second half.
Live Chart
· MAIDEN
(BSE)
ISIN: INE0O1T01010
This sets up a clear divergence between the past year and the one ahead. With the new product lines gaining traction, the annual decline in profitability looks like a base about to be rebuilt.
Funding Growth Without New Debt
Capacity expansion is central to the FY27 outlook. The company is consolidating two units into a new 4-acre facility in Modinagar, expected to be fully operational by September 2026. According to reports from First India, this move is funded internally, including proceeds from a ₹12.9 crore land sale.
The expansion will add 9,000-10,000 tonnes of annual capacity focused on high-margin galvanized wires and stainless steel components. Management targets raising the EBITDA margin by 1-2 percentage points within FY27, as utilization climbs from about 73% toward 85%.
Key Points
- Net profit grew 50% year-on-year in Q4 FY26, driven by a higher contribution from value-added products like stainless steel bars and pneumatic nails.
- The company is executing a capacity consolidation and expansion plan funded through internal accruals, aiming to improve efficiency and product mix.
- Management guidance points to strong revenue growth and a 1-2 percentage point expansion in EBITDA margin for FY27.
- The stock trades at a P/E of 26.5, a 33% premium to the industry average, pricing in the expected execution of its margin improvement plan.
Hexa Perspective
The quarter confirms that Maiden Forgings' earnings recovery is not tied to a steel price cycle but to its own operational shift. The 50% profit jump on a 17% revenue rise shows operating leverage is returning, provided the product mix holds.
The premium valuation suggests the market is betting on management's guidance for margin expansion. The thesis will be tested in the first half of FY27, as the new facility ramps up and the promised savings and mix benefits materialize. Execution on these internal levers, not external commodity trends, will decide if the premium is justified.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.