KV Toys India (KVTOYS) Q2 FY27 Profit Stalls as Costs Outpace 28% Revenue Growth
KV Toys India posted a 28% jump in Q2 revenue, but profit was flat as rising material costs and new depreciation squeezed margins.
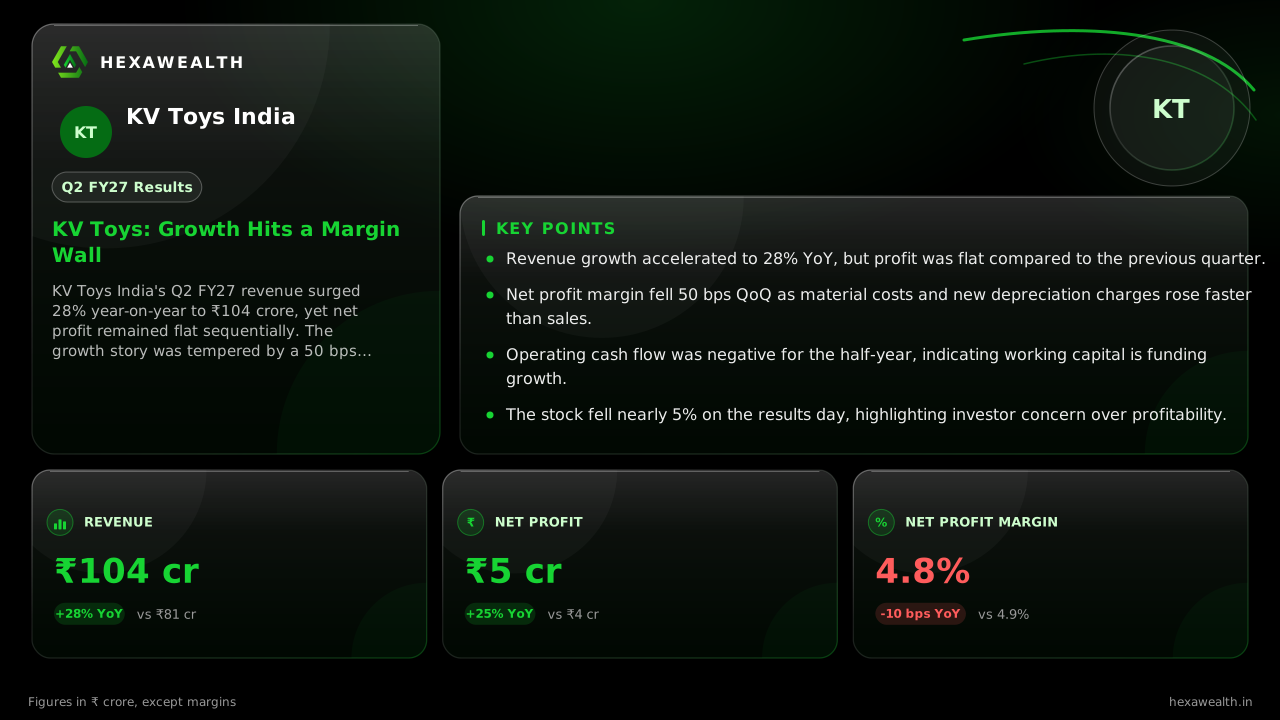
KV Toys India's Q2 FY27 revenue surged 28% year-on-year to ₹104 crore, yet net profit remained flat sequentially. The growth story was tempered by a 50 bps quarterly drop in net margin as expenses climbed faster than sales.
For KV Toys India, scaling up in a protected domestic market has delivered consistent top-line gains. The September quarter saw that trend accelerate, but the cost of that growth became clearer as profits failed to follow revenue higher.
Revenue rose 28.4% year-on-year to ₹104 crore, while net profit grew 25% to ₹5 crore. Sequentially, the story diverged: a 10.6% revenue increase from the March quarter yielded no profit growth, with the net profit margin contracting by 50 basis points to 4.8%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q4 FY25: 55.0
- Revenue (₹ Cr), Q2 FY26: 81.0
- Revenue (₹ Cr), Q4 FY26: 94.0
- Revenue (₹ Cr), Q2 FY27: 104.0
- Profit (₹ Cr), Q4 FY25: 3.0
- Profit (₹ Cr), Q2 FY26: 4.0
- Profit (₹ Cr), Q4 FY26: 5.0
- Profit (₹ Cr), Q2 FY27: 5.0
Revenue (₹ Cr)
- Revenue (₹ Cr), Q4 FY25: 55.0
- Revenue (₹ Cr), Q2 FY26: 81.0
- Revenue (₹ Cr), Q4 FY26: 94.0
- Revenue (₹ Cr), Q2 FY27: 104.0
Profit (₹ Cr)
- Profit (₹ Cr), Q4 FY25: 3.0
- Profit (₹ Cr), Q2 FY26: 4.0
- Profit (₹ Cr), Q4 FY26: 5.0
- Profit (₹ Cr), Q2 FY27: 5.0
Net Profit Margin (%)
- Net Profit Margin (%), Q4 FY25: 5.5
- Net Profit Margin (%), Q2 FY26: 4.9
- Net Profit Margin (%), Q4 FY26: 5.3
- Net Profit Margin (%), Q2 FY27: 4.8
| Metric | CurrentQ2 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|
| Revenue (₹ Cr) | 104.0YoY +28% | 81.0 |
| Profit (₹ Cr) | 5.0YoY +25% | 4.0 |
| Net Profit Margin (%) | 4.8YoY -2% | 4.9 |
Where the Sales Growth Went
The revenue jump was broad-based, driven by portfolio expansion under the QUCO brand and a network now spanning over 700 active SKUs, according to a company business update. However, total expenses grew even faster, up 29.9% year-on-year and 11.4% quarter-on-quarter.
A Cruxal.in analysis notes that cost of materials accounted for 67% of the total expense increase. This suggests volume growth, not pricing power, was the primary driver. While material costs as a share of revenue improved slightly year-on-year, they still consumed 76.8% of every rupee earned.
The New Costs of Expansion
Beyond raw materials, two other expenses pinched margins. Employee costs rose, and depreciation hit ₹1 crore this quarter, up from zero in the prior quarter. This new charge stems from recent capacity investments, including a subsidiary that began operations in May.
Live Chart
· KVTOYS
(BSE)
ISIN: INE1IE301018
The company's growth is also tying up cash. MarketPing reported a consolidated operating cash outflow of ₹2.5 crore for the half-year, as receivables surged to fund sales. This working capital intensity means reported profits are not yet converting into cash.
The Market's Verdict
The stock reacted negatively to these mixed signals, falling 4.9% on the results day according to MarketPing data. Investors weighed strong revenue momentum against clear margin pressure and cash absorption. With a P/E of 15.1, the stock trades at a significant discount to the industry average of 32.7, reflecting these execution risks.
Key Points
- Revenue growth accelerated to 28% YoY, but profit was flat compared to the previous quarter.
- Net profit margin fell 50 bps QoQ as material costs and new depreciation charges rose faster than sales.
- Operating cash flow was negative for the half-year, indicating working capital is funding growth.
- The stock fell nearly 5% on the results day, highlighting investor concern over profitability.
Hexa Perspective
The quarter outlines KV Toys' current phase: successfully capturing demand in a supportive 'Make in India' environment, but doing so at a cost. The margin squeeze is not a one-off but structural, linked to its volume-led model and new capacity investments that bring depreciation before full revenue benefits.
The path forward hinges on whether scale eventually brings operating leverage. Management's focus on backward integration and the planned acquisition of a stake in Play Panda, an educational toy maker, aim to improve brand economics. For now, investors are pricing in the execution gap between a growing top line and a yet-to-materialise bottom-line reward.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.