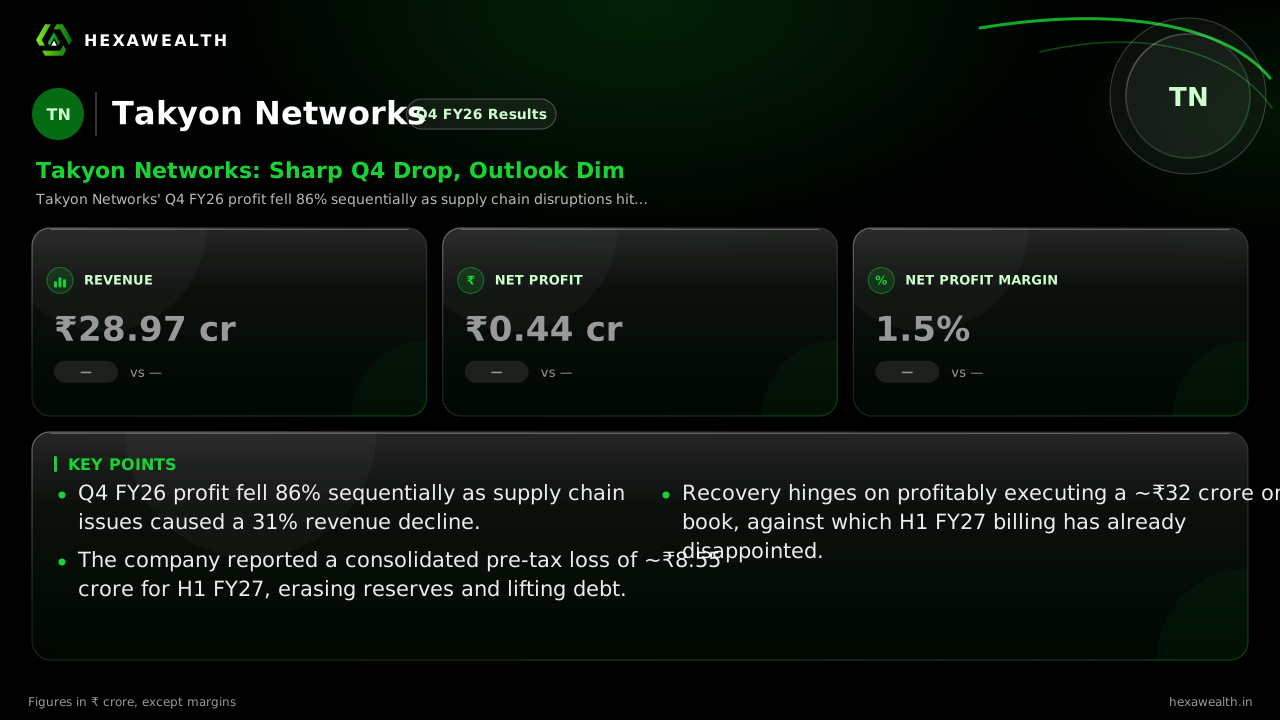
Takyon Networks (TAKYON) Q4 FY26 Profit Plunges 86% as Supply Chain Bites
The IT solutions provider saw revenue and profit fall sharply in Q4 FY26, with a deep loss already reported for the first half of the new fiscal year.
Takyon Networks' Q4 FY26 profit fell 86% sequentially as supply chain disruptions hit revenue. The company reported a consolidated loss for H1 FY27, erasing years of profit and straining its balance sheet.
For Takyon Networks, a project-based IT infrastructure provider, the final quarter of FY26 was about damage control. Global supply chain turbulence and component price inflation, as noted in the company's earnings call covered by Arthneeti, forced a choice between chasing low-margin volume and preserving capital. The result was a steep sequential decline in both top and bottom lines.
The quarter ended with revenue of ₹28.97 crore, down 31% from the September quarter. Profit collapsed 86% to ₹0.44 crore. The net profit margin contracted by 620 basis points to just 1.5%. A near-tripling of other income provided no meaningful cushion against the operating weakness.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY26 (Sep 2025): 42.08
- Revenue (₹ Cr), Q4 FY26 (Mar 2026): 28.97
- Profit (₹ Cr), Q2 FY26 (Sep 2025): 3.22
- Profit (₹ Cr), Q4 FY26 (Mar 2026): 0.44
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY26 (Sep 2025): 42.08
- Revenue (₹ Cr), Q4 FY26 (Mar 2026): 28.97
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY26 (Sep 2025): 3.22
- Profit (₹ Cr), Q4 FY26 (Mar 2026): 0.44
Net Profit Margin
- Net Profit Margin, Q2 FY26 (Sep 2025): 7.7%
- Net Profit Margin, Q4 FY26 (Mar 2026): 1.5%
| Metric | CurrentQ4 FY26 (Mar 2026) | PreviousQ2 FY26 (Sep 2025) |
|---|---|---|
| Revenue (₹ Cr) | 28.97 | 42.08 |
| Profit (₹ Cr) | 0.44 | 3.22 |
| Net Profit Margin | 1.5% | 7.7% |
Why the margins vanished
The sharp profit drop stemmed from a collapse in operating leverage. With revenue down, operating profit nearly vanished, falling to ₹0.31 crore from ₹5.04 crore in the prior quarter. Management, according to Arthneeti, prioritized margin integrity over volume, but fixed-price contracts in a period of hyper-inflation for components squeezed profitability regardless.
This pressure extended into the new fiscal year. Data from mcapital.in shows H1 FY27 swung to a consolidated pre-tax loss of about ₹8.55 crore on revenue of ₹30.67 crore. This loss has already eroded reserves and increased short-term borrowings, pointing to sustained cash-flow pressure.
The bridge to recovery
Management's path forward relies on executing a confirmed order book. The Q4 earnings call indicated a ₹32 crore order book as of March 2026, with ₹20-22 crore expected to bill in H1 FY27. A recent ₹11.59 crore railway contract adds to this pipeline. The company targets 15-20% revenue growth for FY27.
Live Chart
· TAKYON
(BSE)
ISIN: INE14OX01013
Yet, the guidance faces a harsh reality check. The H1 FY27 loss implies the company is far behind its targets. Converting the order book profitably is now critical to stem the erosion of net worth, which fell in the first half as reported by mcapital.in.
Key Points
- Q4 FY26 profit fell 86% sequentially as supply chain issues caused a 31% revenue decline.
- The company reported a consolidated pre-tax loss of ~₹8.55 crore for H1 FY27, erasing reserves and lifting debt.
- Recovery hinges on profitably executing a ~₹32 crore order book, against which H1 FY27 billing has already disappointed.
Hexa Perspective
The quarter confirms a severe operational breakdown, not a transient dip. The plunge from a 7.7% net margin to 1.5% in six months shows how fragile the project-based model is when input costs spike and execution stalls.
With H1 FY27 already deeply in the red, the full-year guidance of 15-20% growth looks detached from current run-rates. Investors are weighing a strong order book against a demonstrated inability to convert it profitably under stress. The stock's 67% discount to the industry P/E reflects that deep skepticism.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.