Crazy Snacks (CRAZY) Q2 FY27 Q2 Loss Widens as Subsidiaries Drag on Sales
The snack maker's consolidated performance weakened, with a ₹1 crore net loss as subsidiary struggles offset a resilient standalone business.
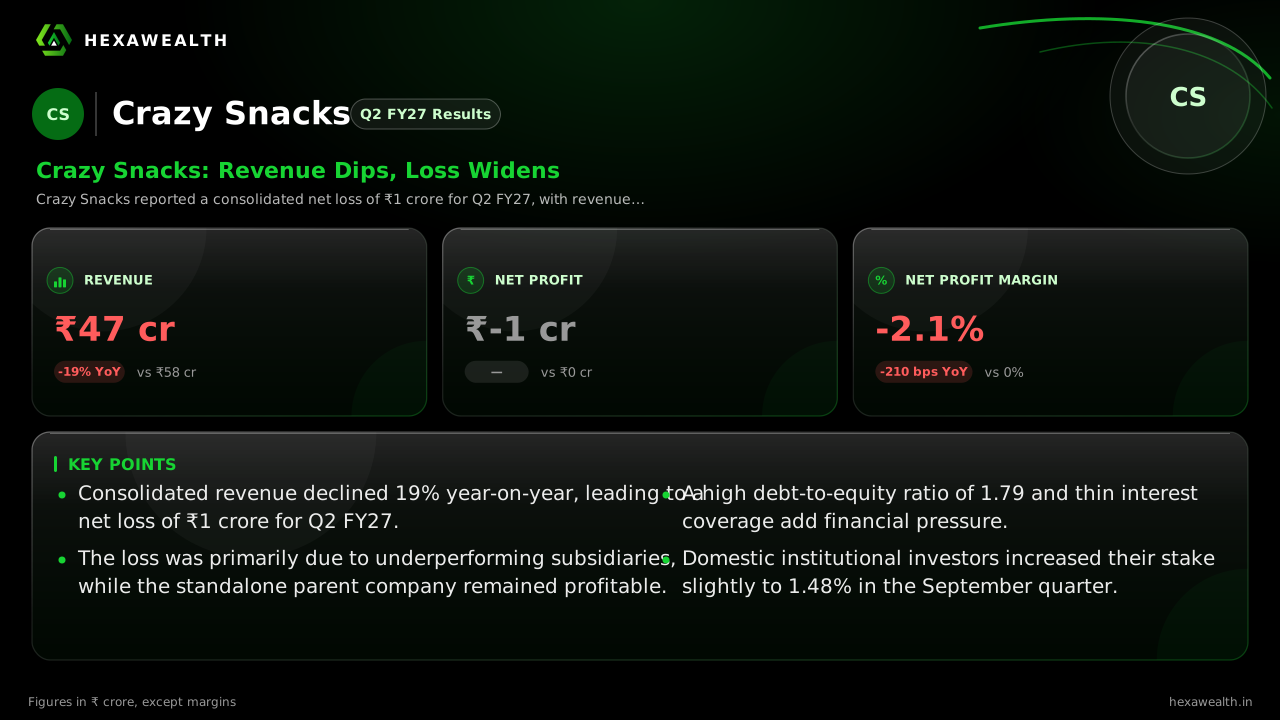
Crazy Snacks reported a consolidated net loss of ₹1 crore for Q2 FY27, with revenue falling 19% year-on-year. The loss was driven by underperformance at its bakery and funfoods subsidiaries, despite the parent company remaining profitable.
For a recently listed snack maker, the first earnings test is whether the core business can grow profitably. Crazy Snacks' second quarter shows a company split in two. The parent entity managed costs well, but its subsidiaries pulled the consolidated group into a loss.
The numbers tell a story of divergence. Consolidated revenue fell 19% year-on-year to ₹47 crore, while net profit swung to a loss of ₹1 crore from a near-breakeven position last year. The net profit margin deteriorated by 210 basis points to -2.1%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q1 FY25: 25.99
- Revenue (₹ Cr), Q2 FY26: 58.0
- Revenue (₹ Cr), Q2 FY27: 47.0
- Profit (₹ Cr), Q1 FY25: 1.28
- Profit (₹ Cr), Q2 FY26: 0.0
- Profit (₹ Cr), Q2 FY27: -1.0
Revenue (₹ Cr)
- Revenue (₹ Cr), Q1 FY25: 25.99
- Revenue (₹ Cr), Q2 FY26: 58.0
- Revenue (₹ Cr), Q2 FY27: 47.0
Profit (₹ Cr)
- Profit (₹ Cr), Q1 FY25: 1.28
- Profit (₹ Cr), Q2 FY26: 0.0
- Profit (₹ Cr), Q2 FY27: -1.0
Net Profit Margin (%)
- Net Profit Margin (%), Q1 FY25: 4.9
- Net Profit Margin (%), Q2 FY26: 0.0
- Net Profit Margin (%), Q2 FY27: -2.1
| Metric | CurrentQ2 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|
| Revenue (₹ Cr) | 47.0YoY -19% | 58.0 |
| Profit (₹ Cr) | -1.0 | 0.0 |
| Net Profit Margin (%) | -2.1 | 0.0 |
The Subsidiary Drag
According to a Scanx Trade report, the consolidated loss was driven by the underperformance of subsidiaries Crazy Bakery Udyog and Crazy Funfoods. While the standalone parent company posted a profit, these units caused total group expenses to exceed income. This structural drag turned what was a marginally profitable quarter a year ago into a clear loss.
A High-Cost Structure
The company carries a significant financial burden. Its debt-to-equity ratio stands at 1.79, which Simply Wall St notes is considered high. Interest coverage is thin at 3x, meaning operating profit is only just enough to cover interest costs. This leverage leaves little room for error as the company invests in capacity.
Capacity and Cash
Investment is ongoing. The company's capital work-in-progress surged to ₹23.2 crore at the end of FY26, as reported by Scanx Trade, indicating active capacity expansion. This comes at a cost: cash reserves fell sharply over the same period to fund these projects. The payoff from this spending is critical for future growth but weighs on the present.
Live Chart
· CRAZY
(BSE)
ISIN: INE0RBX01014
Key Points
- Consolidated revenue declined 19% year-on-year, leading to a net loss of ₹1 crore for Q2 FY27.
- The loss was primarily due to underperforming subsidiaries, while the standalone parent company remained profitable.
- A high debt-to-equity ratio of 1.79 and thin interest coverage add financial pressure.
- Domestic institutional investors increased their stake slightly to 1.48% in the September quarter.
Hexa Perspective
The quarter highlights the execution challenge for a newly public, multi-unit business. The core snack operation shows it can be profitable on a standalone basis, even with lower sales. Yet, the group's fate is tied to turning around its loss-making subsidiaries.
The path forward depends on two factors: whether the parent's cost discipline can be replicated group-wide, and if the heavy capital expenditure translates into revenue-generating capacity soon. Until the subsidiary drag is resolved, consolidated profitability will remain under pressure despite a seemingly healthy standalone core.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.