All posts

Follow Us

LinkedInInstagramX
Quarterly ResultsArchiveLast updated 22 November 20263 min read

Landmark Global Learning (LGLL) Q2 FY27 Revenue Crashes 57% as Business Contracts

The education consultant's revenue plummeted 57% year-on-year, swinging to a net loss amid weak demand and rising working capital stress.

By Abhinav Swaroop, CFA, Chief Business Officer: Hexawealth · Created 17 November 2026

Landmark Global Learning's Q2 FY27 results show a severe contraction. Revenue fell 57% year-on-year to ₹6.68 crore, resulting in a net loss of ₹0.97 crore, a sharp reversal from last year's profit.

For Landmark Global Learning, the September quarter confirmed a deep business contraction. The education consultancy's revenue fell by more than half from a year ago, and a once-profitable operation is now burning cash.

The numbers tell a story of sharp decline. Revenue for Q2 FY27 was ₹6.68 crore, down 57% from the same quarter last year. The company posted a net loss of ₹0.97 crore, a complete reversal from a ₹2.06 crore profit a year earlier. Sequentially, revenue rose from a very low base in March, but profit remained deep in the red.

Revenue & profit

Revenue (₹ Cr.)

Profit (₹ Cr.)

Revenue & profitQ2 FY25 17.96, Q4 FY25 19.62, Q2 FY26 15.60, Q4 FY26 2.71, Q2 FY27 6.68. Q2 FY25 5.34, Q4 FY25 7.79, Q2 FY26 2.06, Q4 FY26 -9.36, Q2 FY27 -0.97-40-2002040Q2 '25Q4 '25Q2 '26Q4 '26Q2 '27
  • Revenue (₹ Cr.), Q2 FY25: 17.96
  • Revenue (₹ Cr.), Q4 FY25: 19.62
  • Revenue (₹ Cr.), Q2 FY26: 15.60
  • Revenue (₹ Cr.), Q4 FY26: 2.71
  • Revenue (₹ Cr.), Q2 FY27: 6.68
  • Profit (₹ Cr.), Q2 FY25: 5.34
  • Profit (₹ Cr.), Q4 FY25: 7.79
  • Profit (₹ Cr.), Q2 FY26: 2.06
  • Profit (₹ Cr.), Q4 FY26: -9.36
  • Profit (₹ Cr.), Q2 FY27: -0.97

Revenue (₹ Cr.)

Revenue (₹ Cr.)Q2 FY25 17.96, Q4 FY25 19.62, Q2 FY26 15.60, Q4 FY26 2.71, Q2 FY27 6.68010203040Q2 '25Q4 '25Q2 '26Q4 '26Q2 '27
  • Revenue (₹ Cr.), Q2 FY25: 17.96
  • Revenue (₹ Cr.), Q4 FY25: 19.62
  • Revenue (₹ Cr.), Q2 FY26: 15.60
  • Revenue (₹ Cr.), Q4 FY26: 2.71
  • Revenue (₹ Cr.), Q2 FY27: 6.68

Profit (₹ Cr.)

Profit (₹ Cr.)Q2 FY25 5.34, Q4 FY25 7.79, Q2 FY26 2.06, Q4 FY26 -9.36, Q2 FY27 -0.97-20-1001020Q2 '25Q4 '25Q2 '26Q4 '26Q2 '27
  • Profit (₹ Cr.), Q2 FY25: 5.34
  • Profit (₹ Cr.), Q4 FY25: 7.79
  • Profit (₹ Cr.), Q2 FY26: 2.06
  • Profit (₹ Cr.), Q4 FY26: -9.36
  • Profit (₹ Cr.), Q2 FY27: -0.97

Net Profit Margin (%)

Net Profit Margin (%)Q2 FY25 29.7, Q4 FY25 39.7, Q2 FY26 13.2, Q4 FY26 —, Q2 FY27 -14.5-80%-40%0%40%80%Q2 '25Q4 '25Q2 '26Q4 '26Q2 '27
  • Net Profit Margin (%), Q2 FY25: 29.7
  • Net Profit Margin (%), Q4 FY25: 39.7
  • Net Profit Margin (%), Q2 FY26: 13.2
  • Net Profit Margin (%), Q4 FY26: —
  • Net Profit Margin (%), Q2 FY27: -14.5
MetricCurrentQ2 FY27Same quarter LYQ2 FY26
Revenue (₹ Cr.)
6.68YoY -57%
15.60
Profit (₹ Cr.)
-0.97YoY -147%
2.06
Net Profit Margin (%)
-14.5YoY -210%
13.2

Why the Business Shrank

The collapse stems from weak demand in its core overseas education and immigration consultancy. A report from mcapital.in points to severe stress, with student departures falling and visa rules tightening in key markets like Canada and Australia. The company's other income, which provided a large boost last year, also plunged 92%.

At the same time, costs remain sticky. Employee benefits and other expenses totaled over ₹7 crore, consuming all revenue. Interest expense surged 550% year-on-year, though from a low base, adding pressure. Trade receivables have ballooned to ₹16.06 crore despite the sales slump, indicating severe working capital strain.

The Cash and IPO Buffer

The company is burning through the buffer from its January 2025 IPO. According to mcapital.in, only ₹8.95 crore of the ₹40.32 crore raised had been used by September 2026, with the rest in bank deposits. Cash stood at ₹7.72 crore, but operating cash flow was negative ₹2.77 crore for the half-year.

Live Chart

· LGLL

(BSE)

ISIN: INE12QA01010

This cash provides a runway, but it is not infinite. With revenue annualizing to roughly ₹13.4 crore, well below last year's ₹18.31 crore, the path to profitability is unclear. Institutional investor holding rose to 22% from 13%, notes Gunpowder Alerts, even as promoter shareholding declined.

Key Points

  • Revenue contracted 57% year-on-year to ₹6.68 crore, reflecting a severe drop in core consultancy business.
  • The company swung to a net loss of ₹0.97 crore from a year-ago profit, with margins deeply negative.
  • Working capital stress is high, with trade receivables at ₹16.06 crore despite the revenue collapse.
  • The company retains most of its IPO proceeds in bank deposits, providing a temporary cash buffer.

Hexa Perspective

The quarter shows a business in structural decline, not a cyclical dip. The core model of placing students abroad is under pressure from tighter visa policies and falling departures. While the IPO cash offers time, it does not solve the fundamental demand problem.

The valuation, at a PE of 3.0 against an industry average of 90.2, prices in this distress. Investors are weighing the cash cushion against a top line that has evaporated. The next few quarters will test whether management can pivot or if the cash simply delays an inevitable reckoning.

Share or follow HexaWealth

Also read

Want this applied to your portfolio?

Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.
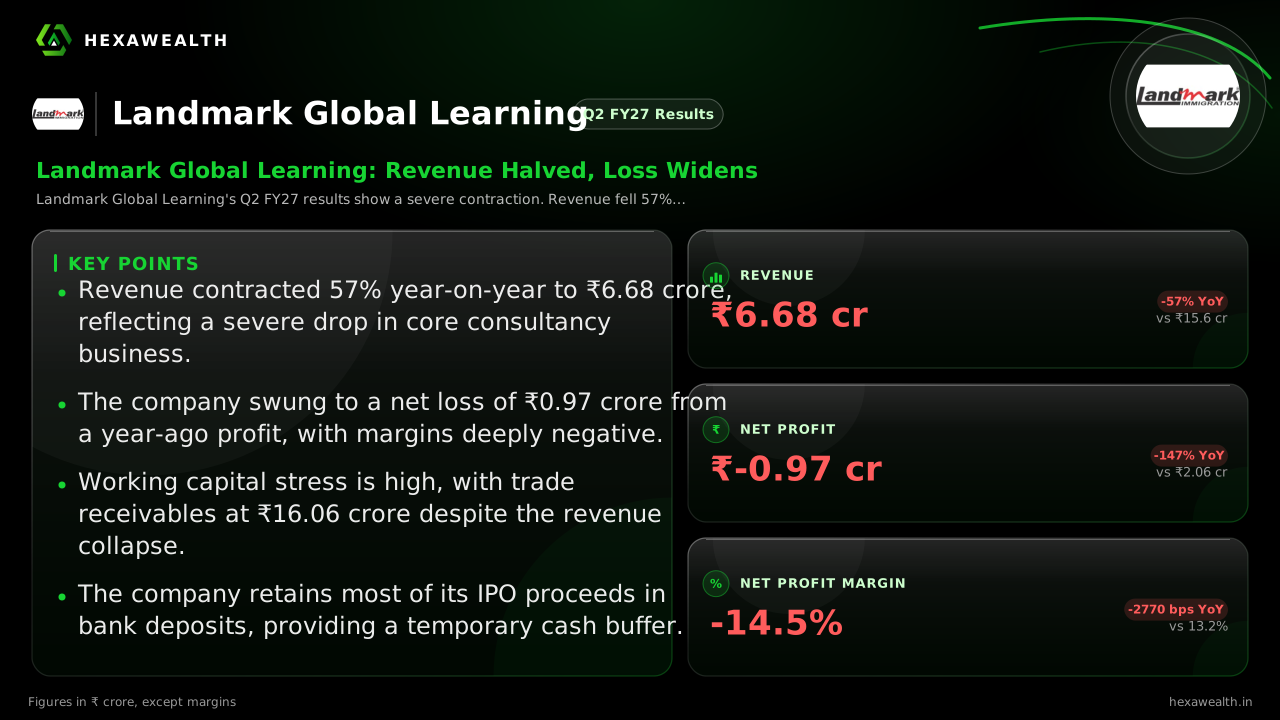
Landmark Global Learning (LGLL) Q2 FY27 results, revenue and profits.

Frequently asked questions

What were Landmark Global Learning's Q2 FY27 results?
Landmark Global Learning reported a Q2 FY27 (September 2026 quarter) revenue of ₹6.68 crore, a 57% drop from last year. The company posted a net loss of ₹0.97 crore, a sharp reversal from a profit of ₹2.06 crore in the same quarter last fiscal year.
What caused Landmark Global Learning's revenue to plummet 57% year-on-year in Q2 FY27?
Landmark Global Learning's revenue collapsed due to weak demand in its overseas education and immigration consultancy business. Reports from mcapital.in cite falling student departures and tighter visa rules in key destination countries like Canada and Australia as primary reasons for the severe stress.
Why did Landmark Global Learning's other income collapse by 92% year-on-year in the September 2026 quarter?
Landmark Global Learning's other income fell 92% year-on-year to ₹0.22 crore in Q2 FY27. This sharp decline removed a significant income stream that had bolstered profits in the prior-year quarter, exacerbating the impact of the operational revenue crash.
Why did Landmark Global Learning's interest expense surge 550% year-on-year in Q2 FY27?
Landmark Global Learning's interest expense rose 550% year-on-year to ₹0.13 crore in Q2 FY27. This surge, though from a very low base of ₹0.02 crore last year, added to the company's cost burden during a period of collapsing revenue.
What is the status of Landmark Global Learning's cash flow and working capital?
Landmark Global Learning's working capital is under severe stress. According to mcapital.in, trade receivables rose to ₹16.06 crore despite a 57% revenue fall. Operating cash flow was negative ₹2.77 crore for H1 FY27, though the company still held ₹7.72 crore in cash from its IPO proceeds.
What guidance did Landmark Global Learning management provide for future quarters?
The research snippets did not contain specific management guidance from a Q2 FY27 earnings call for Landmark Global Learning. The reported results and associated analysis point to a business under severe contraction without a near-term recovery outlook.
What is the current demand environment for educational consultancy services in India?
The overseas education consulting market faces headwinds. Credence Research notes student departures from India fell about 31% between 2023 and 2025, while destination countries have tightened visa and permit policies, putting pressure on agencies like Landmark Global Learning.
Which specific service segments are driving or dragging Landmark Global Learning's performance?
Landmark Global Learning's core Global Education Consultancy and Immigration Consultancy services are dragging performance. The company's business snapshot states these segments assist students and clients with overseas education and visas, which have seen demand collapse due to tighter immigration rules.
Did Landmark Global Learning's Q2 FY27 results beat or miss analyst estimates?
The available research does not specify a consensus analyst estimate for Landmark Global Learning's Q2 FY27. However, reports from ForgeUp and stockfin.ai flag the results as a 'Medium Risk' concern due to the significant decline in revenue and profit.
Are institutional investors increasing or decreasing their stake in Landmark Global Learning?
Institutional investors increased their stake. According to Gunpowder Alerts, institutional holding in Landmark Global Learning rose to 22% as of September 2026, up from 13% in June 2026, even as promoter shareholding declined to 45%.
Landmark Global Learning Q2 profit drop
Landmark Global Learning's Q2 FY27 net profit was a loss of ₹0.97 crore, a severe drop from a profit of ₹2.06 crore in Q2 FY26. This 147% decline was driven by a 57% collapse in revenue and a 92% fall in other income.
Landmark Global Learning September quarter profit
Landmark Global Learning reported a net loss of ₹0.97 crore for the September 2026 quarter (Q2 FY27). This compares to a net profit of ₹2.06 crore in the September 2025 quarter, marking a drastic deterioration in profitability.