Khyati Global Ventures (KGVL) Q2 FY27 Profit Up 67% as Revenue Doubles
The export house reported a 119% surge in revenue, but higher interest costs and the absence of other income kept net profit margin under pressure.
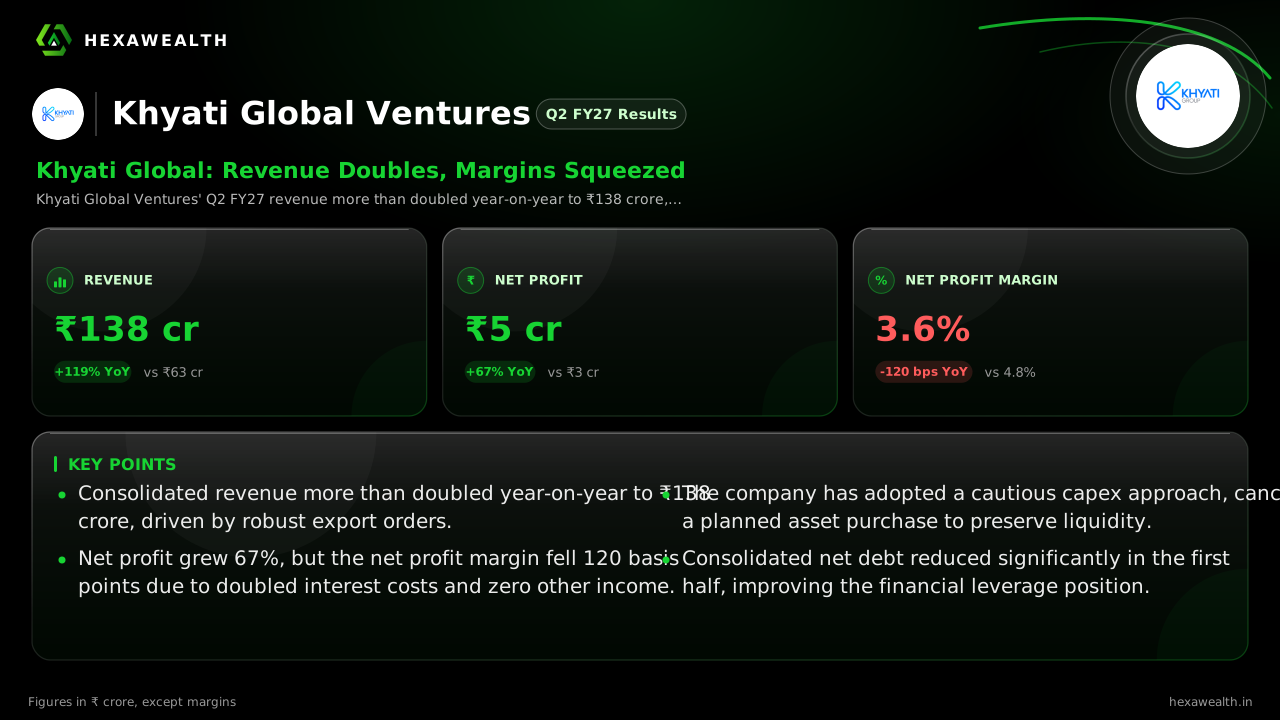
Khyati Global Ventures' Q2 FY27 revenue more than doubled year-on-year to ₹138 crore, driving a 67% profit rise. However, the net profit margin fell as interest costs doubled and other income vanished.
For an export house, growth is measured in orders shipped and markets served. Khyati Global Ventures delivered a breakout quarter on that count, with revenue more than doubling from a year ago. Yet the bottom line tells a story of costs keeping pace, as profitability thinned under higher interest expenses.
The September quarter saw revenue surge to ₹138 crore, up 119% from last year and 64% from the March quarter. Net profit rose 67% to ₹5 crore on both counts. The net profit margin, however, compressed to 3.6% from 4.8% a year earlier.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY25 (Sep 2024): 58.0
- Revenue (₹ Cr), Q4 FY25 (Mar 2025): 61.0
- Revenue (₹ Cr), Q2 FY26 (Sep 2025): 63.0
- Revenue (₹ Cr), Q4 FY26 (Mar 2026): 84.0
- Revenue (₹ Cr), Q2 FY27 (Sep 2026): 138.0
- Profit (₹ Cr), Q2 FY25 (Sep 2024): 3.0
- Profit (₹ Cr), Q4 FY25 (Mar 2025): 2.0
- Profit (₹ Cr), Q2 FY26 (Sep 2025): 3.0
- Profit (₹ Cr), Q4 FY26 (Mar 2026): 3.0
- Profit (₹ Cr), Q2 FY27 (Sep 2026): 5.0
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY25 (Sep 2024): 58.0
- Revenue (₹ Cr), Q4 FY25 (Mar 2025): 61.0
- Revenue (₹ Cr), Q2 FY26 (Sep 2025): 63.0
- Revenue (₹ Cr), Q4 FY26 (Mar 2026): 84.0
- Revenue (₹ Cr), Q2 FY27 (Sep 2026): 138.0
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY25 (Sep 2024): 3.0
- Profit (₹ Cr), Q4 FY25 (Mar 2025): 2.0
- Profit (₹ Cr), Q2 FY26 (Sep 2025): 3.0
- Profit (₹ Cr), Q4 FY26 (Mar 2026): 3.0
- Profit (₹ Cr), Q2 FY27 (Sep 2026): 5.0
Net Profit Margin (%)
- Net Profit Margin (%), Q2 FY25 (Sep 2024): 5.2
- Net Profit Margin (%), Q4 FY25 (Mar 2025): 3.3
- Net Profit Margin (%), Q2 FY26 (Sep 2025): 4.8
- Net Profit Margin (%), Q4 FY26 (Mar 2026): 3.6
- Net Profit Margin (%), Q2 FY27 (Sep 2026): 3.6
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ4 FY26 (Mar 2026) |
|---|---|---|
| Revenue (₹ Cr) | 138.0 | 84.0 |
| Profit (₹ Cr) | 5.0 | 3.0 |
| Net Profit Margin (%) | 3.6 | 3.6 |
The Export Engine Fires
The growth was driven by the company's core export business. According to its annual report, over 90% of revenue comes from overseas sales, with the US and UK as dominant markets. The quarter's performance, as noted by MarketsMojo, indicates strong momentum carried over from the previous fiscal year.
Why Margins Narrowed
Two factors held back profitability despite the sales boom. Interest expense doubled year-on-year to ₹2 crore, even as consolidated net debt fell sharply. Data from investorfeed.in shows the company relies on short-term packing credit facilities, which likely carried higher rates.
Furthermore, other income fell to zero from ₹3 crore in Q2 FY26. This one-off drop, reported by Alfafinder.com, removed a cushion that had previously flattered the net profit margin.
Live Chart
· KGVL
(BSE)
ISIN: INE0S9501014
A Cautious Financial Stance
Management appears focused on managing growth rather than aggressive expansion. In July 2026, as reported by scanx.trade, the company cancelled a planned godown acquisition in Navi Mumbai. This suggests a preference for preserving liquidity over fixed asset investment.
The balance sheet shows progress, with the debt-to-equity ratio at 1.05. An analysis by mcapital.in notes consolidated net debt fell by about ₹20 crore during the first half, supporting stronger earnings potential.
Key Points
- Consolidated revenue more than doubled year-on-year to ₹138 crore, driven by robust export orders.
- Net profit grew 67%, but the net profit margin fell 120 basis points due to doubled interest costs and zero other income.
- The company has adopted a cautious capex approach, cancelling a planned asset purchase to preserve liquidity.
- Consolidated net debt reduced significantly in the first half, improving the financial leverage position.
Hexa Perspective
The quarter confirms Khyati Global's ability to win large export orders, translating directly to the top line. The concern is the quality of that growth, as cash is being consumed by working capital and funded by costlier debt.
For the momentum to be sustainable, the company must either convert receivables faster or secure better financing terms. Investors are weighing strong operational performance against a profitability profile that is financing growth rather than fully capturing it.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.