Swashthik Plascon (SPL) Q2 FY27 Profit Falls 17% as Costs Outpace Sales Growth
Swashthik Plascon's Q2 revenue grew 21% year-on-year, but net profit declined 17% as rising expenses and higher interest costs squeezed margins.
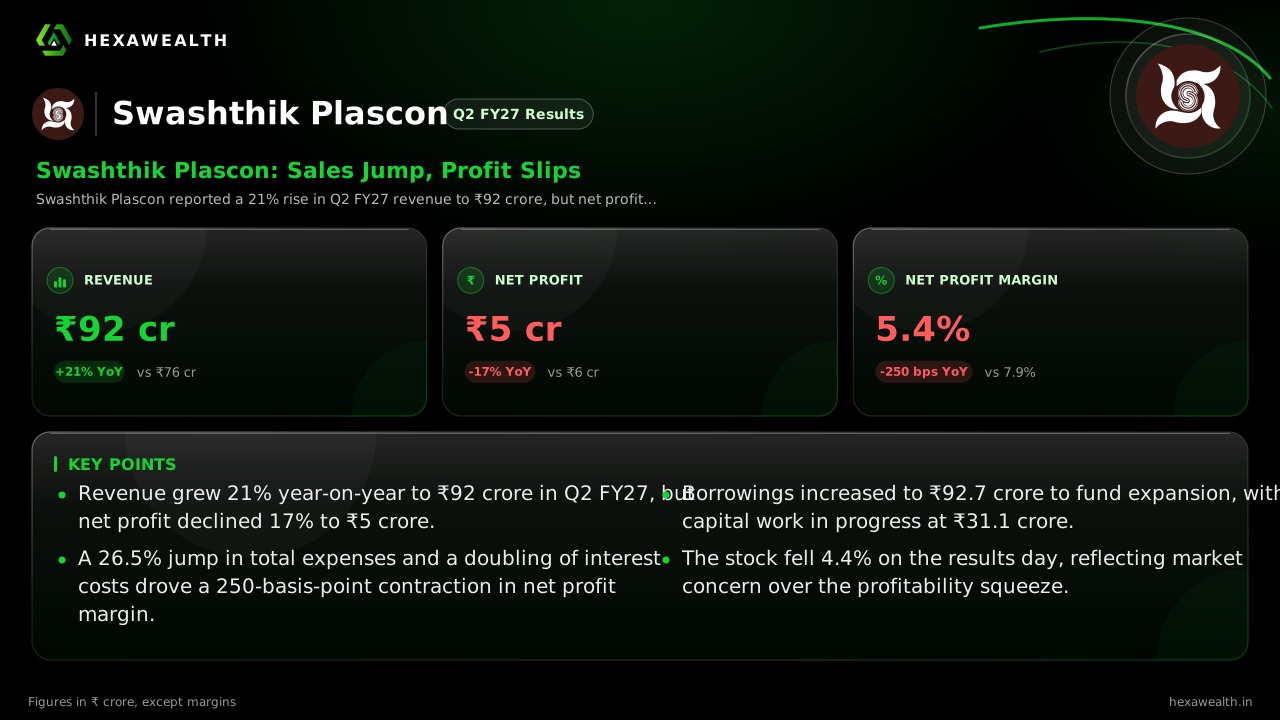
Swashthik Plascon reported a 21% rise in Q2 FY27 revenue to ₹92 crore, but net profit fell 17% to ₹5 crore. The margin squeeze was driven by a 26.5% surge in total expenses and a doubling of interest costs.
For Swashthik Plascon, the September quarter was a story of growth that never reached the bottom line. The plastic products maker delivered a solid 21% year-on-year sales increase, but profit fell as costs rose faster.
Revenue for Q2 FY27 stood at ₹92 crore, up from ₹76 crore a year ago. Net profit, however, declined to ₹5 crore from ₹6 crore. The company's net profit margin contracted 250 basis points to 5.4%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY25: 72.0
- Revenue (₹ Cr), Q4 FY25: 72.0
- Revenue (₹ Cr), Q2 FY26: 76.0
- Revenue (₹ Cr), Q4 FY26: 77.0
- Revenue (₹ Cr), Q2 FY27: 92.0
- Profit (₹ Cr), Q2 FY25: 4.0
- Profit (₹ Cr), Q4 FY25: 2.0
- Profit (₹ Cr), Q2 FY26: 6.0
- Profit (₹ Cr), Q4 FY26: 3.0
- Profit (₹ Cr), Q2 FY27: 5.0
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY25: 72.0
- Revenue (₹ Cr), Q4 FY25: 72.0
- Revenue (₹ Cr), Q2 FY26: 76.0
- Revenue (₹ Cr), Q4 FY26: 77.0
- Revenue (₹ Cr), Q2 FY27: 92.0
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY25: 4.0
- Profit (₹ Cr), Q4 FY25: 2.0
- Profit (₹ Cr), Q2 FY26: 6.0
- Profit (₹ Cr), Q4 FY26: 3.0
- Profit (₹ Cr), Q2 FY27: 5.0
Net Profit Margin (%)
- Net Profit Margin (%), Q2 FY25: 5.6
- Net Profit Margin (%), Q4 FY25: 2.8
- Net Profit Margin (%), Q2 FY26: 7.9
- Net Profit Margin (%), Q4 FY26: 3.9
- Net Profit Margin (%), Q2 FY27: 5.4
| Metric | CurrentQ2 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|
| Revenue (₹ Cr) | 92.0YoY +21% | 76.0 |
| Profit (₹ Cr) | 5.0YoY -17% | 6.0 |
| Net Profit Margin (%) | 5.4YoY -32% | 7.9 |
The cost squeeze behind the headline
Total expenses surged 26.5% year-on-year, outpacing revenue growth. A key driver was a doubling of interest expense to ₹2 crore, according to the analysis. This was linked to funding ongoing expansion, as noted by mCapital.in.
The research suggests a broader industry margin pressure. A report from Plastindia.org in October 2026 noted that wholesale prices for raw plastic were rising faster than finished goods, squeezing processor margins.
Funding growth while profits thin
Capital expenditure remains a priority. The company had capital work in progress of ₹31.1 crore as of September 2026, supporting expansion, mCapital.in reported. This is partly funded by debt, which rose to ₹92.7 crore from ₹87.7 crore in March.
Live Chart
· SPL
(BSE)
ISIN: INE0RDR01012
The debt-to-equity ratio stands at 0.94. While elevated, it shows a slight improvement from 1.00 a year earlier. The balance between funding growth and managing leverage will be critical.
Key Points
- Revenue grew 21% year-on-year to ₹92 crore in Q2 FY27, but net profit declined 17% to ₹5 crore.
- A 26.5% jump in total expenses and a doubling of interest costs drove a 250-basis-point contraction in net profit margin.
- Borrowings increased to ₹92.7 crore to fund expansion, with capital work in progress at ₹31.1 crore.
- The stock fell 4.4% on the results day, reflecting market concern over the profitability squeeze.
Hexa Perspective
The quarter highlights a classic growth-versus-profitability tension. Swashthik Plascon is successfully growing its top line in a firm demand environment, but it is not yet capturing operating leverage.
The margin pressure from input costs and interest is a near-term headwind. Investors are weighing strong revenue momentum against the timeline for these expansion projects to translate into sustained, profitable growth.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.