Swashthik Plascon (SPL) Q4 FY26 Profit Dives 50% as Interest Costs Triple
The plastic packaging maker's Q4 net profit halved sequentially despite steady sales, as a sharp rise in interest expense squeezed margins.
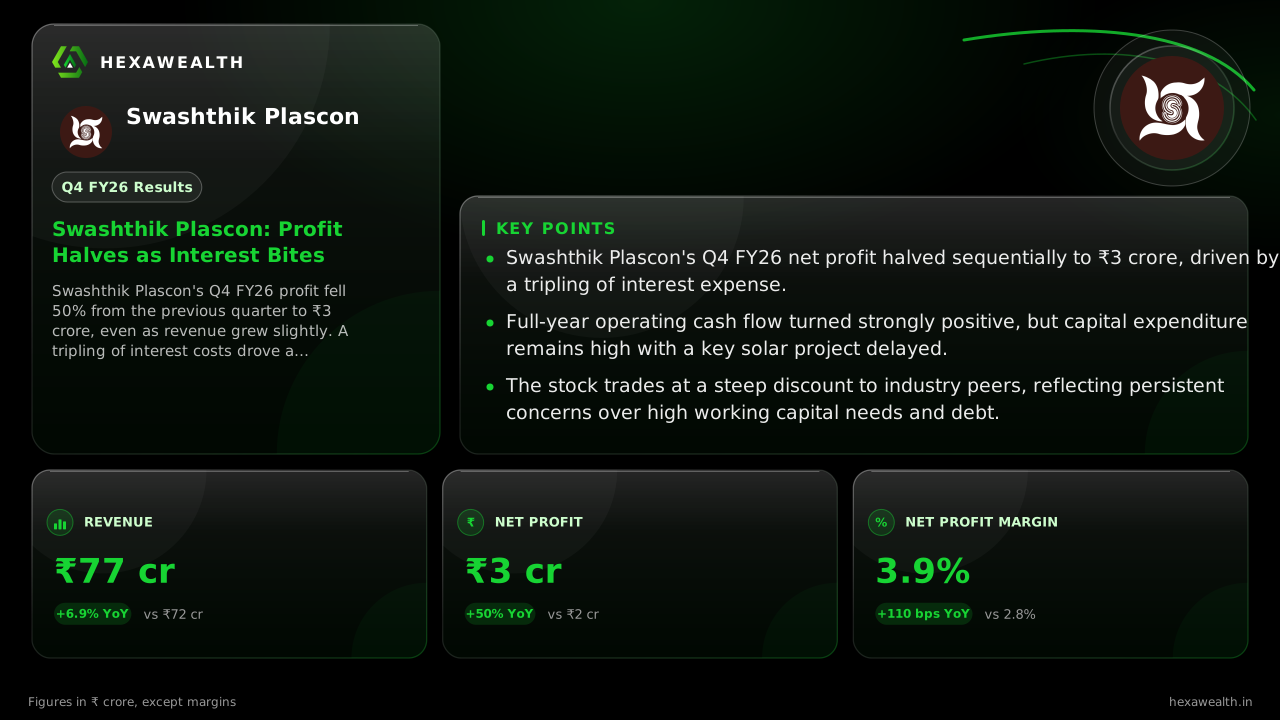
Swashthik Plascon's Q4 FY26 profit fell 50% from the previous quarter to ₹3 crore, even as revenue grew slightly. A tripling of interest costs drove a sharp 400 bps contraction in net profit margin.
For a regional plastic packaging maker like Swashthik Plascon, steady sales growth is often offset by the twin pressures of raw material costs and working capital financing. The March quarter showed that balance tipping, as a modest revenue increase was swamped by a sharp spike in borrowing costs.
Revenue for Q4 FY26 rose 6.9% year-on-year to ₹77 crore, but net profit fell 50% sequentially to ₹3 crore. The net profit margin contracted by 400 basis points from the previous quarter to 3.9%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q4 FY24: 60.0
- Revenue (₹ Cr), Q2 FY25: 72.0
- Revenue (₹ Cr), Q4 FY25: 72.0
- Revenue (₹ Cr), Q2 FY26: 76.0
- Revenue (₹ Cr), Q4 FY26: 77.0
- Profit (₹ Cr), Q4 FY24: 3.0
- Profit (₹ Cr), Q2 FY25: 4.0
- Profit (₹ Cr), Q4 FY25: 2.0
- Profit (₹ Cr), Q2 FY26: 6.0
- Profit (₹ Cr), Q4 FY26: 3.0
Revenue (₹ Cr)
- Revenue (₹ Cr), Q4 FY24: 60.0
- Revenue (₹ Cr), Q2 FY25: 72.0
- Revenue (₹ Cr), Q4 FY25: 72.0
- Revenue (₹ Cr), Q2 FY26: 76.0
- Revenue (₹ Cr), Q4 FY26: 77.0
Profit (₹ Cr)
- Profit (₹ Cr), Q4 FY24: 3.0
- Profit (₹ Cr), Q2 FY25: 4.0
- Profit (₹ Cr), Q4 FY25: 2.0
- Profit (₹ Cr), Q2 FY26: 6.0
- Profit (₹ Cr), Q4 FY26: 3.0
Net Profit Margin (%)
- Net Profit Margin (%), Q4 FY24: 5.0
- Net Profit Margin (%), Q2 FY25: 5.6
- Net Profit Margin (%), Q4 FY25: 2.8
- Net Profit Margin (%), Q2 FY26: 7.9
- Net Profit Margin (%), Q4 FY26: 3.9
| Metric | CurrentQ4 FY26 | Same quarter LYQ4 FY25 |
|---|---|---|
| Revenue (₹ Cr) | 77.0YoY +6.9% | 72.0 |
| Profit (₹ Cr) | 3.0YoY +50% | 2.0 |
| Net Profit Margin (%) | 3.9YoY +39% | 2.8 |
Why the bottom line buckled
A tripling of interest expense was the primary culprit, according to the financials. Interest cost surged to ₹4 crore in Q4 from ₹1 crore in the September quarter. This spike, as highlighted by Newboard research, reflects the cost of funding rising inventories and customer credit in a capital-intensive business.
While the company's operating margin remains healthy at 16% for the full year, this was not enough to shield the bottom line. The business model, dependent on resin prices and regional demand, leaves little room to absorb such financing shocks.
A cash flow turnaround with a catch
The full-year picture shows a significant shift. Operating cash flow swung to a positive ₹34 crore in FY26 from negative ₹19 crore the year before. This improvement, noted by Newboard, came from better working capital management.
Live Chart
· SPL
(BSE)
ISIN: INE0RDR01012
However, this was accompanied by a rise in capital work in progress to ₹30 crore, largely for an 8 MW solar plant. The company had expected this plant to be operational by February 2026, but it remained unfinished at year-end, delaying potential power cost savings.
The valuation disconnect
Swashthik Plascon trades at a P/E of 4.6, an 86% discount to the industry average of 33. This deep value reflects the market's concern over its financial structure. With debt-to-equity at 0.94 and inventory days stretching to 297, the company's need for constant capital is clear.
The recent half-year results for FY27, reported by MarketsMojo, show this tension continuing. Revenue grew over 20% but profit fell 6.2%, suggesting margin pressure is not a one-quarter event.
Key Points
- Swashthik Plascon's Q4 FY26 net profit halved sequentially to ₹3 crore, driven by a tripling of interest expense.
- Full-year operating cash flow turned strongly positive, but capital expenditure remains high with a key solar project delayed.
- The stock trades at a steep discount to industry peers, reflecting persistent concerns over high working capital needs and debt.
Hexa Perspective
The quarter underscores the fragility of Swashthik Plascon's earnings in a rising interest rate environment. Its profitability is highly sensitive to financing costs, which are fuelled by the inventory and receivables required to run its regional packaging business.
The positive cash flow generation is a welcome shift, but its sustainability depends on managing working capital as sales grow. Until the delayed solar plant is operational and provides cost relief, or resin price volatility eases, earnings are likely to remain under pressure. The market's deep discount prices in this ongoing balance sheet risk.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.