Solarium Green Energy (SOLARIUM) Q2 FY27 Revenue Triples as Profit Margin Squeezes
The solar firm's revenue jumped 165% year-on-year, but profit grew only 14% as a shift to lower-margin EPC work and new plant costs bit.
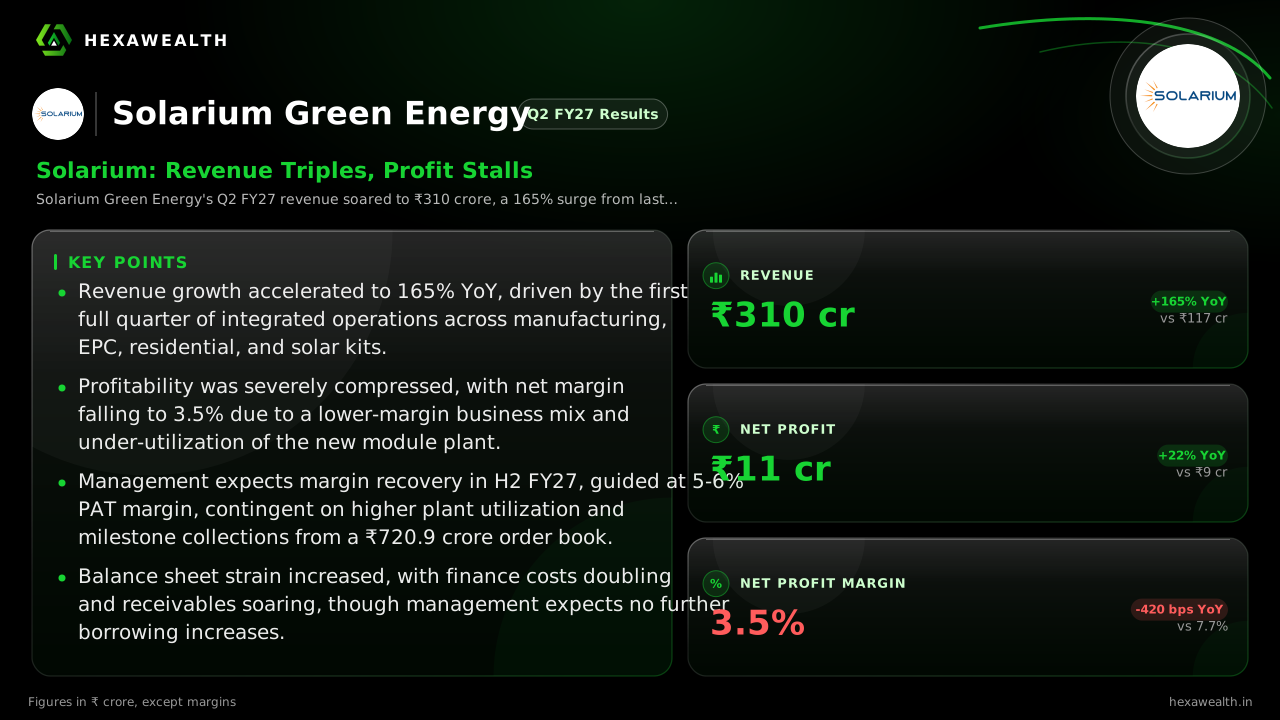
Solarium Green Energy's Q2 FY27 revenue soared to ₹310 crore, a 165% surge from last year. However, net profit grew a mere 14% to ₹11 crore as margins compressed sharply due to a new business mix and high fixed costs.
Solarium Green Energy’s transition to an integrated solar player delivered explosive top-line growth this quarter, but the cost of that shift arrived just as sharply. Revenue tripled as its new manufacturing line and large EPC projects kicked in, yet the profit line barely moved, highlighting a margin squeeze that defines the current phase.
The numbers tell a story of two speeds. Revenue for the quarter ended September 2026 was ₹310 crore, a 165% leap from the same period last year. Sequentially, sales grew 24% from the March quarter. Profit after tax, however, was flat quarter-on-quarter at ₹11 crore, and grew only 22% year-on-year.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY25: 82.0
- Revenue (₹ Cr), Q4 FY25: 148.0
- Revenue (₹ Cr), Q2 FY26: 117.0
- Revenue (₹ Cr), Q4 FY26: 251.0
- Revenue (₹ Cr), Q2 FY27: 310.0
- Profit (₹ Cr), Q2 FY25: 8.0
- Profit (₹ Cr), Q4 FY25: 11.0
- Profit (₹ Cr), Q2 FY26: 9.0
- Profit (₹ Cr), Q4 FY26: 11.0
- Profit (₹ Cr), Q2 FY27: 11.0
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY25: 82.0
- Revenue (₹ Cr), Q4 FY25: 148.0
- Revenue (₹ Cr), Q2 FY26: 117.0
- Revenue (₹ Cr), Q4 FY26: 251.0
- Revenue (₹ Cr), Q2 FY27: 310.0
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY25: 8.0
- Profit (₹ Cr), Q4 FY25: 11.0
- Profit (₹ Cr), Q2 FY26: 9.0
- Profit (₹ Cr), Q4 FY26: 11.0
- Profit (₹ Cr), Q2 FY27: 11.0
Net Profit Margin (%)
- Net Profit Margin (%), Q2 FY25: 9.8
- Net Profit Margin (%), Q4 FY25: 7.4
- Net Profit Margin (%), Q2 FY26: 7.7
- Net Profit Margin (%), Q4 FY26: 4.4
- Net Profit Margin (%), Q2 FY27: 3.5
| Metric | CurrentQ2 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|
| Revenue (₹ Cr) | 310.0YoY +165% | 117.0 |
| Profit (₹ Cr) | 11.0YoY +22% | 9.0 |
| Net Profit Margin (%) | 3.5YoY -55% | 7.7 |
Why the profit didn't follow sales
Management explained the gap on the earnings call, as reported by AlphaStreet and StockSigma. The business mix shifted decisively toward large engineering, procurement, and construction (EPC) projects and module sales, which carry materially lower gross margins than the company's legacy residential installation work. This institutional work accounted for 84% of revenue in the half-year.
Simultaneously, the new 1.23 GW module plant in Ahmedabad, commissioned in March, incurred six months of fixed costs—depreciation and interest—against only about 2.5 months of manufacturing revenue. The plant received its crucial ALMM certification only in July, delaying sales. As a result, net profit margin collapsed to 3.5%, down 420 basis points from a year ago.
The costs that will not fall soon
Finance costs doubled year-on-year to ₹8.3 crore, reflecting the plant's term loan and swelling working capital needs for EPC execution. Depreciation surged to ₹3.4 crore from ₹0.5 crore last year as the new asset began full depreciation. Trade receivables ballooned to ₹281.9 crore, tying up cash and keeping working capital pressure high.
Live Chart
· SOLARIUM
(BSE)
ISIN: INE0W0H01017
Management, however, sees a path to relief. They told analysts on the call that these costs have peaked. With ALMM listing now in place, plant utilization rose to 75-80% by September. Higher sales volumes should absorb the fixed overhead. For the second half of FY27, they guided for a net profit margin recovery to 5-6%.
Key Points
- Revenue growth accelerated to 165% YoY, driven by the first full quarter of integrated operations across manufacturing, EPC, residential, and solar kits.
- Profitability was severely compressed, with net margin falling to 3.5% due to a lower-margin business mix and under-utilization of the new module plant.
- Management expects margin recovery in H2 FY27, guided at 5-6% PAT margin, contingent on higher plant utilization and milestone collections from a ₹720.9 crore order book.
- Balance sheet strain increased, with finance costs doubling and receivables soaring, though management expects no further borrowing increases.
Hexa Perspective
The quarter confirms Solarium's successful scale-up into a multi-segment solar company, with revenue now running at an annualized pace above ₹600 crore. The tension is that this growth came at the expense of profitability, a trade-off that must reverse in the coming quarters for the model to prove itself.
The promised margin recovery hinges entirely on execution: filling the module plant and converting the large order book into timely, collected revenue. With a price-to-earnings ratio of 9.8, trading at a 58% discount to the industry average, the market is pricing in significant skepticism. Investors are weighing the clear top-line momentum against the uncertainty of whether margins can climb back to the company's own 5-6% guide.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.