Bharatrohan Airborne Innovations (BHARATROHAN) Q4 FY26' Revenue Triples as Profitability Fades
The agri-tech firm's Q4 FY26 sales surged 271% year-on-year, but net profit was flat as heavy spending and a new US venture weighed on margins.
Bharatrohan Airborne Innovations reported a transformative year with revenue tripling in Q4 FY26. However, profitability did not keep pace, as margins collapsed from a high base due to aggressive expansion and rising costs.
For Bharatrohan Airborne Innovations, FY26 was a year of explosive top-line growth as its drone and hyperspectral imaging services scaled. The final quarter captured this transformation, but also revealed the cost of that expansion as profitability faded under the weight of new investments.
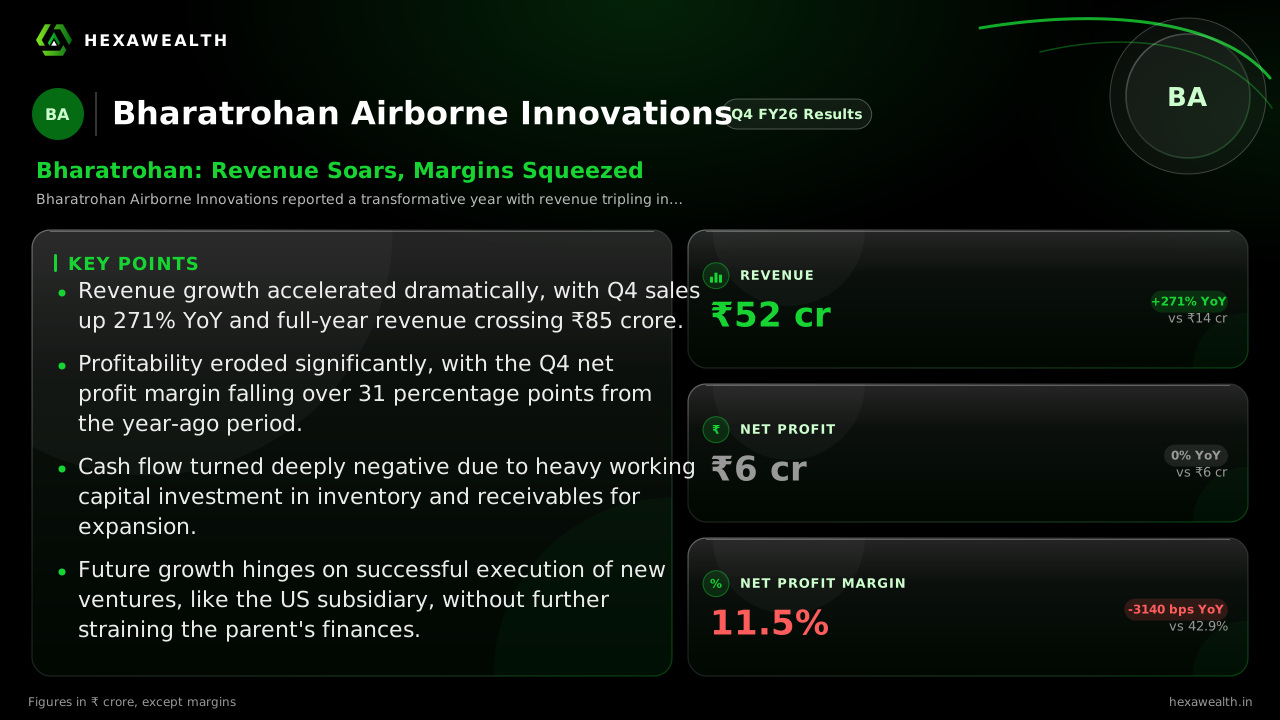
Revenue for the March 2026 quarter jumped 271% year-on-year to ₹52 crore, while net profit remained flat at ₹6 crore. Sequentially, sales grew 58% from the September quarter, with profit up 20%. The stark divergence is in the margins: the net profit margin collapsed from 42.9% a year ago to 11.5% this quarter.
Revenue & profit
Revenue (₹ Cr.)
Net Profit (₹ Cr.)
Net Profit Margin (%)
| Metric | CurrentQ4 FY26 | Same quarter LYQ4 FY25 |
|---|---|---|
| Revenue (₹ Cr.) | 52.0YoY +271% | 14.0 |
| Net Profit (₹ Cr.) | 6.0YoY 0% | 6.0 |
| Net Profit Margin (%) | 11.5YoY -73% | 42.9 |
The Growth Engine and Its Cost
The revenue surge was driven by scaling core agricultural services and a strategic push into new sectors. According to a ScanX report, the company diversified into solar energy monitoring and industrial inspections, leveraging its hyperspectral technology. It served over 58,000 farmers across 2.6 lakh acres.
This expansion came at a price. Total expenses ballooned 450% year-on-year in Q4. A key factor was a sharp rise in inventory and receivables, which grew by ₹29 crore and ₹15 crore respectively over the full year, locking up cash. This contributed to a negative operating cash flow of ₹27.74 crore for FY26, as per the company's financials.
Funding an Ambitious Future
To fund its growth, Bharatrohan is looking beyond its balance sheet. Its US subsidiary, BharatRohan INC, is in discussions to raise up to $5 million via a private placement, as noted by mCapital. The parent will retain majority control without providing capital or guarantees.
This move is strategic but carries near-term risks. mCapital's analysis suggests the US spice brand launch could add revenue but also create an annual drag of ₹1-3 crore on attributable profit, further pressuring margins. The company's own cash flow statement shows it funded an aggressive ₹7.5 crore in estimated fixed asset additions in FY26 through financing activities.
Key Points
- Revenue growth accelerated dramatically, with Q4 sales up 271% YoY and full-year revenue crossing ₹85 crore.
- Profitability eroded significantly, with the Q4 net profit margin falling over 31 percentage points from the year-ago period.
- Cash flow turned deeply negative due to heavy working capital investment in inventory and receivables for expansion.
- Future growth hinges on successful execution of new ventures, like the US subsidiary, without further straining the parent's finances.
Hexa Perspective
The quarter underscores Bharatrohan's transition from a niche service provider to a scaled agri-tech platform. The 200%+ full-year revenue growth is impressive, but the margin compression reveals the operational intensity of this model.
The path ahead involves a delicate balance. The company must monetize its growing asset base and farmer network to improve cash conversion. Success in non-agri segments and the US venture could provide the next leg of growth, but they also introduce execution risk and near-term profit dilution. Investors are essentially betting on the company's ability to translate its technological edge into sustainable, profitable scale.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.