Shivashrit Foods (SHIVASHRIT) Q2 FY27 Profit Surges 24% Despite a 7% Drop in Revenue
The potato flake maker posted a sharp rise in net profit on lower costs and higher other income, even as quarterly revenue fell year-on-year.
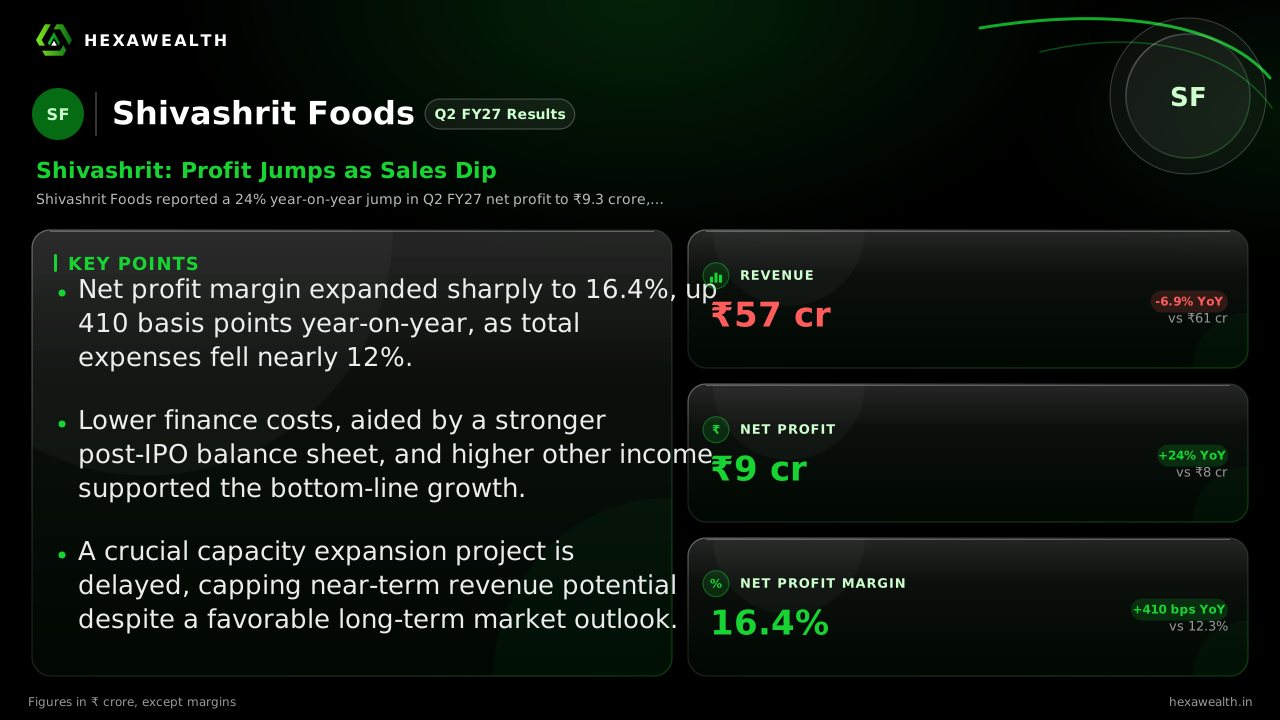
Shivashrit Foods reported a 24% year-on-year jump in Q2 FY27 net profit to ₹9.3 crore, driven by cost controls and higher other income. This came despite a nearly 7% decline in revenue from operations during the quarter.
For a company that turns potatoes into a core ingredient for snack giants, a drop in sales would typically spell trouble. Shivashrit Foods, however, turned that challenge into a showcase of margin discipline in the September quarter, delivering a 24% profit jump on a smaller revenue base.
The numbers tell a story of efficiency over growth. Revenue from operations fell 6.9% year-on-year to ₹56.94 crore. Yet, net profit climbed to ₹9.34 crore, pushing the net profit margin to 16.4%—a sharp 410 basis point improvement from a year ago.
Revenue & profit
Revenue (₹ Cr)
Net Profit (₹ Cr)
Net Profit Margin
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ4 FY26 (Mar 2026) |
|---|---|---|
| Revenue (₹ Cr) | 56.94 | 52.33 |
| Net Profit (₹ Cr) | 9.34 | 6.54 |
| Net Profit Margin | 16.4% | 12.5% |
Where the profit came from
A significant drop in total expenses, down nearly 12% year-on-year, was the primary driver. Lower interest and depreciation costs provided a tailwind. Interest expense fell 25%, which a Sharpely.in financial report links to an improved debt-to-equity ratio following the company's IPO.
Other income also played a role, nearly doubling year-on-year to ₹0.97 crore. This boost, while not from core operations, helped lift the bottom line. The result was a profit before tax that grew 25% despite the revenue decline.
The expansion delay and the road ahead
The quarter's profitability is a positive, but a key growth lever remains stuck. Research from mCapital notes a critical capacity expansion project, meant to triple daily output, has been delayed. A CARE Ratings report filed by the company confirms the delay, flagging it as a monitorable.
This puts the company in a holding pattern. Current capacity utilization was 81% in FY25, per mCapital. Until the new plant is operational, top-line growth may remain constrained, leaving further profit gains dependent on continued cost control.
Key Points
- Net profit margin expanded sharply to 16.4%, up 410 basis points year-on-year, as total expenses fell nearly 12%.
- Lower finance costs, aided by a stronger post-IPO balance sheet, and higher other income supported the bottom-line growth.
- A crucial capacity expansion project is delayed, capping near-term revenue potential despite a favorable long-term market outlook.
Hexa Perspective
The quarter reveals a company adept at managing what it can control—costs and balance sheet health—amidst external constraints on sales. The margin expansion is impressive but partially reliant on non-operational income and lower interest, gains that may not repeat at the same magnitude.
The delayed expansion is the pivot. Until new capacity comes online, Shivashrit's story is one of efficient stewardship of existing assets, not breakout growth. Investors are left weighing solid near-term profitability against the execution risk and timeline of its promised scale-up.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.