On Door Concepts (ONDOOR) Q2 FY27 Profit Drops 30% Sequentially as Costs Climb
The convenience retailer posted solid yearly growth but saw a sharp quarterly contraction in profit and margins due to rising employee and depreciation costs.
On Door Concepts reported a 22% yearly rise in Q2 FY27 net profit, but profit fell 30% from the prior quarter. Revenue also declined sequentially, while employee and depreciation costs surged, squeezing margins.
For a neighbourhood retailer, growth is about more stores and more orders from existing ones. On Door Concepts has relied on the latter, with its store count nearly static, making each quarter's sales efficiency critical. The September quarter delivered yearly growth but a sharp sequential step back, as rising costs bit into profitability.
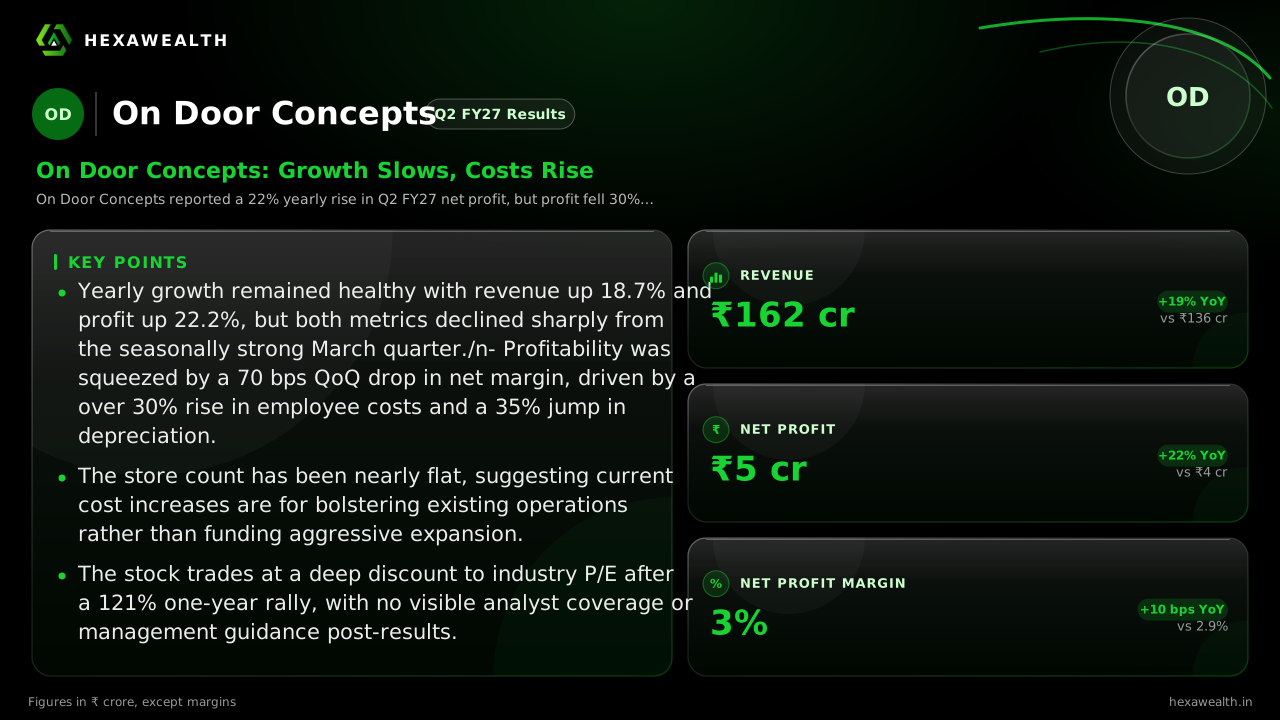
The numbers show a business in transition. Revenue of ₹161.95 crore was up 18.7% from a year ago but down 12% from the March quarter. Net profit of ₹4.79 crore grew 22.2% year-on-year but fell 30.2% sequentially. The net profit margin contracted by 70 basis points from the prior quarter to 3.0%.
Revenue & profit
Revenue (₹ Cr)
Net Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ4 FY26 (Mar 2026) |
|---|---|---|
| Revenue (₹ Cr) | 161.95 | 184.06 |
| Net Profit (₹ Cr) | 4.79 | 6.86 |
| Net Profit Margin (%) | 3.0 | 3.7 |
Why the squeeze hit now
Two fixed costs rose sharply, eating into the bottom line. Employee costs jumped over 30% quarter-on-quarter, while depreciation expense surged nearly 35%. According to a report from Newboard, the company's store network has grown slowly, moving from 63 to 65 stores over 18 months. This suggests the cost increases are for supporting existing operations and technology, not rapid expansion.
A seasonal dip also played a role. The prior March quarter is often stronger for retailers, and the sequential revenue decline of 12% points to a post-festival normalization. With sales softer, the higher fixed costs had a magnified impact on margins.
The runway in Tier-2 cities
Long-term demand is not the issue. Research from Credence Research projects India's online grocery market to grow at 29.5% annually through 2035, with significant potential in smaller cities. On Door's focus on Madhya Pradesh aligns with this, but it operates in a crowded space against large quick-commerce apps expanding beyond metros.
The company's franchise-owned, company-operated (FOCO) model, noted by StockScans, keeps capital spending low. However, the lack of new store openings raises questions about its ability to capture the growth wave through physical density. Most sales growth is currently coming from existing stores, online orders, and bulk sales.
The market's muted reaction
The stock has had a spectacular run, up 121.8% over the past year, closing at ₹273 on November 13. This values the company at a P/E of 17.7, a significant discount to the industry average of 64.5. No major brokerages have published ratings or target changes following these results, according to data from Sharpely, indicating limited institutional coverage.
Foreign institutional investors held a 14.81% stake as of the last filing, per Alfafinder. The lack of analyst estimates or guidance from the company leaves investors to weigh the strong yearly trends against the clear near-term cost pressures.
Key Points
- Yearly growth remained healthy with revenue up 18.7% and profit up 22.2%, but both metrics declined sharply from the seasonally strong March quarter./n- Profitability was squeezed by a 70 bps QoQ drop in net margin, driven by a over 30% rise in employee costs and a 35% jump in depreciation.
- The store count has been nearly flat, suggesting current cost increases are for bolstering existing operations rather than funding aggressive expansion.
- The stock trades at a deep discount to industry P/E after a 121% one-year rally, with no visible analyst coverage or management guidance post-results.
Hexa Perspective
The quarter frames the challenge of scaling a capital-light franchise model. Growth is evident year-on-year, but profitability is fragile when fixed costs rise ahead of sales. The 30% quarterly profit drop shows how thin the operating buffer is.
The coming quarters will test whether these cost increases are one-time investments in systems and staff that will drive future efficiency, or a new, higher baseline for expenses. With the store network expanding slowly, the path to leverage relies on squeezing more sales from existing assets—a task that becomes harder if consumer demand in its Tier-2 cities softens.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.