Bemco Hydraulics (BEMHY) Q2 FY27 Profit Plunges 48% as Costs Outpace Revenue
The hydraulic press maker's September quarter profit fell sharply despite a revenue uptick, as total expenses surged over 16% year-on-year.
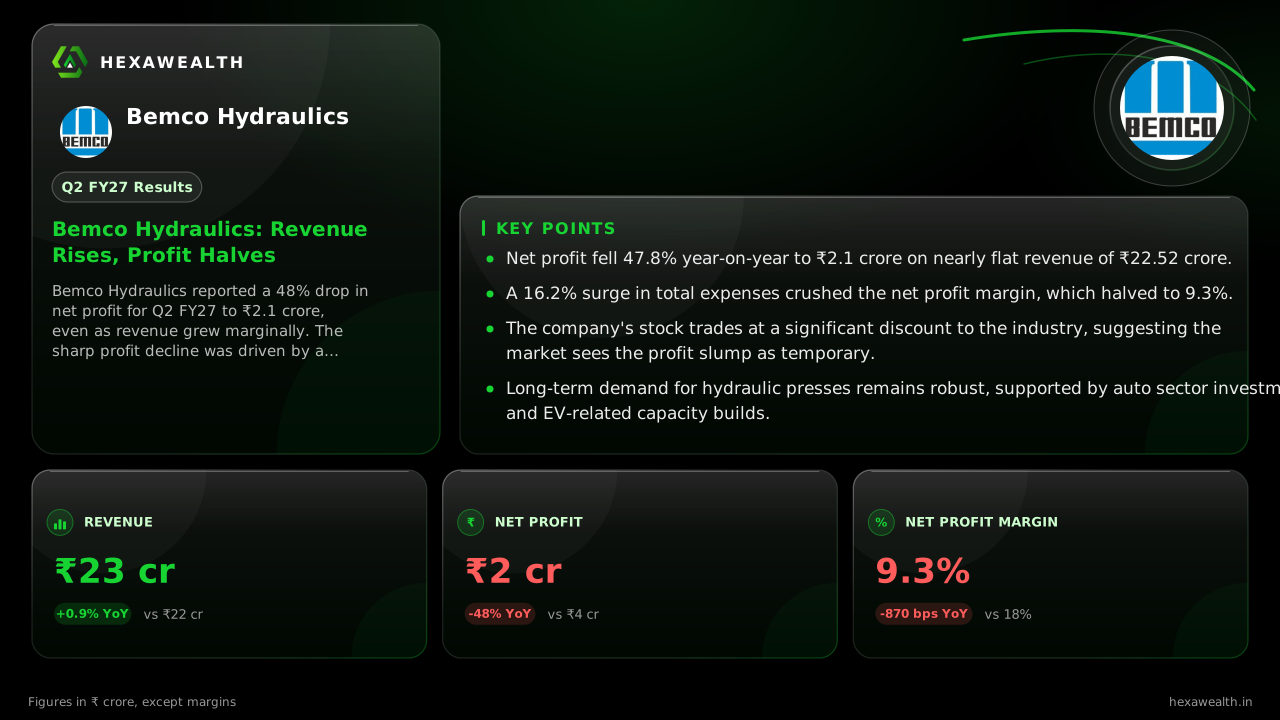
Bemco Hydraulics reported a 48% drop in net profit for Q2 FY27 to ₹2.1 crore, even as revenue grew marginally. The sharp profit decline was driven by a significant surge in total expenses, which squeezed the net profit margin down to 9.3%.
For a capital goods maker like Bemco Hydraulics, a quarter where sales hold steady but profits collapse is a story of costs running ahead of pricing. The September quarter delivered exactly that, with revenue inching up but net profit nearly halving from a year ago.
The numbers tell a clear tale of pressure. Revenue was ₹22.52 crore, nearly flat compared to ₹22.33 crore in Q2 FY26. Net profit, however, plunged 47.8% to ₹2.1 crore. The net profit margin contracted sharply to 9.3%, down from 18.0% a year earlier.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ1 FY27 (Jun 2026) |
|---|---|---|
| Revenue (₹ Cr) | 22.52 | 15.58 |
| Profit (₹ Cr) | 2.10 | 2.72 |
| Net Profit Margin | 9.3% | 17.5% |
Where the money went
The profit squeeze was not due to a one-off charge. According to the company's filing, profit before exceptional items and tax was ₹3.1 crore, down 41.7% year-on-year. The main driver was a 16.2% jump in total expenses, which far outpaced the minimal revenue growth.
This suggests underlying cost inflation in materials, employee benefits, or other operational outlays. The quarterly filing, as reported by Alfafinder, showed an operating margin of 13.3%, down from 23.3% a year ago, confirming the core profitability erosion.
The market's long-term bet
Despite the weak quarter, the stock's valuation tells a different story. At a P/E of 27.5, Bemco trades at a 37% discount to its industry P/E of 43.5. This gap reflects the market's view that the current margin pressure is cyclical, not terminal, for a company supplying every major Indian automaker.
Industry reports from Mordor Intelligence point to strong structural demand. The Indian industrial press market is forecast to grow at nearly 8% annually, driven by automotive electrification and capacity expansion. This long-term tailwind may be cushioning the stock from a steeper fall.
Key Points
- Net profit fell 47.8% year-on-year to ₹2.1 crore on nearly flat revenue of ₹22.52 crore.
- A 16.2% surge in total expenses crushed the net profit margin, which halved to 9.3%.
- The company's stock trades at a significant discount to the industry, suggesting the market sees the profit slump as temporary.
- Long-term demand for hydraulic presses remains robust, supported by auto sector investment and EV-related capacity builds.
Hexa Perspective
This quarter highlights the vulnerability of engineering firms to input cost volatility when they cannot immediately pass it on. The nearly 900 basis point margin compression is severe and needs a clear reversal in the coming quarters to restore investor confidence in the earnings trajectory.
The discount to industry valuation provides a margin of safety, but it is justified only if Bemco demonstrates pricing power or cost control as order execution picks up. Investors are effectively betting that the strong industry outlook will translate into better realizations before costs rise further.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.