All posts

Follow Us

LinkedInInstagramX
Quarterly ResultsArchiveLast updated 14 November 20263 min read

Maan Aluminium (MAANALU) Q2 FY27 Profit Crashes 85% Despite 46% Revenue Jump

The aluminium extruder's September quarter saw a severe margin squeeze as input costs surged far faster than sales, leaving net profit at just ₹0.89 crore.

By Abhinav Swaroop, CFA, Chief Business Officer: Hexawealth · Created 14 November 2026

Maan Aluminium's Q2 FY27 revenue surged 46% year-on-year to ₹279.48 crore, but net profit collapsed 85% to ₹0.89 crore. The dramatic margin squeeze was driven by a massive rise in purchases of stock-in-trade, which outpaced revenue growth.

For an aluminium extruder building a high-value manufacturing business, the September quarter was a test of whether sales growth could outrun costs. Maan Aluminium posted a 46% revenue jump, but profit fell 85% as costs surged even faster.

The numbers tell a story of top-line momentum and bottom-line collapse. Revenue rose to ₹279.48 crore, a 20.5% sequential increase. Yet net profit shrank to just ₹0.89 crore, down 71% from the June quarter. The net profit margin was a wafer-thin 0.3%.

Revenue & profit

Revenue (₹ Cr)

Profit (₹ Cr)

Net Profit Margin

MetricCurrentQ2 FY27 (Sep 2026)PreviousQ1 FY27 (Jun 2026)
Revenue (₹ Cr)
279.48
231.86
Profit (₹ Cr)
0.89
3.10
Net Profit Margin
0.3%
1.3%

The Cost That Ate the Profit

The story is in the expenses. Total costs rose 50.3% year-on-year, outpacing the 44.9% rise in total income. According to a report by Multibagg.ai, purchases of stock-in-trade soared by ₹84.43 crore to ₹182.46 crore. This was the largest driver of the margin squeeze.

Interest expense also jumped 53% sequentially, though it remained below last year's level. Management has projected capital expenditure of ₹40-50 crore for FY27, which may explain the higher borrowing costs.

A Pivot Under Pressure

The company is pivoting from commodity extrusion to high-value conversion, a strategy highlighted by MarketPing. It has a contract with Tata and is ramping up a precision tubing facility in Dewas. This transition requires heavy investment before the promised margin benefits arrive.

Current capacity utilisation is low, around 25% of its expanded 24,000-tonne capacity. The promised ramp-up to 75-80% over three years is critical for absorbing fixed costs and improving profitability.

The Market's Read

There were no formal analyst estimates to beat or miss. The stock closed at ₹102.06 the day before the results, down 24% over the past year. One technical rating service, MarketsMojo, recently upgraded the stock from 'Strong Sell' to 'Sell' based on price momentum, not fundamentals.

The valuation reflects deep skepticism. The stock trades at a P/E of 2.4, an 83% discount to the industry average of 13.6. Investors are clearly pricing in the persistent margin weakness.

Key Points

  • Revenue grew 46% year-on-year to ₹279.48 crore, but net profit collapsed 85% to ₹0.89 crore due to a severe cost surge.
  • The primary driver was a massive ₹84.43 crore increase in purchases of stock-in-trade, which far outpaced sales growth.
  • The company's strategic pivot to high-value manufacturing is ongoing, but current capacity utilisation remains low at around 25%.
  • The stock trades at a significant discount to the sector, reflecting deep investor concern over profitability.

Hexa Perspective

The quarter exposes the raw tension in Maan Aluminium's transition. Revenue growth is strong, confirming demand for its products. But the cost structure is volatile and currently overwhelming.

The path forward hinges on two factors: stabilising input costs and successfully ramping up high-margin capacity. Until the Dewas facility and other value-added projects contribute meaningfully, profits will remain under severe pressure from commodity price swings and low utilisation. The market's deep discount suggests it is waiting for proof that the pivot can actually deliver earnings.

Share or follow HexaWealth

Also read

Want this applied to your portfolio?

Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.
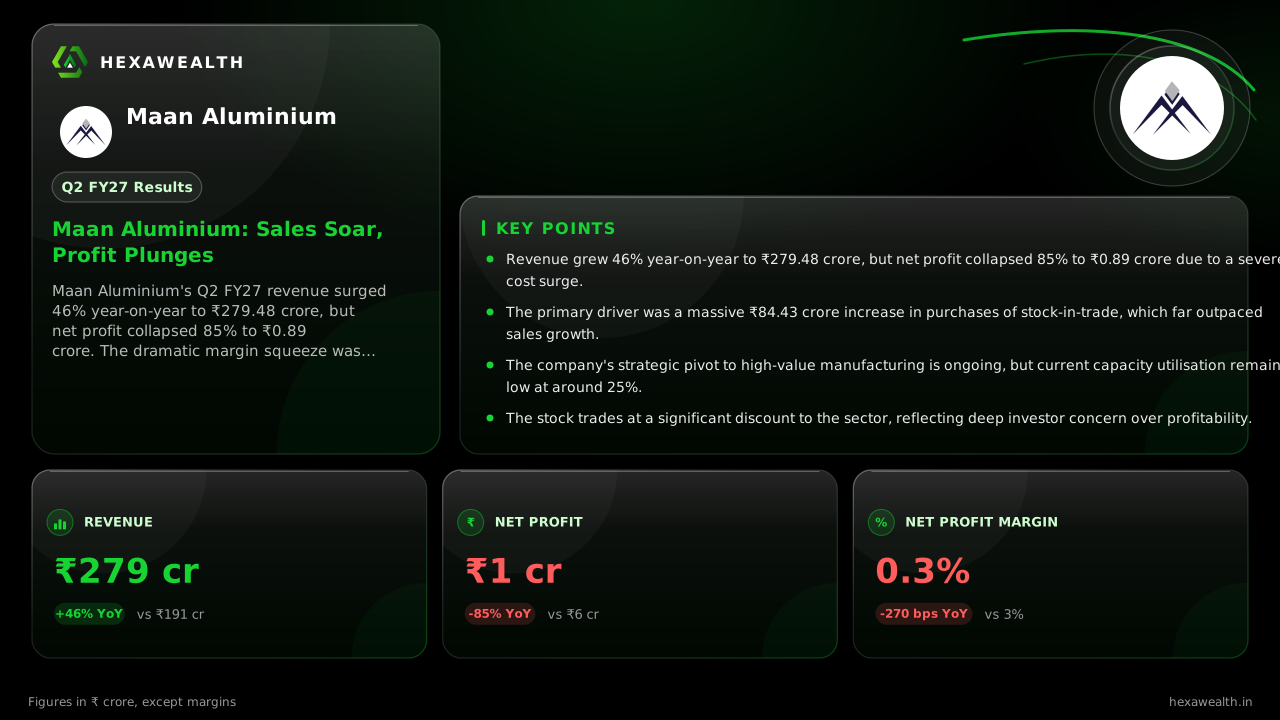
Maan Aluminium (MAANALU) Q2 FY27 results, revenue and profits.

Frequently asked questions

What were Maan Aluminium's Q2 FY27 results?
Maan Aluminium reported Q2 FY27 revenue of ₹279.48 crore, a 46.3% increase year-on-year. However, net profit plunged 84.6% to just ₹0.89 crore for the quarter ended September 2026, as a massive rise in input costs severely compressed margins.
Why did Maan Aluminium's profit fall despite higher revenue in Q2 FY27?
Maan Aluminium's profit fell because total expenses rose faster than income. According to Multibagg.ai, purchases of stock-in-trade surged by ₹84.43 crore year-on-year. This 50.3% jump in total costs far outpaced the 44.9% growth in total income, crushing profitability.
What was Maan Aluminium's net profit margin in Q2 FY27?
Maan Aluminium's net profit margin was just 0.3% in Q2 FY27, down from 1.3% in the previous quarter and 3.0% in the same quarter last year. This 270 basis point year-on-year decline highlights the severe margin pressure the company faced.
What caused the sharp drop in Maan Aluminium's Q2 profit margin?
The sharp margin drop was primarily due to a surge in input costs, specifically purchases of stock-in-trade. This line item rose by ₹84.43 crore year-on-year to ₹182.46 crore, as reported by Multibagg.ai. The cost increase dramatically outpaced revenue growth.
Did Maan Aluminium's Q2 FY27 results beat analyst estimates?
There is no evidence of formal analyst estimates for Maan Aluminium's Q2 FY27 results in the available research. The company does not appear to be widely covered by brokerages, so the results were not framed against a consensus forecast.
What is Maan Aluminium's capacity expansion plan?
Maan Aluminium has doubled its extrusion capacity to 24,000 tonnes per annum but is currently utilising only about 25% of it. Management aims to reach 75-80% utilisation over three years and has a capex plan of ₹40-50 crore for FY27 to support its shift to high-value manufacturing.
What is the status of Maan Aluminium's Dewas precision tubing project?
According to MarketPing, the Dewas precision tubing facility is a strategic project targeting aerospace and defense applications. The plant's start-up has been delayed and is now targeted for mid-next year. It is expected to be a low-volume, high-margin operation.
How did Maan Aluminium's stock price react to the Q2 results?
The stock closed at ₹102.06 on November 13, 2026, the day before the results were announced. Over the past year, the share price has fallen 23.7%, reflecting broader concerns about the company's profitability and the challenging cost environment.
What is Maan Aluminium's valuation compared to the industry?
Maan Aluminium trades at a significant discount to its sector. Its P/E ratio is 2.4, which is 82.6% below the industry average P/E of 13.6. This discount underscores the market's cautious view on its earnings potential.
Have any brokerages changed their rating on Maan Aluminium after Q2 results?
No brokerage rating changes were found following the Q2 results. However, MarketsMojo, a technical rating service, upgraded the stock from 'Strong Sell' to 'Sell' in early November based on improved price momentum, not fundamentals.
Maan Aluminium September revenue rose 46%, profit fell 85%
For the September 2026 quarter, Maan Aluminium's revenue from operations rose 46% year-on-year to ₹279.48 crore. However, its net profit fell 85% to ₹0.89 crore, as a massive increase in purchases of stock-in-trade caused total expenses to outpace income growth.
Maan Aluminium Q2 FY27 results order book
The available research on Maan Aluminium's Q2 FY27 results does not provide specific details about its order book. The commentary focuses on the company's strategic pivot to high-value contracts and capacity ramp-up, rather than disclosing a quantified order backlog.