NIBE Q2 FY27 Profit Inches Positive as Defence Order Execution Begins
The defence manufacturer turned a slim profit on higher revenue, but surging interest and depreciation costs underscore the capital intensity of its growth.
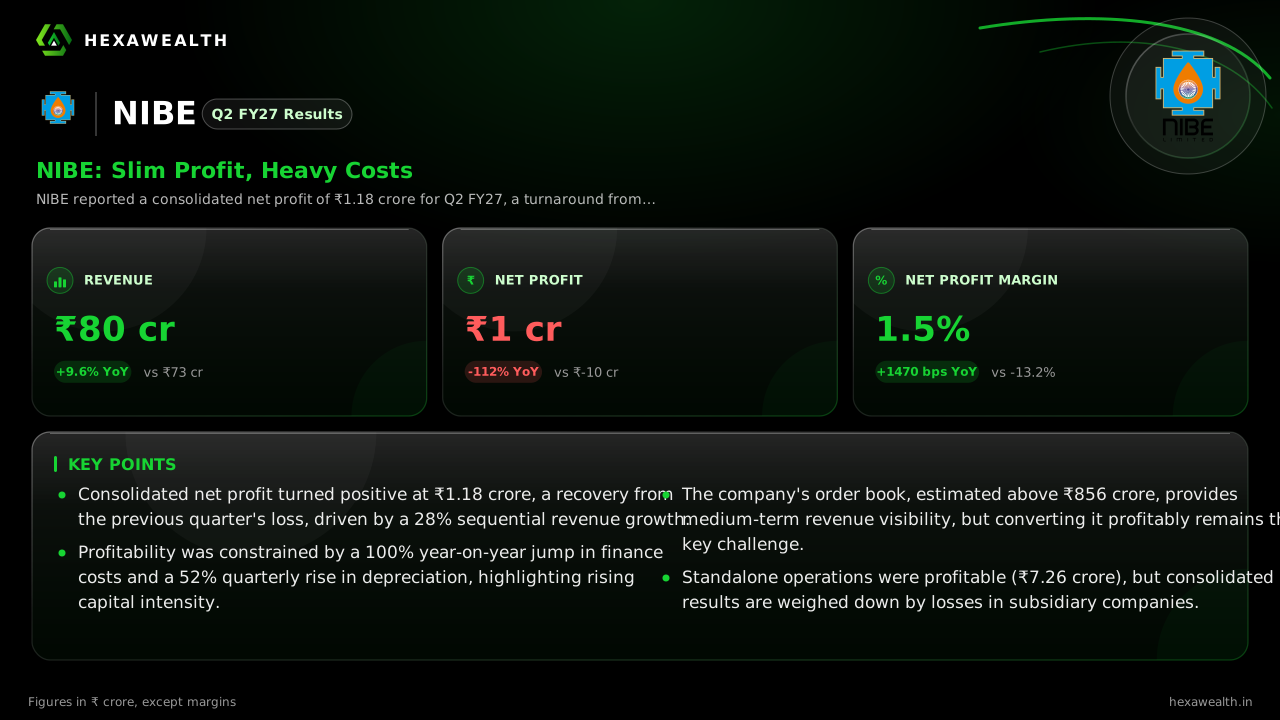
NIBE reported a consolidated net profit of ₹1.18 crore for Q2 FY27, a turnaround from last quarter's loss. Revenue grew 9.6% year-on-year to ₹80.38 crore, though profitability was pressured by a sharp rise in finance and depreciation costs.
For NIBE, a quarter defined by the promise of massive defence orders, the September results were a first test of execution. The company turned a slim profit, but the financials reveal the heavy costs of building capacity for that future.
The numbers show a business in transition. Revenue of ₹80.38 crore grew 10% from a year ago and jumped 28% from the prior quarter. This pushed the company to a net profit of ₹1.18 crore, a welcome shift from a ₹12 crore loss in Q1. Yet the profit margin remains wafer-thin at 1.5%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 80.38YoY +9.6% | 63.01 | 73.37 |
| Profit (₹ Cr) | 1.18YoY +112% | -12.00 | -9.69 |
| Net Profit Margin | 1.5%YoY +111% | -19.0% | -13.2% |
Why the profit was so slender
A closer look at expenses explains the modest bottom line. While total expenses fell year-on-year, two costs surged. Finance costs doubled to ₹3.45 crore, and depreciation rose 52% sequentially to ₹6.55 crore. According to a report by Stockwatch, this reflects the capital intensity of ramping up for large contracts like the ₹563 crore Loiter Munition System order secured in August.
The company's standalone performance was stronger, with a net profit of ₹7.26 crore. The consolidated figure is dragged down by subsidiary losses, a point noted in the filing highlighted by Blacklitt. This structural drag adds another layer of complexity to the profitability story.
The long road of order execution
Investors are watching how NIBE converts its ₹856+ crore order book, as estimated by Stockwatch, into steady revenue and earnings. The recent ₹1,347 crore capital raise is earmarked for capacity expansion to support this execution over the next 2-3 years. The near-term outlook hinges on managing the associated rise in interest and depreciation without eroding margins further.
Market sentiment remains cautious, with analyst coverage described as sparse by Stockwatch. The wide range in price targets reflects the high uncertainty around execution timelines and final profitability. Foreign institutional investors have steadily increased their stake over the past year, signaling long-term confidence amidst the quarterly volatility.
Key Points
- Consolidated net profit turned positive at ₹1.18 crore, a recovery from the previous quarter's loss, driven by a 28% sequential revenue growth.
- Profitability was constrained by a 100% year-on-year jump in finance costs and a 52% quarterly rise in depreciation, highlighting rising capital intensity.
- The company's order book, estimated above ₹856 crore, provides medium-term revenue visibility, but converting it profitably remains the key challenge.
- Standalone operations were profitable (₹7.26 crore), but consolidated results are weighed down by losses in subsidiary companies.
Hexa Perspective
NIBE's quarter is a story of two halves: the top-line recovery meeting the bottom-line squeeze. The return to profit is a necessary first step, but the surge in fixed costs confirms that scaling defence manufacturing is a capital-heavy endeavour. The next few quarters will test whether revenue growth from the large order book can outpace the climb in interest and depreciation. For now, the path to sustained, healthy margins looks long, and the stock's premium valuation appears to be betting heavily on flawless execution ahead.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.