Lamosaic India (LAMOSAIC) Q2 FY27's Profit Returns on Surging Revenue, But Margins Tell a Different Story
The decorative laminates trader saw revenue nearly double year-on-year, but profitability lagged as costs rose even faster.
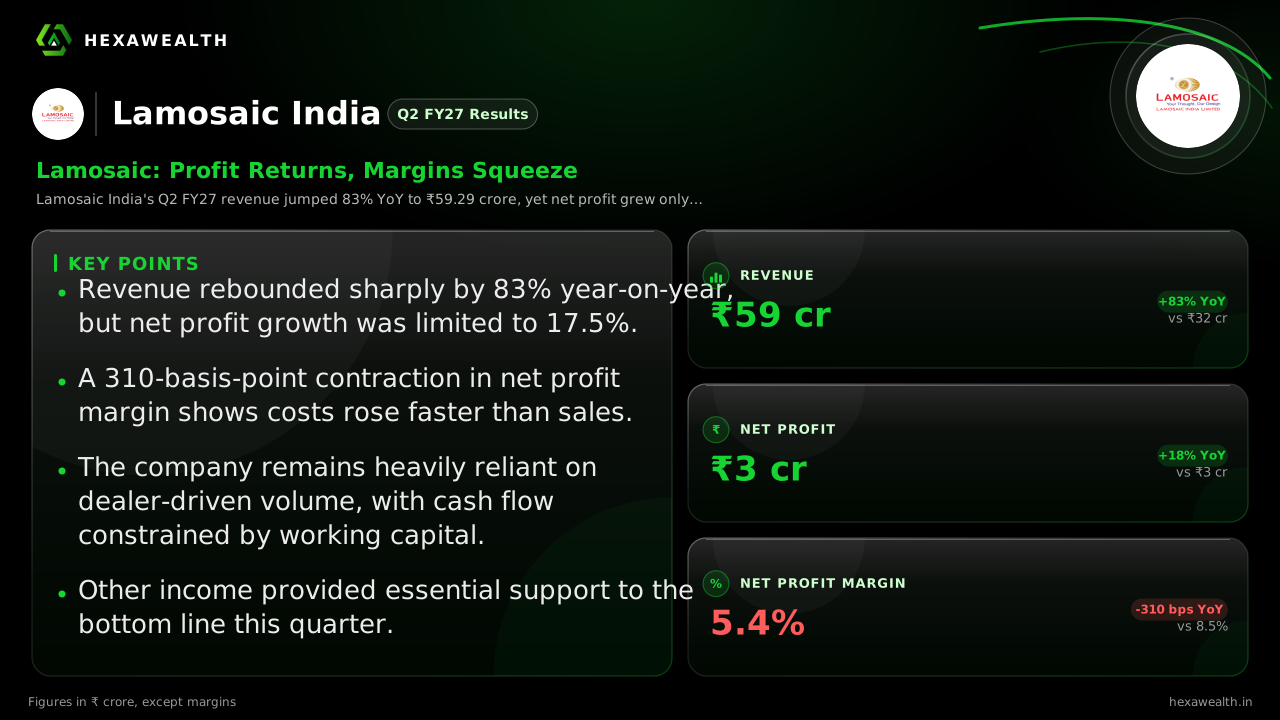
Lamosaic India's Q2 FY27 revenue jumped 83% YoY to ₹59.29 crore, yet net profit grew only 17.5%. The gap highlights a sharp margin squeeze as expenses outpaced sales growth.
For Lamosaic India, a trader of decorative laminates and plywood, the September quarter was about volume recovery. After a sharp dip a year ago, sales roared back, but the path to profit was far narrower.
The numbers show a business that grew its top line dramatically but struggled to keep earnings in step. Revenue for Q2 FY27 stood at ₹59.29 crore, an 83% jump from the same period last year. Net profit was ₹3.23 crore, a 17.5% increase.
Revenue & profit
Revenue (₹ Cr)
Net Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ4 FY26 (Mar 2026) |
|---|---|---|
| Revenue (₹ Cr) | 59.29 | 69.71 |
| Net Profit (₹ Cr) | 3.23 | -1.08 |
| Net Profit Margin (%) | 5.4 | -1.5 |
The profit margin tells the real story. At 5.4%, it is 310 basis points lower than the 8.5% margin from a year ago. This squeeze happened because total expenses surged 96.7% year-on-year, even faster than the revenue growth.
Why profits lagged the sales surge
As a trader, Lamosaic’s model is inherently low-margin. According to analysis from Newboard, its profit rests on volume and collecting money from dealers. This quarter, the cost of driving that volume ate deeply into earnings.
A significant jump in other income, which rose over 700% year-on-year to ₹0.56 crore, provided a crucial buffer. Without it, the profit growth would have been even more modest. The company also benefited from lower tax and interest costs compared to last year.
The persistent working capital challenge
Cash flow remains a structural concern. Research from Investing.com India shows operating cash flow was deeply negative in FY26 at -₹157.13 crore. Money is tied up with dealers, as evidenced by high receivable days.
The board is looking beyond its core trade, with a June 2026 notice adding textiles to its main objects, as noted by Newboard. This suggests a search for new avenues amid the cash-intensive, low-margin nature of its current business.
Key Points
- Revenue rebounded sharply by 83% year-on-year, but net profit growth was limited to 17.5%.
- A 310-basis-point contraction in net profit margin shows costs rose faster than sales.
- The company remains heavily reliant on dealer-driven volume, with cash flow constrained by working capital.
- Other income provided essential support to the bottom line this quarter.
Hexa Perspective
The quarter reveals a trader caught between recovery and compression. The impressive revenue jump is a corrective bounce from a very weak base in Q2 FY26, not necessarily a sign of sustained momentum.
The margin pressure is the more telling metric. With expenses growing nearly as fast as sales on a trailing basis, the business model's thin returns are laid bare. The shift toward textiles in the corporate objects clause hints at management's own search for a more durable path.
For the earnings trajectory to improve, Lamosaic needs either much better cost control or a fundamental change in its trade-heavy model. The current run-rate leaves little room for error.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.