CJ Gelatine (CJGEL) Q2 FY27 Profit Hits Zero as Sales Slide 19%
The gelatin maker's revenue fell sharply year-on-year and sequentially, erasing its meager profitability despite a one-off gain.
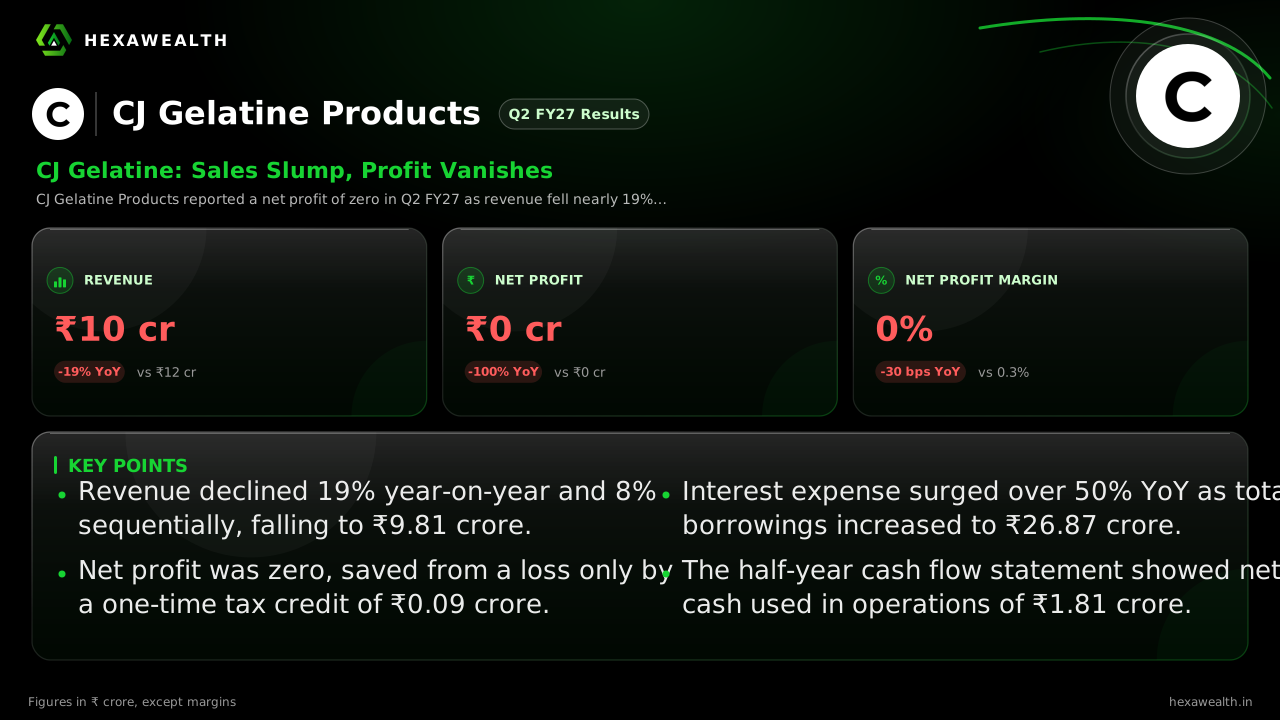
CJ Gelatine Products reported a net profit of zero in Q2 FY27 as revenue fell nearly 19% from a year ago. A sharp drop in sales overwhelmed a one-time tax credit, highlighting persistent operational pressure.
For CJ Gelatine, the September quarter was a step back. After a profitable June period, the company's top line contracted sharply, pushing its bottom line to zero and raising questions about its ability to sustain growth in a competitive market.
The numbers tell a clear story of retreat. Revenue fell 19% year-on-year to ₹9.81 crore and slipped 8% from the previous quarter. This decline erased the company's already thin profitability, resulting in a net profit of ₹0.0 crore. A one-time exceptional gain of ₹0.09 crore, related to a tax credit, was the only factor that prevented a reported loss.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ1 FY27 (Jun 2026) |
|---|---|---|
| Revenue (₹ Cr) | 9.81 | 10.65 |
| Profit (₹ Cr) | 0.00 | 0.14 |
| Net Profit Margin | 0.0% | 1.3% |
The Cost That Won't Budge
While material costs fell, a surging finance charge ate into margins. Interest expense jumped over 50% from a year ago to ₹0.53 crore, according to the company's filing. This reflects a heavier debt burden, as total borrowings rose to ₹26.87 crore by September end from ₹23.64 crore in March, a report from Multibagg.ai noted. The company is funding its operations through borrowings while generating negative cash flow from operations.
A Sector in Slow Motion
The broader market offers little near-term relief. While a report from IndexBox suggests India's food-grade gelatin demand could grow 4-6% annually, the current environment is challenging. A peer, India Gelatine & Chemicals, recently reported flat quarterly revenue despite record margins, signaling a period of industry consolidation rather than rapid expansion.
With revenue at a five-quarter low and debt costs climbing, the path to sustained profitability is narrow. The company's trailing-twelve-month net profit margin is just 1.0%, leaving minimal buffer against further sales volatility.
Key Points
- Revenue declined 19% year-on-year and 8% sequentially, falling to ₹9.81 crore.
- Net profit was zero, saved from a loss only by a one-time tax credit of ₹0.09 crore.
- Interest expense surged over 50% YoY as total borrowings increased to ₹26.87 crore.
- The half-year cash flow statement showed net cash used in operations of ₹1.81 crore.
Hexa Perspective
The quarter underscores a fragile financial position. Sales are moving in the wrong direction while debt and its associated costs are rising, creating a profitability squeeze. The one-off gain masks an operating loss, making the underlying trend more concerning.
For the stock, which trades at a 33% discount to the industry PE, the discount reflects these fundamental pressures. Investors are weighing the stable, long-term demand for gelatin against the company's immediate struggle to grow sales and manage its balance sheet. Until revenue finds a floor and debt stabilizes, earnings momentum will remain elusive.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.