All posts

Follow Us

LinkedInInstagramX
Quarterly ResultsArchiveLast updated 14 November 20263 min read

Ahluwalia Contracts (AHLUCONT) Q2 FY27 Profit Drops 29% Despite Strong Revenue Growth

The construction firm's revenue climbed 24% year-on-year, but a surge in material costs and depreciation led to a sharp profit decline.

By Vinayak Gandhi, CFA · Created 14 November 2026

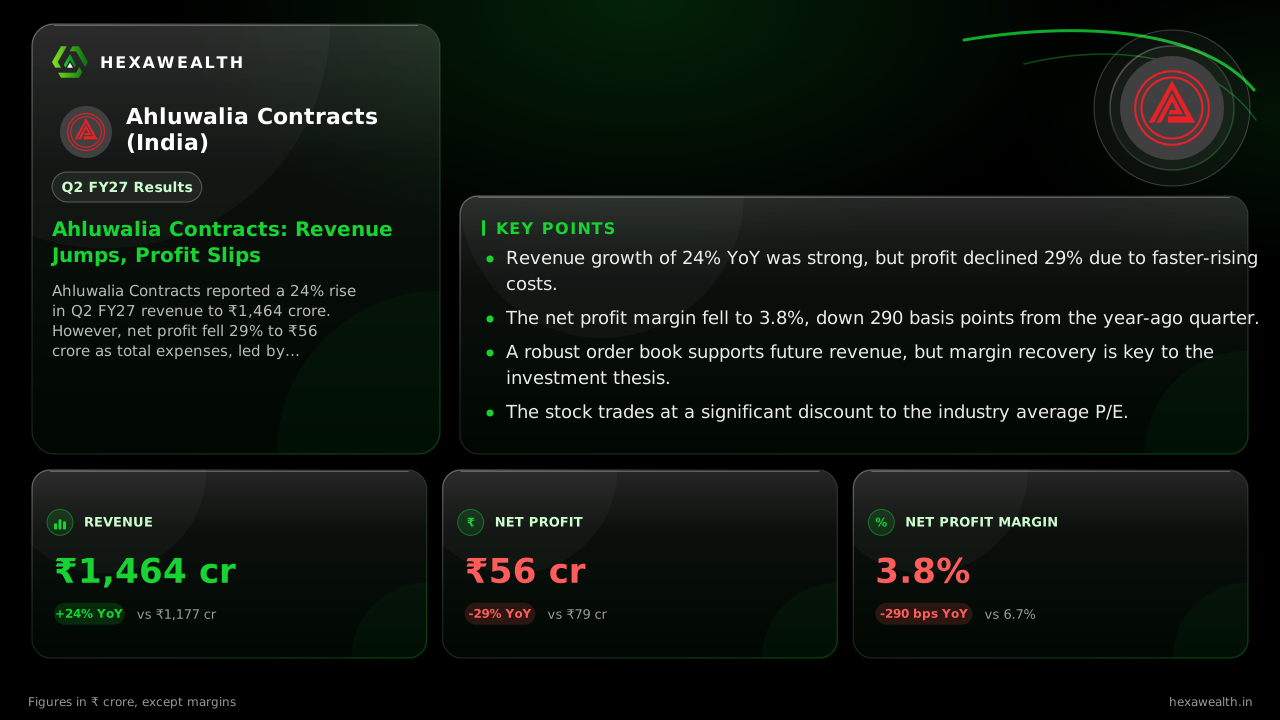
Ahluwalia Contracts reported a 24% rise in Q2 FY27 revenue to ₹1,464 crore. However, net profit fell 29% to ₹56 crore as total expenses, led by material costs, grew faster than sales.

For Ahluwalia Contracts, a strong order book is translating into higher revenue, but the path to profit is getting rougher. The September quarter saw a sharp divergence as sales grew robustly but earnings fell, highlighting a margin squeeze that has become the central story.

The numbers show the split. Revenue rose 24% year-on-year to ₹1,464 crore, a solid 30% jump from the weak June quarter. Profit, however, fell 29% from a year ago to ₹56 crore, though it rebounded sharply from a low base last quarter. The net profit margin compressed to 3.8%, down 290 basis points from the 6.7% seen in Q2 FY26.

Revenue & profit

Revenue (₹ Cr)

Net Profit (₹ Cr)

Net Profit Margin (%)

MetricCurrentQ2 FY27PreviousQ1 FY27Same quarter LYQ2 FY26
Revenue (₹ Cr)
1,463.66YoY +24%
1,125.81
1,177.30
Net Profit (₹ Cr)
56.09YoY -29%
10.39
78.57
Net Profit Margin (%)
3.8YoY -43%
0.9
6.7

Why the top line didn't reach the bottom

Costs rose faster than revenue, eroding profitability. Total expenses grew 29% year-on-year, outpacing the 24% sales growth. A key driver was a 46% surge in the cost of materials to ₹688 crore, as reported by MarketsMojo. Higher depreciation, up 56% year-on-year, also weighed on profits.

Management had flagged a shift to selective, higher-margin bidding after a difficult first quarter. The Q2 EBITDA margin of about 7.6%, reported by Perivis, shows some recovery from Q1's 4.3% low but remains well below historical levels. The company has ruled out double-digit EBITDA margins for the full year, according to StockWatch.

The runway ahead

A record order book of about ₹21,100 crore, as noted by Anand Rathi Research, provides strong revenue visibility. Recent wins like a ₹310 crore order from Bennett University add to the pipeline. However, the market is focused on margin recovery.

Analyst consensus remains positive, with 10 of 11 brokers rating it a Buy, StockWatch reports. The median price target implies significant upside, but the debate centres on the timing of a sustained margin rebound. The stock closed at ₹528 on results day, having fallen over 40% in the past year.

Key Points

  • Revenue growth of 24% YoY was strong, but profit declined 29% due to faster-rising costs.
  • The net profit margin fell to 3.8%, down 290 basis points from the year-ago quarter.
  • A robust order book supports future revenue, but margin recovery is key to the investment thesis.
  • The stock trades at a significant discount to the industry average P/E.

Hexa Perspective

The quarter confirms that Ahluwalia Contracts' growth engine is running, but profitability is under strain. The margin compression is not a one-off; it reflects persistent input cost inflation and project-specific pressures like the AIIMS Jammu bill reduction.

The path forward hinges on execution. If the company's selective bidding strategy and hoped-for labour cost normalisation in the second half materialise, margins could stabilise. If not, the valuation discount may persist despite the strong order book. Investors are betting on a cyclical recovery, but patience is required.

Share or follow HexaWealth

Also read

Want this applied to your portfolio?

Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.
Ahluwalia Contracts (India) (AHLUCONT) Q2 FY27 results, revenue and profits.

Frequently asked questions

What were Ahluwalia Contracts' Q2 FY27 results?
Ahluwalia Contracts reported Q2 FY27 revenue of ₹1,463.66 crore, a 24.3% increase year-on-year. Net profit for the quarter was ₹56.09 crore, which was 28.6% lower than the ₹78.57 crore profit reported in the same quarter last year.
Why did Ahluwalia Contracts' Q2 FY27 revenue grow 24% but profit fall 29%?
Ahluwalia Contracts' profit fell despite higher revenue because total expenses grew faster than sales, rising 29% year-on-year. A significant 46% jump in the cost of materials to ₹688 crore, as reported by MarketsMojo, and a 56% increase in depreciation were the main factors squeezing margins.
What was Ahluwalia Contracts' net profit margin in Q2 FY27?
Ahluwalia Contracts' net profit margin was 3.8% in Q2 FY27. This represents a decline of 290 basis points from the 6.7% margin achieved in the same quarter of the previous fiscal year (Q2 FY26).
What is Ahluwalia Contracts' order book status as of Q2 FY27?
Ahluwalia Contracts has a robust order book supporting future growth. Anand Rathi Research cited a record backlog of about ₹21,100 crore, which is equivalent to 4.6 times its trailing-twelve-month revenue, providing strong visibility for execution in the coming periods.
What was management's guidance on margins after Q2 FY27 results?
Management has previously ruled out double-digit EBITDA margins for FY27, as noted by StockWatch. The Q2 EBITDA margin was approximately 7.6%, per Perivis, showing some recovery from the Q1 low but indicating that significant margin expansion is not expected in the near term.
Did Ahluwalia Contracts win any major new projects in Q2 FY27?
Yes, Ahluwalia Contracts secured a significant ₹310 crore construction order from Bennett University for six institutional buildings in Greater Noida during the quarter, as reported by Alfafinder. Execution for this project is scheduled over 22 months.
How did Ahluwalia Contracts' stock price react to the Q2 FY27 results?
The stock closed at ₹528.00 on the results date, November 13, 2026. MarketsMojo reported the market was closed at the time of the alert. The stock has declined over 40% in the past year, reflecting investor concerns over margin pressures.
What caused the 56% year-on-year increase in depreciation for Ahluwalia Contracts in Q2 FY27?
Depreciation expense rose 56% year-on-year to ₹34.83 crore in Q2 FY27. This significant increase is typically associated with capital expenditure on new equipment and assets to support the company's expanding project execution and order book.
Did Ahluwalia Contracts' Q2 FY27 results beat analyst estimates?
Pre-result expectations, as outlined by StockWatch, were for revenue of ₹1,150+ crore and profit of ₹40-50 crore. The actual revenue of ₹1,464 crore significantly exceeded this range, while the profit of ₹56 crore was at the higher end of the estimated band.
What is Ahluwalia Contracts' valuation after Q2 FY27 results?
Ahluwalia Contracts trades at a trailing P/E of 16.4, which is a 51.7% discount to the industry average P/E of 34.0. This discount reflects the market's pricing of the near-term margin pressures and profitability challenges the company is facing.
Ahluwalia Contracts Q2 FY27 results August 2026
Ahluwalia Contracts announced its Q2 FY27 (September 2026 quarter) results on November 14, 2026. The company reported revenue of ₹1,463.66 crore and a net profit of ₹56.09 crore for the quarter ended September 30, 2026.
Why did Ahluwalia Contracts profits plunge despite higher sales in the recent quarter?
Ahluwalia Contracts' profit fell 29% in Q2 FY27 despite a 24% sales increase because costs rose even faster. Material costs jumped 46% year-on-year, and depreciation increased by 56%, compressing the net profit margin from 6.7% to 3.8%.