Purv Flexipack (PURVFLEXI) Profit Slips 17% as Revenue Declines 16% in Q2 FY27
The distributor's top-line shrank year-on-year for the first time in recent quarters, while a sharp drop in other income further pressured profitability.
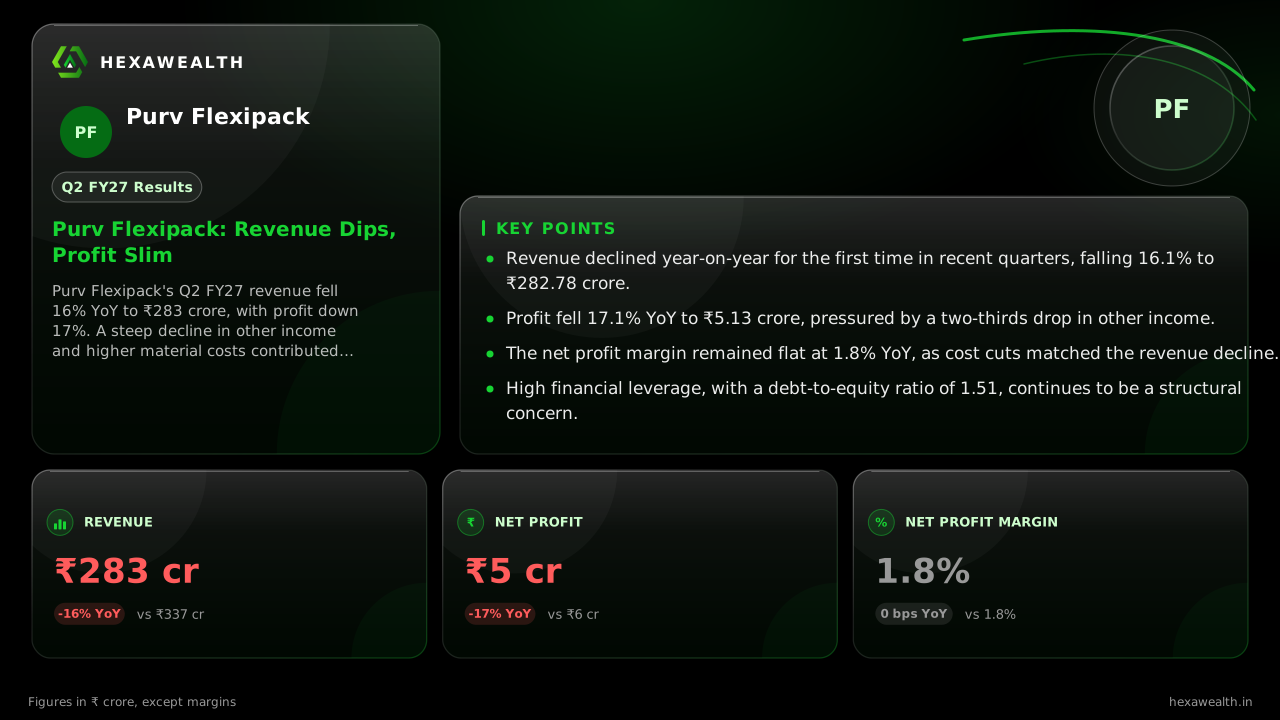
Purv Flexipack's Q2 FY27 revenue fell 16% YoY to ₹283 crore, with profit down 17%. A steep decline in other income and higher material costs contributed to the squeeze, despite a slight margin improvement from the previous quarter's loss.
For a distributor like Purv Flexipack, the story is written in the volume of goods it moves. The September quarter saw that volume contract, marking a departure from the growth trajectory of recent periods.
Revenue for Q2 FY27 was ₹282.78 crore, down 16.1% from a year ago and 12.6% sequentially. Net profit fell 17.1% year-on-year to ₹5.13 crore, though this represented a recovery from the ₹2.78 crore loss in the March quarter. The net profit margin held steady at 1.8% compared to Q2 FY26.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ4 FY26 (Mar 2026) |
|---|---|---|
| Revenue (₹ Cr) | 282.78 | 323.39 |
| Profit (₹ Cr) | 5.13 | -2.78 |
| Net Profit Margin | 1.8% | -0.9% |
The Squeeze from Both Sides
The decline was driven by a sharp 66.6% year-on-year drop in other income, which fell to ₹6.34 crore. Reports from marketping.in and HV Investing on a related entity, Purity Flexpack, show a similar trend where other income turned negative, suggesting this was a significant headwind.
At the same time, the cost environment remained challenging. While total expenses fell 18.3% YoY in line with lower sales, the cost of materials as a proportion likely stayed high. Industry reports point to firm input prices; BOPP film prices in India rose about 4% in Q3 2026, according to Expert Market Research.
A High-Wire Act with Debt
The company's high debt load adds a persistent cost. The debt-to-equity ratio stands at 1.51, meaning borrowings significantly exceed shareholder equity. Interest expense, while down 5.9% YoY, still consumed ₹8.19 crore this quarter.
This leverage amplifies the impact of any operational slippage. Data from newboard.in shows borrowings have grown steadily, reaching ₹209 crore at the end of FY26. Managing this balance sheet will be crucial for sustaining profitability at thin margins.
Key Points
- Revenue declined year-on-year for the first time in recent quarters, falling 16.1% to ₹282.78 crore.
- Profit fell 17.1% YoY to ₹5.13 crore, pressured by a two-thirds drop in other income.
- The net profit margin remained flat at 1.8% YoY, as cost cuts matched the revenue decline.
- High financial leverage, with a debt-to-equity ratio of 1.51, continues to be a structural concern.
Hexa Perspective
The quarter reveals a distributor caught between softer demand and stubborn costs. The flat margin suggests Purv Flexipack managed to keep its operating squeeze in check, but the path forward is narrow.
Recovery hinges on a rebound in shipment volumes to utilize its distribution network. However, with industry capacity ample and global freight costs elevated, pricing power may remain limited. Investors are weighing whether this is a cyclical dip or a sign of deeper competitive pressures in its core film distribution business.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.