Atal Realtech (ATALREAL) Q2 FY27 Profit Jumps 50% as Revenue Doubles Sequentially
The civil contractor's revenue surged 115% from the previous quarter, but a sharp sequential margin drop highlights the cost pressures of scaling up.
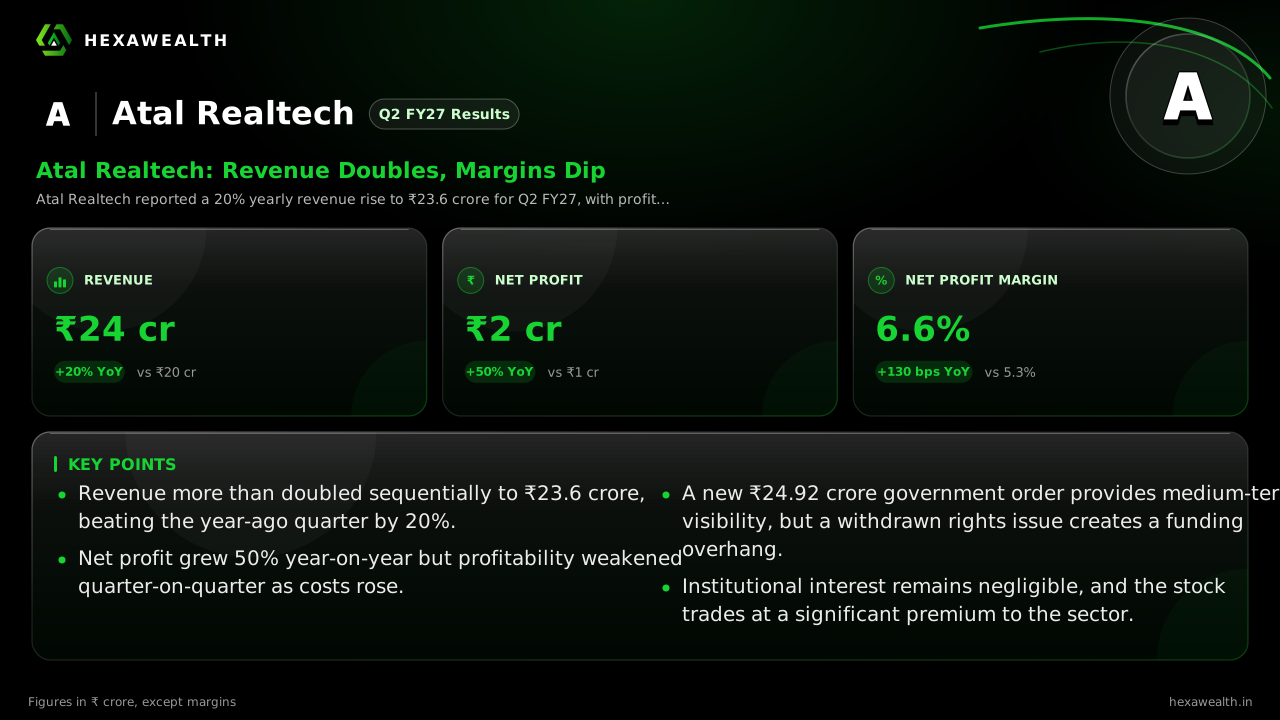
Atal Realtech reported a 20% yearly revenue rise to ₹23.6 crore for Q2 FY27, with profit up 50%. However, net profit margin fell 250 basis points sequentially as costs rose faster than sales.
For a small civil contractor like Atal Realtech, the quarter's success is measured by its ability to convert a growing order book into timely revenue. The September quarter delivered that, with revenue more than doubling from a low monsoon-impacted base.
Revenue jumped 20% year-on-year to ₹23.6 crore, while net profit rose 50% to ₹1.56 crore. The sequential story is more dramatic: revenue surged 115% from the previous quarter's ₹11 crore. Profit followed, rising 56%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ1 FY27 (Jun 2026) |
|---|---|---|
| Revenue (₹ Cr) | 23.61 | 10.97 |
| Profit (₹ Cr) | 1.56 | 1.00 |
| Net Profit Margin | 6.6% | 9.1% |
Why the margin slipped as revenue soared
Despite the strong top-line growth, net profit margin contracted 250 basis points sequentially to 6.6%. This squeeze came as total expenses rose 119%, slightly outpacing revenue growth. Employee costs and interest expenses climbed 35% and 23% year-on-year, respectively, as reported by the company.
This reflects the inherent cost of ramping up execution. The quarter also saw a ₹0.15 crore swing in other income to a small loss, removing a tailwind from the prior quarter.
A new order, but a funding gap
The revenue momentum was likely driven by progress on existing projects and the start of a major new one. In July, the company secured a formal ₹24.92 crore work order from the Maharashtra PWD, as reported by Alfafinder. This project will provide revenue visibility over the next 18 months.
However, a key constraint emerged. The company withdrew a proposed ₹16 crore rights issue in October, citing unfavourable market conditions, according to StockFin.ai. Analysts at mCapital.in estimate this could cut executable work by ₹6-10 crore over the next year, forcing a reliance on incremental debt to fund its negative operating cash flow.
The market's cautious read
Foreign institutional investor (FII) holdings have dwindled from 6.2% to just 0.5% over the past year, notes StockFin.ai, signaling weak institutional confidence. The stock trades at a P/E of 39.9, a 68% premium to its industry, despite a 42% decline over the past year. This valuation gap underscores the market's skepticism about sustainable, high-quality earnings growth.
Key Points
- Revenue more than doubled sequentially to ₹23.6 crore, beating the year-ago quarter by 20%.
- Net profit grew 50% year-on-year but profitability weakened quarter-on-quarter as costs rose.
- A new ₹24.92 crore government order provides medium-term visibility, but a withdrawn rights issue creates a funding overhang.
- Institutional interest remains negligible, and the stock trades at a significant premium to the sector.
Hexa Perspective
The quarter shows Atal Realtech can deliver growth when projects move into the execution phase. The year-on-year margin expansion is a positive sign of operating improvement.
Yet the sequential margin compression and the withdrawn fundraise point to a fragile financial structure. Growth is currently funded by a tightening working capital cycle, not sustainable equity. For the momentum to hold, the company must demonstrate it can win and execute projects without straining its balance sheet, a test the next few quarters will define.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.