Sumeet Industries (SUMEETINDS) Q2 FY27 Revenue Jumps 35% as Profit Falls 43%
The polyester manufacturer's sales hit a record high, but profitability was squeezed by soaring input costs, with a large part of the profit coming from other income.
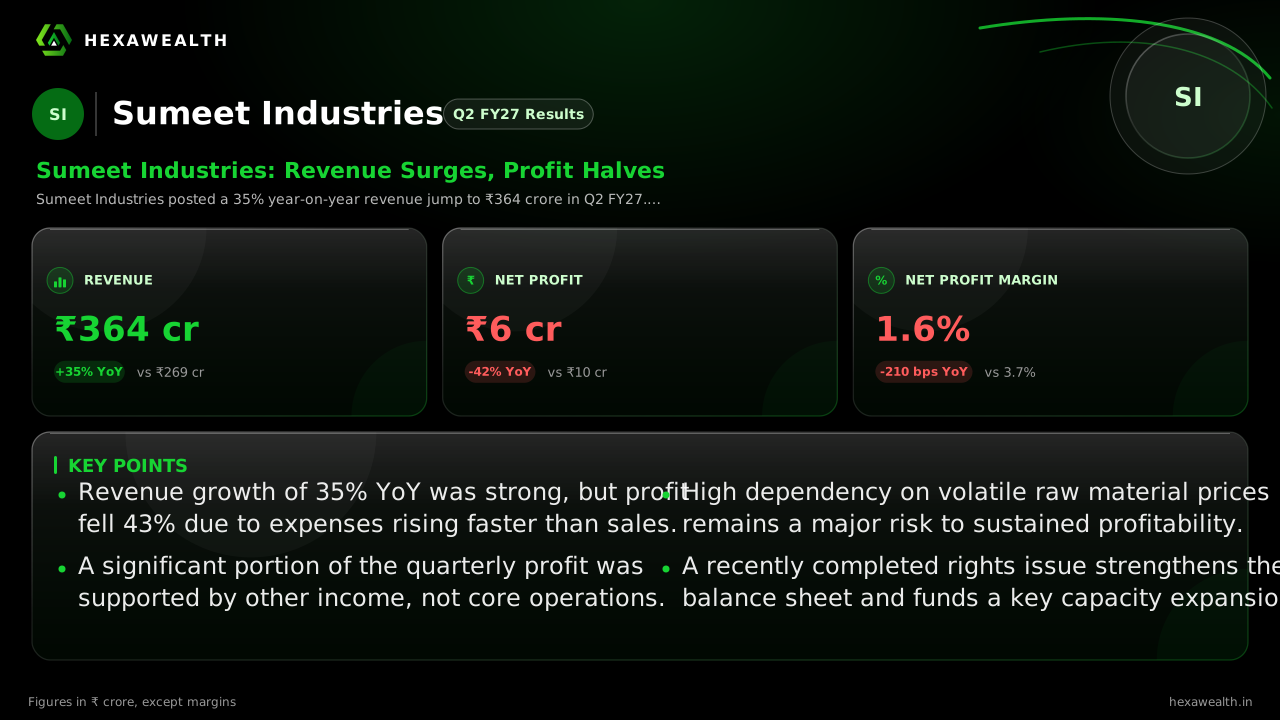
Sumeet Industries posted a 35% year-on-year revenue jump to ₹364 crore in Q2 FY27. However, net profit fell 43% to ₹5.67 crore as total expenses grew faster than sales, compressing margins significantly.
For Sumeet Industries, a polyester yarn and chips maker, the September quarter was a story of two diverging lines. Revenue soared to a record high, yet profitability was squeezed by costs that rose even faster, leaving the bottom line far weaker than a year ago.
The numbers show a clear split. Revenue jumped 35% year-on-year to ₹364 crore, a sharp sequential recovery from the June quarter. Profit, however, fell 43% to ₹5.67 crore. The net profit margin shrank to 1.6%, down from 3.7% a year earlier.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 364.18YoY +35% | 272.36 | 269.30 |
| Profit (₹ Cr) | 5.67YoY -42% | 1.14 | 9.86 |
| Net Profit Margin (%) | 1.6YoY -57% | 0.4 | 3.7 |
Why the profit fell behind
Total expenses surged 39% year-on-year, outpacing the 35% revenue growth. This points to a severe margin squeeze in the core business. A report from Flash Finance notes that 58% of the quarter's pre-tax profit came from other income and one-off items, not operations.
Core operating profit fell 36.5% year-on-year. The company's other income, however, jumped 73% to ₹2.94 crore, providing a critical buffer. This income, along with a 27% sequential drop in interest costs, helped lift profit from the very low base of the previous quarter.
The cost challenge ahead
Raw material costs, which make up 80-85% of expenses, are the central pressure. According to an analysis by Flash Finance, the company has a severe dependency on suppliers like Reliance Industries for key inputs PTA and MEG. This leaves margins highly vulnerable to crude oil-linked price swings.
Industry reports from September 2026 describe a crisis in Surat's textile cluster, where soaring polyester yarn prices burdened downstream weavers. While some reports suggest raw material prices have started to correct, the company's ability to fully pass on costs remains tested by volatility.
Funding the next phase
Management is betting on a major capacity expansion to drive future growth. The company successfully completed a ₹199.75 crore rights issue in July, as noted by SAHI. Proceeds are allocated to working capital and integrating the newly acquired Nakoda polyester chips plant.
The rights issue also helped cut debt. According to Arthneeti, the company reported a net decrease in borrowings of over ₹213 crore on a consolidated basis for the half-year. This should ease the interest burden, which already fell sequentially in Q2.
Key Points
- Revenue growth of 35% YoY was strong, but profit fell 43% due to expenses rising faster than sales.
- A significant portion of the quarterly profit was supported by other income, not core operations.
- High dependency on volatile raw material prices remains a major risk to sustained profitability.
- A recently completed rights issue strengthens the balance sheet and funds a key capacity expansion.
Hexa Perspective
The quarter reveals the tightrope Sumeet Industries walks. Record sales show demand is not the issue, but razor-thin margins expose its vulnerability as a commodity processor. The promised margin recovery hinges on two unstable factors: sustained calm in raw material prices and flawless execution of the Nakoda plant integration.
The capital raise provides a runway, but the core economics are unchanged. Investors are left weighing aggressive growth targets against a history of margin volatility, with the stock's reaction suggesting cautious acknowledgment of the top-line beat amidst deeper profitability concerns.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.