Subros (SUBROS) Q2 FY27 Profit Growth Lags Behind a 36% Revenue Surge as Costs Bite
The auto parts maker posted its highest-ever quarterly sales but profitability was squeezed by raw material and logistics costs that are not fully passed on.
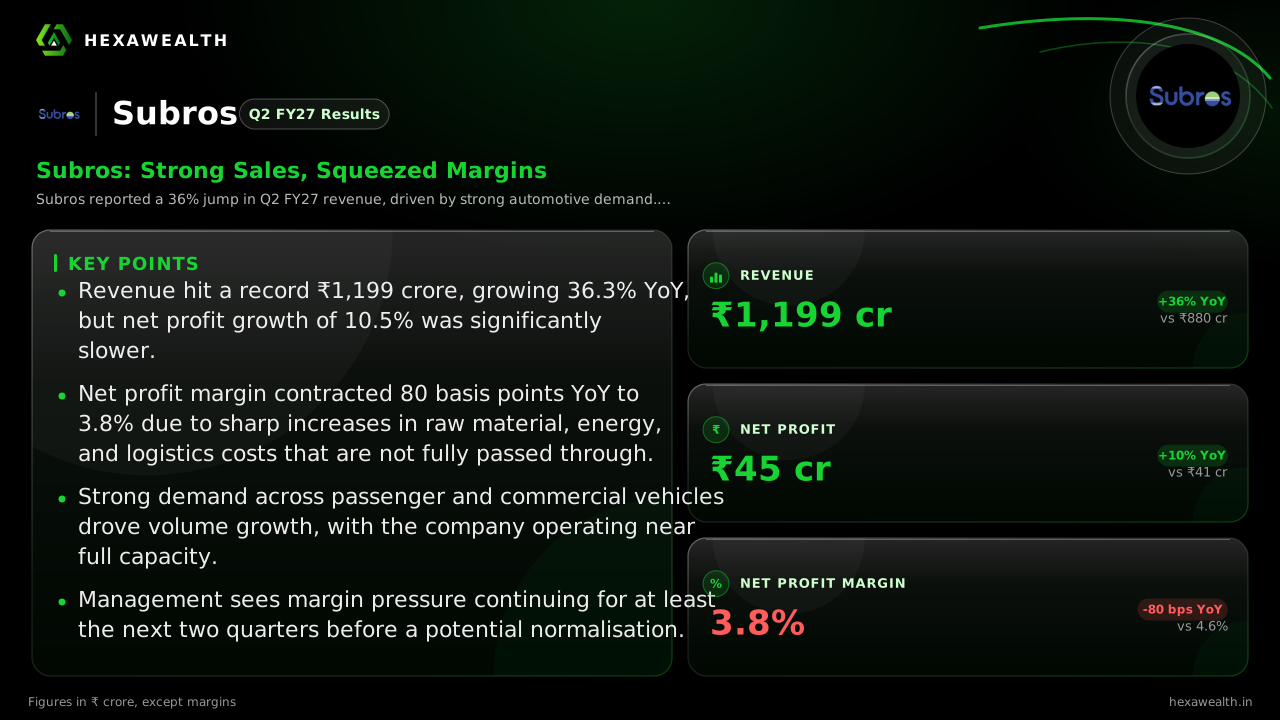
Subros reported a 36% jump in Q2 FY27 revenue, driven by strong automotive demand. However, net profit grew only 10.5% as margins contracted sharply due to elevated input and logistics costs.
For an auto parts supplier, a booming market is a double-edged sword. Subros rode a wave of record vehicle sales to its highest-ever quarterly revenue, but the scramble to meet that demand came at a steep cost to profitability.
Revenue surged 36.3% year-on-year to ₹1,199 crore, while net profit grew a more modest 10.5% to ₹45 crore. The gap tells the story: net profit margin shrank 80 basis points to 3.8%. The quarter-on-quarter picture was similar, with sales up 16.2% but profit margins dipping another 20 basis points.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 1,199.0YoY +36% | 1,032.1 | 879.8 |
| Profit (₹ Cr) | 45.0YoY +11% | 41.5 | 40.7 |
| Net Profit Margin | 3.8%YoY -17% | 4.0% | 4.6% |
The Cost That Outran Pricing
The margin squeeze was no mystery. Management, on the earnings call hosted by AlphaStreet, pointed to a triple whammy of commodity, energy, and logistics costs that have surged 200-300% since February. Prices for key inputs like aluminum, copper, plastic, and steel are at a peak.
Crucially, these costs are not fully reimbursed by automaker customers, and compensation comes with a quarter's lag. The company also had to prioritise supplying original equipment manufacturers over the more lucrative aftermarket segment to keep their lines running, further pressuring the mix.
A Demand-Led Revenue Engine
Despite the cost pain, the revenue engine is firing. Growth was broad-based, led by a 54% jump in commercial vehicle business and a 64% surge in bus air-conditioning, according to the earnings call. The company is operating near full capacity to serve a domestic auto industry that grew 18.2% in the quarter.
Visibility remains strong. Subros recently secured a ₹225 crore, seven-year order from Maruti Suzuki, with start of production slated for FY29. Its new Karkoda plant has begun commercial operations to support this growth.
The Outlook: Patience Required
Management expects the margin pressure to persist. On the call, CEO Pramod Kumar Duggal indicated it may take another two quarters for costs to normalise or for a one-time settlement with customers on extraordinary variations. Until then, EBITDA margins are likely to remain in the high single digits.
The demand outlook for the second half remains encouraging, though growth may moderate against a higher base. To prepare, the company is preponing some capacity expansion investments originally planned for next year.
Key Points
- Revenue hit a record ₹1,199 crore, growing 36.3% YoY, but net profit growth of 10.5% was significantly slower.
- Net profit margin contracted 80 basis points YoY to 3.8% due to sharp increases in raw material, energy, and logistics costs that are not fully passed through.
- Strong demand across passenger and commercial vehicles drove volume growth, with the company operating near full capacity.
- Management sees margin pressure continuing for at least the next two quarters before a potential normalisation.
Hexa Perspective
Subros is caught in a classic cyclical squeeze: top-line growth is robust, but profitability is hostage to input costs and pricing power with large OEMs. The quarter confirms that strong industry volumes alone are not enough to drive earnings leverage when cost pressures are this acute.
The path to margin recovery hinges on two factors: a moderation in commodity prices and the company's ability to negotiate better pass-through terms. With management guiding for a two-quarter wait, investors are effectively betting on a second-half FY27 earnings inflection, provided the demand momentum holds.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.