All posts

Follow Us

LinkedInInstagramX
Quarterly ResultsArchiveLast updated 4 November 20262 min read

Savita Oil (SOTL) Q2 FY27 Profit Drops 26% Despite Surging Revenue

Revenue jumped 59% year-on-year, but profit fell sequentially as material costs and lower other income squeezed margins.

By Abhinav Swaroop, CFA, Chief Business Officer: Hexawealth · Created 4 November 2026

Savita Oil Technologies posted a 59% YoY revenue surge in Q2 FY27, yet profit fell 26% from the previous quarter. The drop highlights margin pressure from rising input costs and a sharp decline in other income.

For Savita Oil Technologies, the September quarter was a story of two very different comparisons. The specialty chemicals maker saw its core petroleum products business roar ahead, but the bottom line told a more complicated tale.

Revenue reached ₹1,709 crore, a 59% leap from last year and a 15.5% gain from the June quarter. Profit, however, fell 26% sequentially to ₹212 crore, even as it soared over 400% year-on-year. The net profit margin compressed sharply to 12.4% from 19.5% in Q1.

Revenue & profit

Revenue (₹ Cr)

Profit (₹ Cr)

Net Profit Margin (%)

MetricCurrentQ2 FY27 (Sep 2026)PreviousQ1 FY27 (Jun 2026)
Revenue (₹ Cr)
1,709.0
1,479.8
Profit (₹ Cr)
212.0
288.1
Net Profit Margin (%)
12.4
19.5

The cost surge behind the margin squeeze

Nearly all the revenue growth came from the petroleum products segment, according to a Multibagg.ai report. But material costs rose in lockstep with sales, up 56% year-on-year to ₹1,320 crore. Total expenses jumped 27% from the prior quarter.

This cost pressure, combined with a steep drop in other income, explains the profit dip. Other income collapsed 85% sequentially to just ₹5 crore, as reported by ScanX.trade. The prior quarter’s profit was flattered by this one-off boost.

A supportive but volatile backdrop

Management’s outlook, noted in a StockFin.ai analysis, remains focused on high-growth sectors like data centers and electric vehicles. The company’s official presentation expects EBITDA margins to stay in a 17-20% range.

The broader refining environment is supportive. The Economic Times reports Indian refiners expect healthy margins due to global supply disruptions. This tight market aids pricing for Savita Oil’s specialty products.

Key Points

  • Revenue growth remained robust, driven entirely by the core petroleum products segment./n- Sequential profit decline was driven by a sharp rise in material costs and an 85% drop in other income.
  • Management is targeting high-margin specialty segments and expects core EBITDA margins to remain elevated.

Hexa Perspective

The quarter confirms strong underlying demand but also exposes vulnerability to input costs. The core business is healthy, with margins still far above last year's levels.

The path ahead hinges on whether product pricing can outpace raw material inflation. With the company debt-free and trading at a discount to the industry PE, the market seems to be weighing this cost-pressure risk against a solid growth runway.

Share or follow HexaWealth

Also read

Want this applied to your portfolio?

Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.
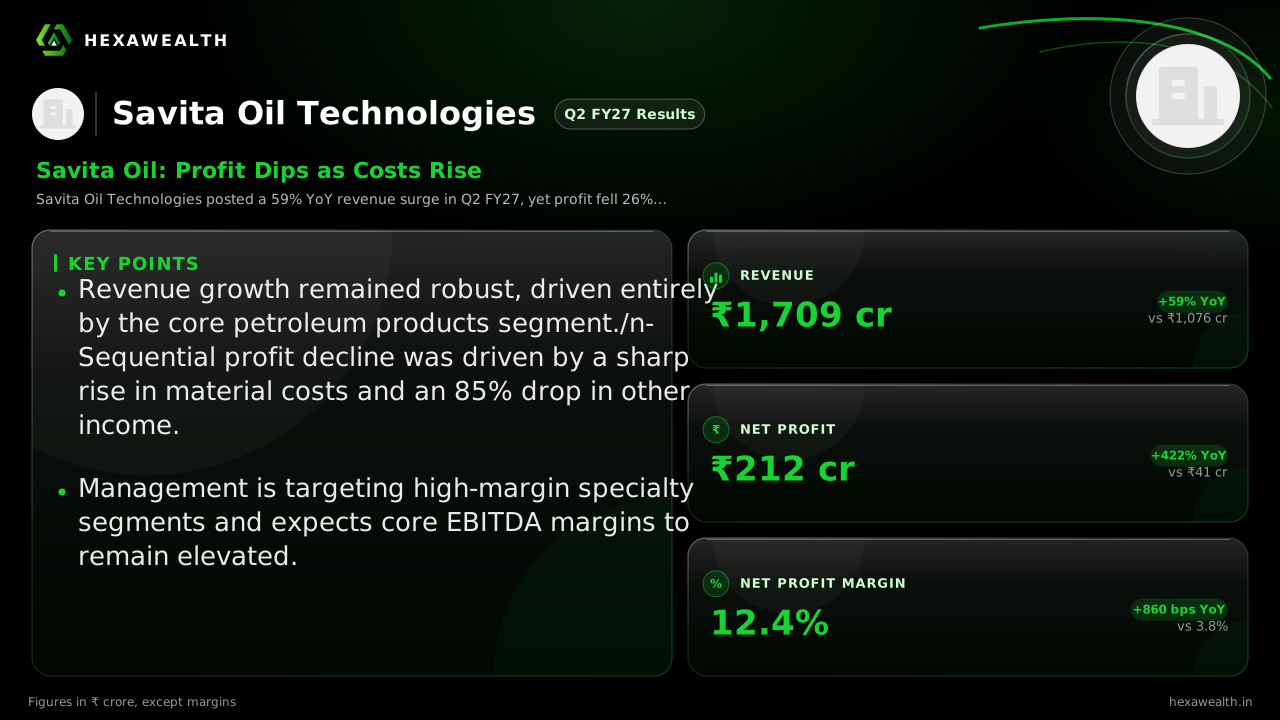
Savita Oil Technologies (SOTL) Q2 FY27 results, revenue and profits.

Frequently asked questions

What were Savita Oil Technologies' Q2 FY27 results?
For Q2 FY27 (September 2026), Savita Oil Technologies reported revenue of ₹1,709 crore and a net profit of ₹212 crore. This represents a 59% year-on-year revenue increase, though profit fell 26% compared to the previous quarter (Q1 FY27).
Why did Savita Oil Technologies' Q2 profit fall despite higher sales?
Savita Oil's Q2 FY27 profit fell 26% sequentially because of rising material costs and a sharp drop in other income. Total expenses rose 27% from the prior quarter, while other income collapsed by 85%, as reported by ScanX.trade, squeezing the net profit margin.
What was Savita Oil Technologies' net profit margin in Q2 FY27?
Savita Oil Technologies' net profit margin was 12.4% in Q2 FY27 (September 2026). This marks a significant year-on-year improvement but a 7.1 percentage point decline from the 19.5% margin achieved in the previous quarter (Q1 FY27).
What drove Savita Oil's 58.8% YoY revenue growth in Q2 FY27?
The 59% year-on-year revenue growth was driven almost entirely by the Petroleum Products segment. A report by Multibagg.ai states segment revenue rose to ₹1,696 crore in Q2 FY27 from ₹1,062 crore a year ago, accounting for nearly all of the company's total revenue.
Why did total expenses increase 27.2% QoQ for Savita Oil?
Total expenses rose 27% quarter-on-quarter primarily due to higher material costs linked to increased sales volumes. The cost of materials consumed was ₹1,320 crore in Q2 FY27, up from ₹848 crore a year earlier, consistent with the higher level of business activity.
What caused the 710 bps QoQ decline in net profit margin?
The 7.1 percentage point sequential decline in net profit margin was caused by two factors: a significant rise in material costs that outpaced revenue growth, and an 85% quarter-on-quarter collapse in other income, which had boosted the previous quarter's profitability.
Why did other income collapse by 84.8% QoQ?
Other income fell sharply to ₹5 crore in Q2 FY27 from ₹33 crore in Q1 FY27. ScanX.trade notes this sequential dip coincided with the profit decline, indicating the prior quarter's earnings were supported by a non-recurring income boost.
What was management's guidance and outlook in the Q2 FY27 concall?
While no formal transcript was published, a StockFin.ai analysis of management commentary highlights a strategic shift towards high-growth sectors like data centers and EVs. The company's official presentation expects EBITDA margins to remain in the 17-20% range going forward.
What is the performance outlook for Savita Oil's transformer oil and lubricants segments?
The Petroleum Products segment, which includes transformer oils and lubricants, remains the primary growth driver. It contributed ₹1,696 crore of the ₹1,709 crore total revenue in Q2 FY27, indicating sustained strong performance and central importance to earnings.
Did Savita Oil Q2 FY27 results beat or miss analyst estimates?
Specific analyst estimates for Q2 are not detailed in available research. However, the reported revenue of ₹1,709 crore and profit of ₹212 crore show massive year-on-year growth but a sequential profit decline, which may have been softer than some expectations.
What are major brokerages saying about Savita Oil after Q2 results?
According to Sharpely.in, analyst consensus for Savita Oil is a 'Buy' with a median target price of ₹950. The report states 100% of covering analysts have a buy or strong buy rating, implying a positive street outlook despite the sequential earnings dip.
Savita Oil Technologies Q2 profit drop
Savita Oil Technologies' Q2 FY27 (Sep 2026) net profit dropped 26% quarter-on-quarter to ₹212 crore. This decline occurred despite a 15.5% rise in revenue, primarily due to higher material costs and a sharp fall in other income compared to the previous quarter.
Savita Oil Technologies September quarter profit
Savita Oil Technologies' profit for the September 2026 quarter (Q2 FY27) was ₹212 crore. This is a 422% increase from the same quarter last year but a 26% decrease from the profit of ₹288 crore reported in the June 2026 quarter.