Shalby (SHALBY) Q2 FY27 Profit Drops 25% Sequentially as Margin Pressure Intensifies
The hospital chain posted a 9.7% revenue gain year-on-year, but higher costs led to a sharp quarterly profit decline and margin squeeze.
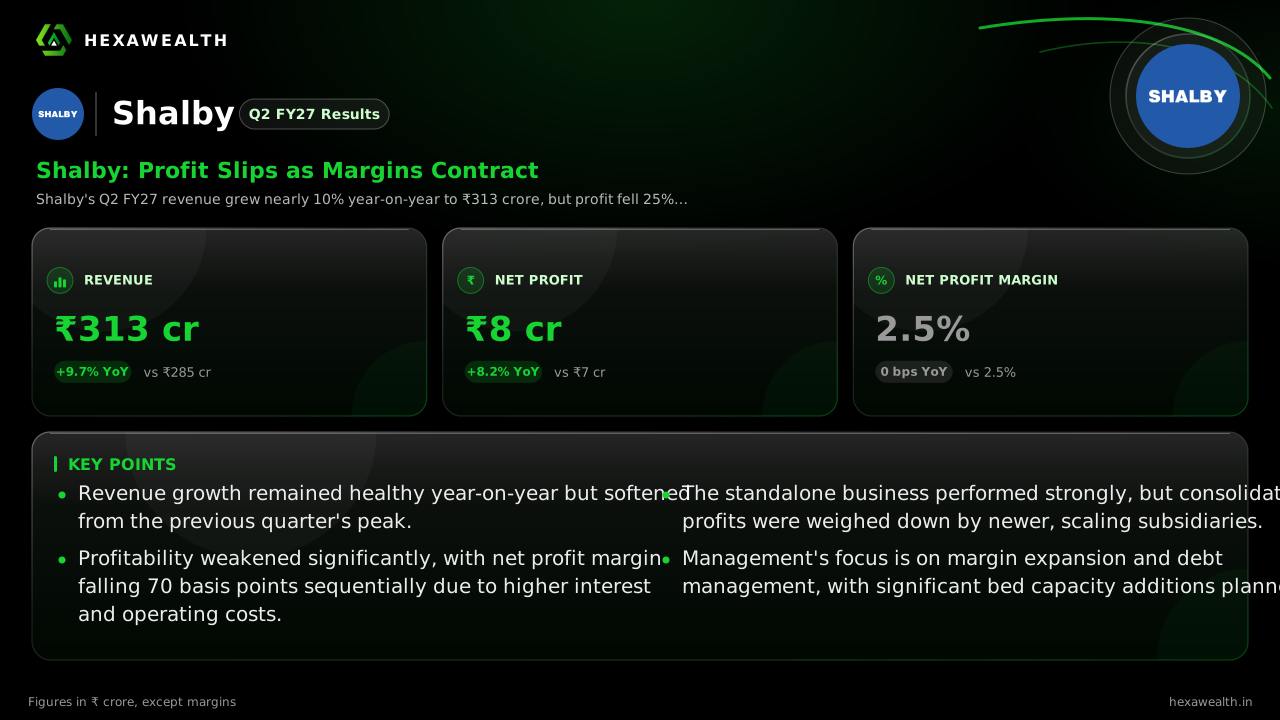
Shalby's Q2 FY27 revenue grew nearly 10% year-on-year to ₹313 crore, but profit fell 25% from the previous quarter. Higher interest and flat operating profit squeezed margins, highlighting the cost pressures facing its expansion.
For Shalby, a quarter defined by steady patient demand has been overshadowed by a sharp profitability squeeze. The hospital chain's revenue grew, but costs rose faster, delivering a sequential profit drop that underscores the operational challenges of its growth phase.
The numbers show a business expanding but not yet efficiently. Revenue for the September quarter stood at ₹313.17 crore, up 9.7% from a year ago but down 5.4% from the strong June quarter. Net profit fell more sharply, dropping 25% sequentially to ₹7.88 crore.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 (Sep '26) | PreviousQ1 FY27 (Jun '26) |
|---|---|---|
| Revenue (₹ Cr) | 313.17 | 331.22 |
| Profit (₹ Cr) | 7.88 | 10.50 |
| Net Profit Margin (%) | 2.5 | 3.2 |
Where the growth went
Revenue growth was broad-based, led by the core hospital business which contributed over 80% of sales, according to Arthneeti's review of the investor presentation. Yet operating profit was nearly flat year-on-year at ₹41.4 crore, as reported by Univest.
This points to costs rising in step with, or ahead of, sales. Interest expense jumped 14.6% year-on-year, reflecting higher debt to fund expansion. While employee costs fell, other operational expenses kept overall spending growth at 11.4%, outpacing revenue.
The margin squeeze ahead
Management has set an ambitious target of reaching a 20% EBITDA margin for FY27, as noted by StockFin.ai. The current quarter's consolidated EBITDA margin, however, contracted to 14.6% from 15.9% a year ago, per Scanx.trade.
This gap highlights the execution challenge. New units like Shalby International and Shalby MedTech are still scaling and diluting group profitability. The planned Mumbai expansion, a 175-bed facility secured on a long-term lease, will add capacity but also near-term commissioning costs.
Key Points
- Revenue growth remained healthy year-on-year but softened from the previous quarter's peak.
- Profitability weakened significantly, with net profit margin falling 70 basis points sequentially due to higher interest and operating costs.
- The standalone business performed strongly, but consolidated profits were weighed down by newer, scaling subsidiaries.
- Management's focus is on margin expansion and debt management, with significant bed capacity additions planned.
Hexa Perspective
The quarter reveals Shalby in a classic expansion trap: revenue is growing, but the capital needed to fuel that growth is biting into profits today. The 14.6% YoY rise in interest cost is a direct result of funding its bed additions and MedTech capacity.
Investors are weighing steady demand against this margin compression. The path to the targeted 20% EBITDA margin hinges on new units reaching profitability and the core hospital business holding pricing power in a competitive market. For now, the cost of growth is the story.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.