Synergy Green (SGIL) Q2 FY27 Profit Dives 315% Despite 56% Revenue Surge
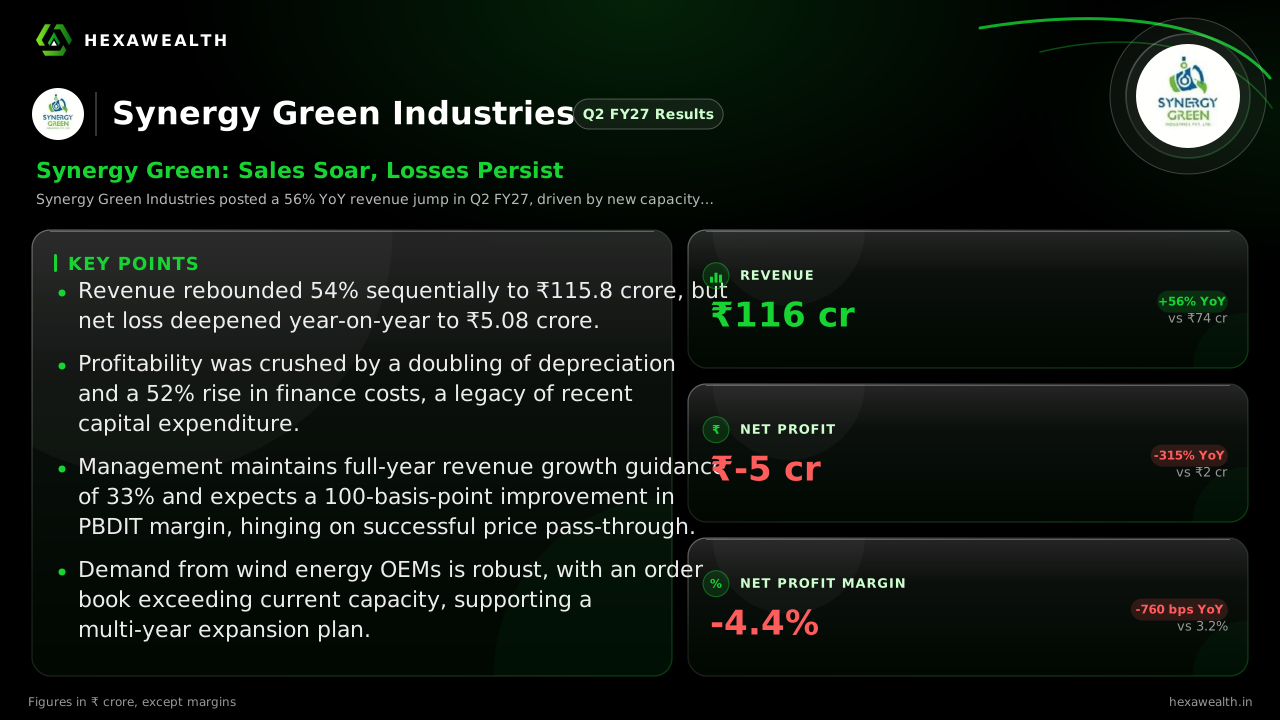
The engineering firm's September quarter revenue jumped to ₹116 crore, but a heavy cost structure pushed it to a ₹5 crore net loss.
Synergy Green Industries posted a 56% YoY revenue jump in Q2 FY27, driven by new capacity and customers. However, steep input costs and high depreciation led to a net loss of ₹5.08 crore, reversing last year's profit.
For a capital-intensive foundry like Synergy Green, the test is whether rising sales can outrun the heavy costs of a recent expansion. The September quarter delivered a surge in revenue but left that question unanswered.
Revenue rose 56% year-on-year to ₹115.8 crore, a sharp sequential recovery from a weak June quarter. Yet the company posted a net loss of ₹5.08 crore, a stark reversal from a ₹2.36 crore profit a year ago. The net loss margin stood at -4.4%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 (Sep '26) | PreviousQ1 FY27 (Jun '26) |
|---|---|---|
| Revenue (₹ Cr) | 115.78 | 75.15 |
| Profit (₹ Cr) | -5.08 | -10.11 |
| Net Profit Margin (%) | -4.4 | -13.5 |
The cost wall that revenue hit
Operating profit, defined as EBITDA excluding other income, grew 21% YoY to ₹11.3 crore, reports AlphaTribe. But costs below that line overwhelmed it. Depreciation more than doubled year-on-year to ₹9.97 crore, reflecting the recent capacity expansion from 30,000 to 45,000 tonnes.
Finance costs also rose 52% to ₹7.15 crore. The company's debt-to-equity ratio stands at a high 2.26, according to the payload. This heavy fixed-cost structure, activated by the expansion, now needs far higher sales to become profitable.
A pricing lag in an inflationary storm
Management, on the earnings call transcribed by AlphaStreet, blamed "steep input cost escalations" for the pressure. While some raw material prices have softened 5-10%, logistics costs have surged, effectively keeping input costs elevated.
The company operates with a mix of annual and quarterly price resets with customers. This creates a lag in passing on cost inflation, which management says impacted margins by 100-150 basis points this quarter. They expect to recover this through upcoming price revisions.
The demand that outruns capacity
The underlying story is one of strong demand. Executive Director V.S. Reddy stated on the call that demand from customers like Nordex and Vestas already exceeds the new 45,000-tonne capacity. The company has a confirmed export order book of over ₹200 crore from Nordex alone.
This demand is driving a bold capacity roadmap. According to a Multibagg.ai report, Synergy Green plans to reach 100,000 tonnes by FY30, more than double its FY26 base. The immediate goal is to ramp up utilization from 75% in the first half to 85% in the second half of FY27.
Key Points
- Revenue rebounded 54% sequentially to ₹115.8 crore, but net loss deepened year-on-year to ₹5.08 crore.
- Profitability was crushed by a doubling of depreciation and a 52% rise in finance costs, a legacy of recent capital expenditure.
- Management maintains full-year revenue growth guidance of 33% and expects a 100-basis-point improvement in PBDIT margin, hinging on successful price pass-through.
- Demand from wind energy OEMs is robust, with an order book exceeding current capacity, supporting a multi-year expansion plan.
Hexa Perspective
The quarter shows Synergy Green caught between a promising top-line recovery and a punishing cost structure that hasn't yet leveraged it. The path to profitability is clear but narrow: it requires the company to successfully pass on high input costs in the next pricing cycle while simultaneously ramping up capacity utilization to absorb high fixed charges.
Investors are essentially funding growth today for profits tomorrow. The stock's premium valuation, with a P/E of 160 against an industry average of 48, prices in a swift execution of this margin recovery and capacity expansion. Any stumble on pricing power or utilization rates would challenge that narrative sharply.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.