Sanghvi Brands (SBRANDS) Q2 FY27 Profit Doubles as Austerity Offsets Softer Sales
The luxury spa operator saw net profit jump 100% year-on-year in Q2 FY27, driven by a sharp reduction in total expenses despite a 6.4% dip in revenue.
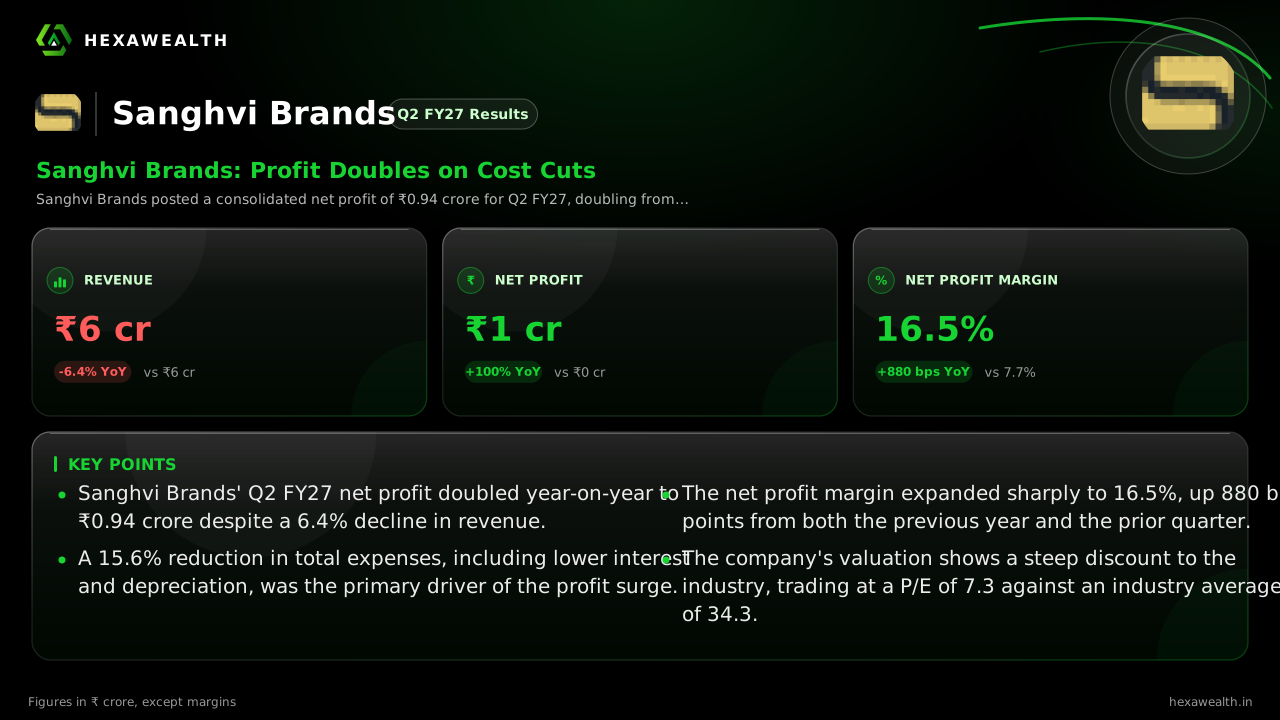
Sanghvi Brands posted a consolidated net profit of ₹0.94 crore for Q2 FY27, doubling from the year-ago quarter. This sharp rise came even as revenue declined to ₹5.69 crore, highlighting a significant improvement in cost management and profitability.
For a luxury services operator, the quarter is often a balance between footfall and premium pricing. Sanghvi Brands' September quarter saw that balance tilt decisively toward profitability, as disciplined spending turned a softer top line into a sharply improved bottom line.
The numbers tell a story of efficiency. Consolidated revenue dipped 6.4% year-on-year to ₹5.69 crore. Yet, net profit doubled to ₹0.94 crore, pushing the net profit margin to 16.5% from 7.7% a year ago. This was a sequential improvement too, with profit also doubling from ₹0.47 crore in Q4 FY26.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|
| Revenue (₹ Cr) | 5.69YoY -6.4% | 6.08 |
| Profit (₹ Cr) | 0.94YoY +100% | 0.47 |
| Net Profit Margin (%) | 16.5YoY +114% | 7.7 |
The Engine Behind the Profit Jump
The profit surge was powered by a sharp 15.6% reduction in total expenses, which fell to ₹4.76 crore. Interest and depreciation costs were each halved compared to the previous year, according to the company's financials. This austerity drive more than offset the revenue decline and a 73% rise in other income, which stood at ₹0.19 crore.
Management commentary from news.tulsian.ai noted the company's focus on operational discipline. While specific segment performance for its spas, salons, and gyms was not detailed in the filings, the consolidated cost control points to tighter management across operations.
A Valuation Gap and the Road Ahead
The company trades at a price-to-earnings ratio of 7.3, a significant discount to the industry average of 34.3, as per the latest valuation data. This gap reflects the market's view of its scale and growth trajectory. With an order book reported at ₹1,582 crore as of late October by news.tulsian.ai, management expressed confidence in demand visibility.
The key will be sustaining this new level of profitability. The margin expansion this quarter is a positive step, but it stemmed largely from cost reduction rather than revenue growth. For the momentum to hold, the company must demonstrate it can grow its top line without letting expenses creep back up.
Key Points
- Sanghvi Brands' Q2 FY27 net profit doubled year-on-year to ₹0.94 crore despite a 6.4% decline in revenue.
- A 15.6% reduction in total expenses, including lower interest and depreciation, was the primary driver of the profit surge.
- The net profit margin expanded sharply to 16.5%, up 880 basis points from both the previous year and the prior quarter.
- The company's valuation shows a steep discount to the industry, trading at a P/E of 7.3 against an industry average of 34.3.
Hexa Perspective
This quarter showcases Sanghvi Brands' ability to protect its bottom line in a softer revenue environment. The dramatic margin improvement is commendable but raises a question about its source: is this a new, sustainable operating efficiency, or a one-time pruning of costs? The company's guidance, cited by stockwatch.live, targets ₹1,400-1,500 crore in consolidated revenue for FY27. Hitting that target will require a significant revenue acceleration in the second half. Investors are now weighing whether the demonstrated cost discipline can be maintained alongside that necessary growth, or if one will come at the expense of the other.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.