Kalyani Investment (KICL) Q2 FY27 Profit Jumps 78% as Dividend Income Rebounds
The core investment company saw its net profit surge to ₹33.72 crore in Q2 FY27, driven by a seasonal rebound in dividend receipts from group firms.
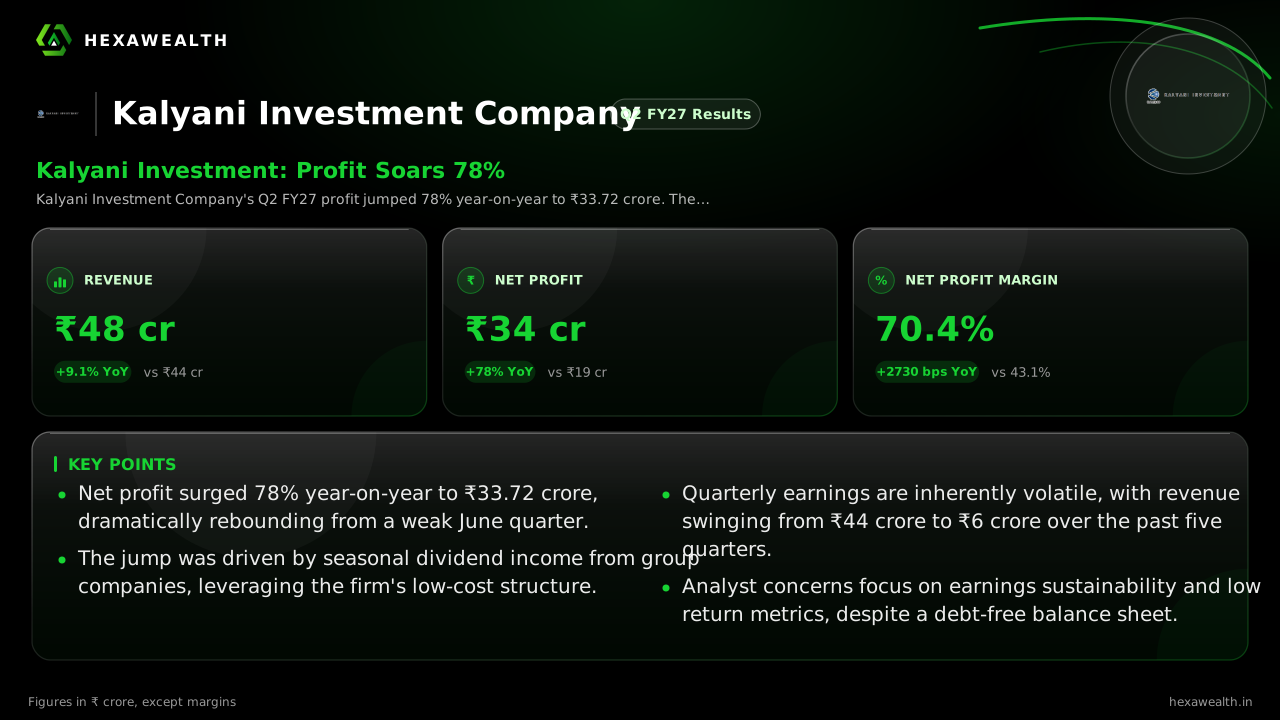
Kalyani Investment Company's Q2 FY27 profit jumped 78% year-on-year to ₹33.72 crore. The surge was powered by a rebound in dividend income, pushing the net profit margin to an exceptional 70.4%.
For a holding company like Kalyani Investment, earnings are a story of timing. Its income flows from dividends and investment valuations across the Kalyani Group, making quarterly results inherently volatile rather than a steady growth line. The September quarter delivered a powerful seasonal rebound, with net profit surging 78% year-on-year to ₹33.72 crore.
The numbers show a company catching the dividend wave. Revenue grew a modest 9% to ₹47.91 crore, but profit before tax jumped 60%. This leverage pushed the net profit margin to 70.4%, up sharply from 43.1% a year ago. The quarter-on-quarter swing is even more dramatic, highlighting the feast-or-famine nature of its business model.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ1 FY27 (Jun 2026) |
|---|---|---|
| Revenue (₹ Cr) | 47.91 | 5.95 |
| Profit (₹ Cr) | 33.72 | 0.68 |
| Net Profit Margin (%) | 70.4 | 11.5 |
The Dividend-Driven Surge
The quarter's strength came from its core function. According to Arthneeti.com, standalone revenue was driven mainly by dividend income of ₹425.01 crore and interest income. This aligns with the company's structure as a Core Investment Company (CIC), as noted by Univest.in. Its 'sales' are dominated by dividend receipts and portfolio marks from holdings in Bharat Forge and other group entities.
This explains the wild volatility between quarters. The quiet June quarter, with revenue of just ₹5.95 crore, gave way to this September surge, mirroring the pattern from a year earlier. The performance is less about operational growth and more about the calendar of payouts from its industrial portfolio.
A Margin Built on Timing
The explosive profit growth far outpacing revenue points to significant operating leverage. Total expenses fell 56.5% year-on-year, as reported in the company's financials. With minimal debt and a lean cost structure, almost every extra rupee of dividend income flows directly to the bottom line when it arrives. This creates the exceptionally high margins seen this quarter.
However, this is not a margin that can be sustained linearly. It is a function of receiving large income against a near-fixed cost base. The trailing twelve-month net profit margin is a more tempered 67.4%, still high but reflecting the averaging effect of quieter quarters.
The Sustainability Question
Analyst skepticism centers on this earnings volatility. A MarketsMojo report from October highlighted concerns over “persistently weak financial performance” and “significant erosion in operational efficiency,” downgrading the stock to Strong Sell. The report pointed to low institutional ownership and a disconnect between valuation and financial health as key risks.
The outlook is tied directly to its investee companies. Bharat Forge, a major holding, expects 20-25% growth in FY27, as per CNBC-TV18. Another key holding, Kalyani Steels, reported a 28% rise in Q2 net profit. Strong performance from these portfolio companies supports future dividend potential, but the timing of those payments remains the unpredictable variable for Kalyani Investment's own quarterly numbers.
Key Points
- Net profit surged 78% year-on-year to ₹33.72 crore, dramatically rebounding from a weak June quarter.
- The jump was driven by seasonal dividend income from group companies, leveraging the firm's low-cost structure.
- Quarterly earnings are inherently volatile, with revenue swinging from ₹44 crore to ₹6 crore over the past five quarters.
- Analyst concerns focus on earnings sustainability and low return metrics, despite a debt-free balance sheet.
Hexa Perspective
This quarter is a clear demonstration of Kalyani Investment's business model: high margins when dividends hit, shallow troughs in between. The 70% net margin is impressive but ephemeral, a peak in a sharply saw-toothed earnings pattern. Investors are essentially betting on the dividend-generating capacity and valuation of the underlying Kalyani Group portfolio. The stock's premium valuation—trading at 190% above the industry PE—prices in the quality of those assets but may not fully account for the lumpiness and lack of control over income timing. The coming quarters will hinge less on management execution and more on the dividend declarations of Bharat Forge and its peers.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.