Vintage Coffee (VINCOFE) Q2 FY27 Sales Jump 64% as Capacity Hits Full Stride
Vintage Coffee's revenue soared on full capacity utilization, but net margins narrowed as expansion costs and a higher tax rate weighed on profit growth.
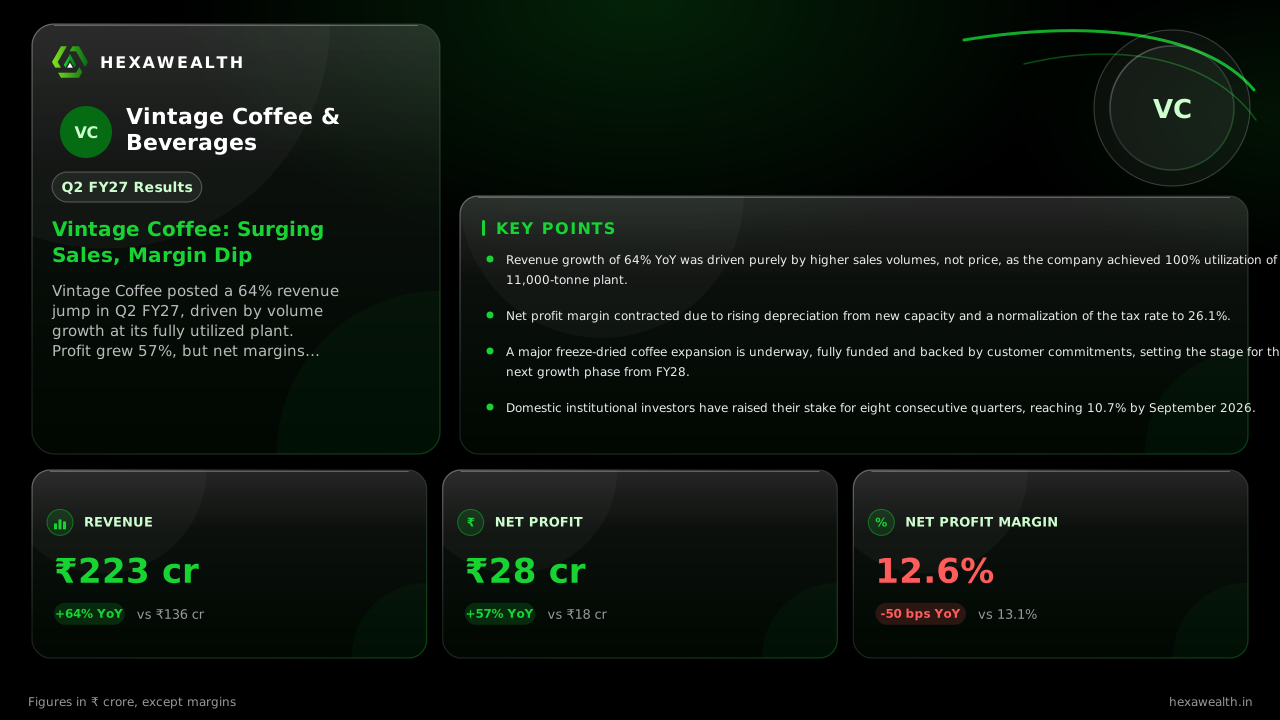
Vintage Coffee posted a 64% revenue jump in Q2 FY27, driven by volume growth at its fully utilized plant. Profit grew 57%, but net margins contracted due to rising costs and a higher effective tax rate.
For an instant coffee exporter, growth is a function of capacity and orders. Vintage Coffee entered the September quarter with its plant running at full tilt for the first time, and the numbers show what that scale can deliver.
Revenue surged 64% year-on-year to ₹223 crore, while net profit climbed 57% to ₹28 crore. The quarter-on-quarter gains were equally sharp, with sales up 39% and profit up 35%. A five-quarter view shows a steady climb in both metrics.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 223.0YoY +64% | 161.0 | 135.6 |
| Profit (₹ Cr) | 28.0YoY +57% | 20.8 | 17.8 |
| Net Margin (%) | 12.6YoY -3.8% | 12.9 | 13.1 |
Why profit growth trailed sales
Despite the strong top line, net profit margin slipped 50 basis points from a year ago and 30 basis points sequentially. The Investing.com transcript shows EBITDA margin actually expanded 244 basis points, helped by a richer product mix. The pressure came from two places below that line.
First, depreciation and employee costs rose faster than revenue as the company absorbed its expanded capacity. Second, the effective tax rate jumped to 26.1% from about 10% in Q2 FY26, as noted by Stockwatch. This higher normalized rate, which management had guided towards, took a larger bite out of pre-tax profit.
The expansion funding the next leg
Growth is set to continue, but not without cost. Management, cited by Arthneeti, confirmed a ₹500-550 crore freeze-dried coffee plant is under construction, funded by internal cash and debt. The board has already raised its borrowing limit to ₹1,000 crore for this capex.
The company told Investing.com it has letters of intent for 100% of this new plant's 5,500-tonne capacity. This project, slated to start in the second half of FY28, will lift total capacity by 50% to 16,500 tonnes. For now, the existing plant is at 100% utilization with a strong order book for Q3.
Key Points
- Revenue growth of 64% YoY was driven purely by higher sales volumes, not price, as the company achieved 100% utilization of its 11,000-tonne plant.
- Net profit margin contracted due to rising depreciation from new capacity and a normalization of the tax rate to 26.1%.
- A major freeze-dried coffee expansion is underway, fully funded and backed by customer commitments, setting the stage for the next growth phase from FY28.
- Domestic institutional investors have raised their stake for eight consecutive quarters, reaching 10.7% by September 2026.
Hexa Perspective
The quarter confirms Vintage Coffee's operational model works at scale: fill the plant and profits follow. The margin compression is not a cost crisis but the arithmetic of a capital-intensive ramp-up, where depreciation runs ahead of revenue for a quarter or two.
The story now turns to execution. The stock's 7.4% jump on results day, reported by HDFC SKY, prices in the current success. The next move depends on seamlessly layering the freeze-dried capex onto a business already at full throttle, without straining the balance sheet. The promised demand is there; the challenge is delivering it.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.