Shivalik Bimetal (SBCL) Q2 FY27's Q2 Growth Masks a Margin Squeeze
The precision components maker delivered a 44% revenue surge in Q2 FY27, but rising costs and a strategic shift are pressuring its net profit margin.
Shivalik Bimetal Controls reported a 44% jump in Q2 FY27 revenue, yet net profit growth lagged. The margin squeeze stems from higher depreciation and interest costs, alongside a strategic move into lower-margin assembly work.
For Shivalik Bimetal Controls, the September quarter was about a powerful top-line engine meeting new cost pressures. The precision components maker, riding structural demand from EVs and smart meters, posted its strongest revenue growth in recent quarters. Yet, the bottom line told a more nuanced story of a strategic pivot that is reshaping profitability.
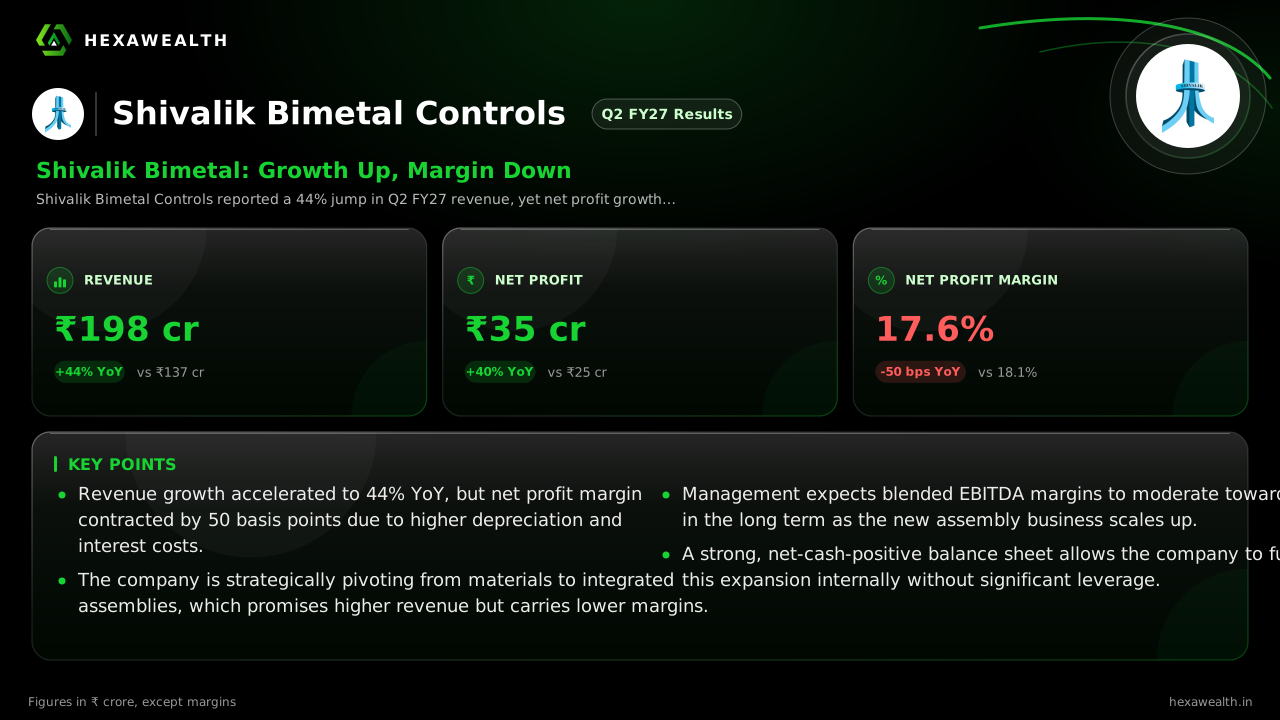
The numbers show a business accelerating. Revenue hit ₹197.8 crore, up 44% from a year ago and 8.6% sequentially. Profit after tax grew a healthy 39.8% YoY to ₹34.8 crore. However, the net profit margin contracted by 50 basis points both yearly and quarterly to 17.6%, as costs rose faster than sales.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 197.79YoY +44% | 182.20 | 137.40 |
| Profit (₹ Cr) | 34.75YoY +40% | 33.01 | 24.85 |
| Net Profit Margin | 17.6%YoY -2.8% | 18.1% | 18.1% |
The cost of moving downstream
Growth was broad-based, but the margin pressure had clear sources. According to the Investing.com presentation, the company is shifting from selling raw bimetal strips to higher-value finished components. This lifted average shunt resistor realizations by about 46%, even as volume fell.
The strategic move downstream, however, comes with a price tag. Depreciation surged 61% YoY and 37% QoQ to ₹5.4 crore, reflecting recent capacity additions. Interest expense jumped 84% YoY to ₹2.1 crore. Management, cited by Investing.com, explained this is tied to working capital for converting inventory into finished goods and new assembly work.
A pivot that will define margins
Management’s guidance, reported by Investing.com, confirms this is a deliberate, lasting shift. The new assembly business for busbars and PCBAs could bring ₹100-200 crore of revenue in FY27-28. But it targets 15-16% EBITDA margins, well below the core business's 26-27%.
Consequently, the company expects blended EBITDA margins to moderate over time toward a long-term range of 20-22%. This explains why net profit growth, though strong, trailed revenue growth this quarter. The payoff is in locking in customer relationships and tapping a larger market.
Funding growth without strain
Despite the rising interest cost, the balance sheet remains a strength. The Investing.com presentation notes the company is net cash positive, with ₹105 crore in cash against ₹59 crore of debt. This self-funded model supports its capex plans in automation and downstream processes without equity dilution.
The stock, trading at a P/E of 23.4, carries a 134% premium to its industry. This prices in the high-growth narrative. With shares up 126% in the past year, the market is betting the margin trade-off for strategic growth is the right one.
Key Points
- Revenue growth accelerated to 44% YoY, but net profit margin contracted by 50 basis points due to higher depreciation and interest costs.
- The company is strategically pivoting from materials to integrated assemblies, which promises higher revenue but carries lower margins.
- Management expects blended EBITDA margins to moderate toward 20-22% in the long term as the new assembly business scales up.
- A strong, net-cash-positive balance sheet allows the company to fund this expansion internally without significant leverage.
Hexa Perspective
Shivalik Bimetal’s quarter reveals a company successfully executing a high-stakes transition. The 44% revenue growth validates demand, but the 50 bps margin dip is the early cost of moving downstream. The critical question is the timing and scale of the assembly business ramp-up.
If new programs move swiftly from development to production, the top-line momentum could sustain the premium valuation despite margin compression. The risk is that the lower-margin work grows faster than expected, pressuring returns before the strategic benefits fully materialize. For now, the strong balance sheet provides a cushion to navigate this shift.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.