Saksoft (SAKSOFT) Q2 FY27 Profit Rises 9% Despite Flat Revenue as AI Shift Bites
Saksoft's Q2 FY27 profit grew sequentially, but revenue fell 4% year-on-year as its strategic pivot to AI product engineering caused short-term cannibalization.
Saksoft reported a 9.3% sequential rise in net profit to ₹32 crore for Q2 FY27, though revenue slipped 3.7% year-on-year. The company's AI-first transformation is pressuring near-term sales but improving the bottom line through lower costs and interest.
For Saksoft, the September quarter was a story of strategic transition taking precedence over immediate growth. The mid-sized IT services firm, repositioning itself as an AI product engineering company, saw its revenue contract year-on-year while profit improved sequentially, highlighting the near-term trade-offs of its new focus.
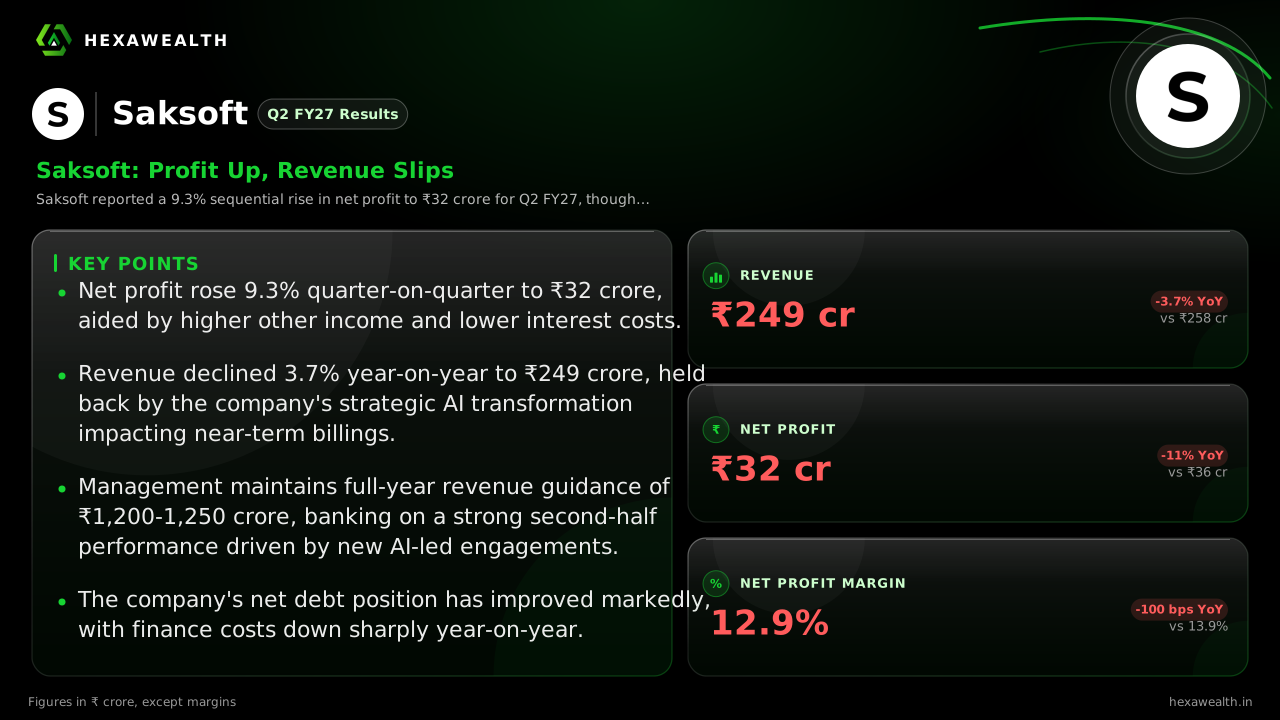
Revenue for Q2 FY27 was essentially flat from the prior quarter at ₹249 crore, but marked a 3.7% decline from the same period last year. Net profit, however, rose 9.3% sequentially to ₹32 crore, though it remained 11% lower year-on-year. The net profit margin improved to 12.9%, up 110 basis points from Q1.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 249.0YoY -3.7% | 248.6 | 258.5 |
| Profit (₹ Cr) | 32.0YoY -11% | 29.3 | 36.0 |
| Net Profit Margin | 12.9%YoY -7.2% | 11.8% | 13.9% |
Why the bottom line improved
The sequential profit growth was not driven by core operations. According to a scanx.trade report, operating EBITDA margin actually contracted by 66 basis points. Instead, the improvement came from a 70.6% jump in other income and a 20.8% drop in interest expense.
Lower interest costs reflect a stronger balance sheet. An analysis by Arthneeti notes that Saksoft has significantly reduced its borrowings, cutting finance costs by half in the first half of FY27 compared to the prior year. This deleveraging provided a steady tailwind to profitability.
The AI transition's short-term cost
Management directly attributes the flat revenue to its strategic shift. Chairman Aditya Krishna stated the company is proactively offering free proofs of concept and implementing AI to reduce client team sizes, as reported by scanx.trade. He acknowledged this causes “revenue cannibalization in the short term” but is intended to build deeper, co-innovation partnerships for the long term.
This explains the year-on-year decline. The company is trading traditional service volumes for what it hopes will be higher-value, outcome-based AI engagements. The guidance for FY27 revenue remains ₹1,200-1,250 crore, implying a significant second-half acceleration is required.
Key Points
- Net profit rose 9.3% quarter-on-quarter to ₹32 crore, aided by higher other income and lower interest costs.
- Revenue declined 3.7% year-on-year to ₹249 crore, held back by the company's strategic AI transformation impacting near-term billings.
- Management maintains full-year revenue guidance of ₹1,200-1,250 crore, banking on a strong second-half performance driven by new AI-led engagements.
- The company's net debt position has improved markedly, with finance costs down sharply year-on-year.
Hexa Perspective
The quarter underscores a company in the midst of a deliberate, and somewhat painful, pivot. Saksoft is sacrificing current revenue growth to reposition its client relationships around AI, a bet that its medium-term prospects depend on. The maintained full-year guidance is ambitious, requiring a nearly 50% sequential revenue jump in the second half.
Investors are weighing the strength of the underlying pipeline against the visible near-term top-line pressure. The improving balance sheet and cost control provide a margin of safety, but the stock’s significant underperformance over the past year reflects skepticism about the pace of this transformation paying off.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.