Powerica (POWERICA) Q2 FY27 Profit Drops 15.6% as Rising Costs Squeeze Record Revenue
The power solutions provider posted its highest-ever quarterly revenue, but surging input costs and supply constraints led to a significant year-on-year profit contraction.
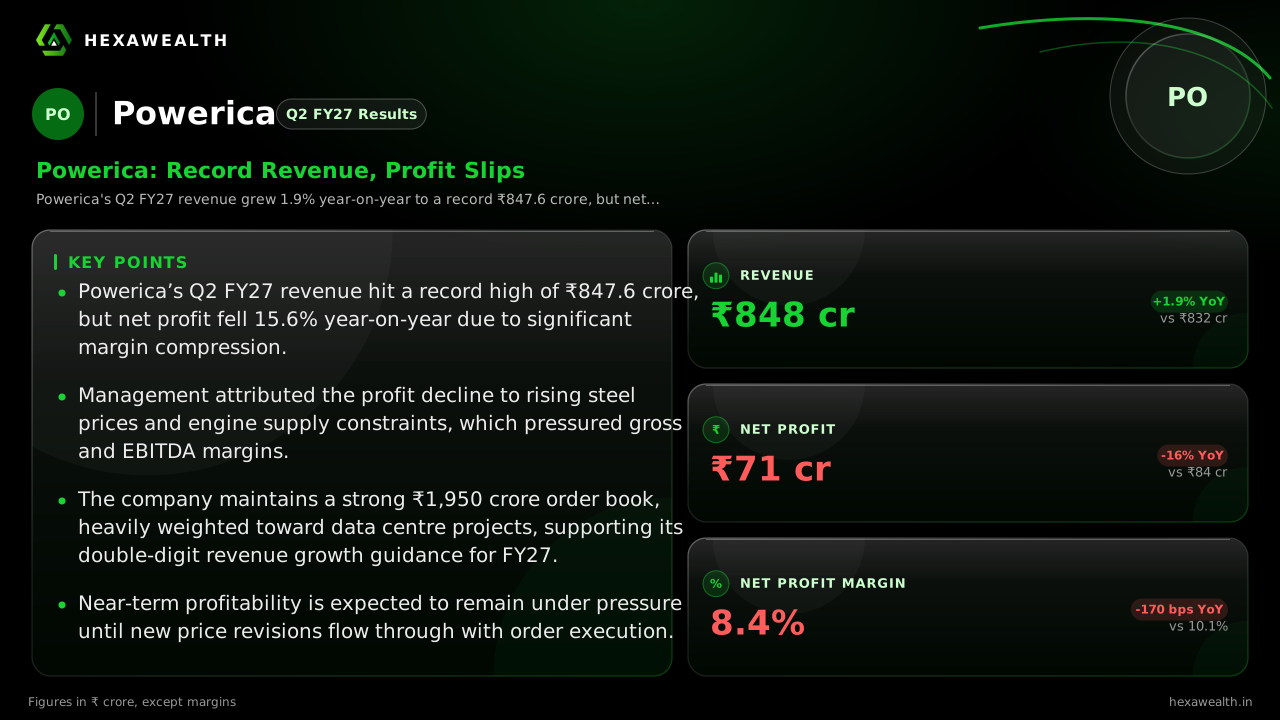
Powerica's Q2 FY27 revenue grew 1.9% year-on-year to a record ₹847.6 crore, but net profit fell 15.6% to ₹70.9 crore. The decline was driven by margin compression from rising steel prices and engine supply constraints, despite a robust ₹1,950 crore order book.
For Powerica, a leading diesel generator and wind power solutions provider, the September quarter was a story of strong demand meeting stubborn costs. The company delivered its highest-ever quarterly revenue, yet profit fell sharply as rising input prices and supply chain issues squeezed margins.
The numbers show a clear divergence. Revenue from operations reached ₹847.6 crore, a 1.9% increase from a year ago and an 8.7% sequential improvement. However, profit after tax (PAT) declined 15.6% year-on-year to ₹70.9 crore, though it did recover 10.1% from the June quarter. The net profit margin contracted by 170 basis points to 8.4%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 847.6YoY +1.9% | 780.11 | 832.0 |
| Profit (₹ Cr) | 70.92YoY -16% | 64.43 | 84.0 |
| Net Profit Margin (%) | 8.4YoY -17% | 8.3 | 10.1 |
Where the Profit Went
Management, cited by reports from multibagg.ai and scanx.trade, pointed squarely at rising input costs and engine supply constraints. Steel, a major raw material, saw renewed price hikes with suppliers announcing further increases. This drove a 7.4% year-on-year drop in gross profit, compressing the gross margin to 35.1% from 38.6%.
Depreciation also nearly doubled year-on-year to ₹39.9 crore, a structural increase reflecting ongoing capital expenditure in wind power projects. While lower interest costs provided some relief, it was not enough to offset the operating margin pressure.
A Strong Pipeline Meets Near-Term Headwinds
The core generator set business, contributing over 80% of revenue, is supported by a robust order book. As of October 2026, the Cummins-powered DG-set order book stood at approximately ₹1,950 crore, with about ₹1,200 crore linked to data centres, according to investor presentations.
Management has maintained its guidance for double-digit revenue growth in FY27, supported by this backlog. However, the near-term outlook for margins remains cautious. Reports indicate that pressure is likely to persist until new price revisions take effect with the execution of fresh orders.
The wind power segment, with its high 47.4% EBITDA margin in H1, offers a profitable counterbalance. The company recently secured a letter of intent for a 50 MW wind project, adding to its renewable energy pipeline.
Market Reaction and the Path Forward
The stock fell 5.11% on November 6, closing at ₹468.60, as the market digested the profit decline against high expectations. MarketsMojo highlighted a “troubling exodus” of foreign institutional investors and downgraded the stock to “SELL,” citing fundamental concerns despite sequential margin recovery.
The quarter underscores a transitional phase. Powerica’s revenue visibility is excellent, but converting that top line into bottom-line growth hinges on managing commodity costs and supply chains. The next few quarters will test its pricing power and execution agility.
Key Points
- Powerica’s Q2 FY27 revenue hit a record high of ₹847.6 crore, but net profit fell 15.6% year-on-year due to significant margin compression.
- Management attributed the profit decline to rising steel prices and engine supply constraints, which pressured gross and EBITDA margins.
- The company maintains a strong ₹1,950 crore order book, heavily weighted toward data centre projects, supporting its double-digit revenue growth guidance for FY27.
- Near-term profitability is expected to remain under pressure until new price revisions flow through with order execution.
Hexa Perspective
Powerica’s quarter presents a classic growth-versus-margin tension. The record revenue and formidable order book confirm strong underlying demand, particularly from data centres and infrastructure. Yet, the 170-basis-point year-on-year contraction in PAT margin reveals how quickly input cost inflation can erode earnings.
The sequential margin improvement is a positive sign that earlier price actions are starting to work. The key question is whether future price revisions can outpace persistent cost pressures. With a deleveraged balance sheet providing financial flexibility, the company’s ability to navigate this cost environment while executing its large backlog will define its earnings trajectory over the next year.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.