Perfectpac (PERFEPA) Q2 FY27 Profit Falls 27% as Costs Outrun Flat Revenue
The packaging firm's Q2 earnings show a sharp profit drop despite steady sales, as rising employee and material costs squeeze margins.
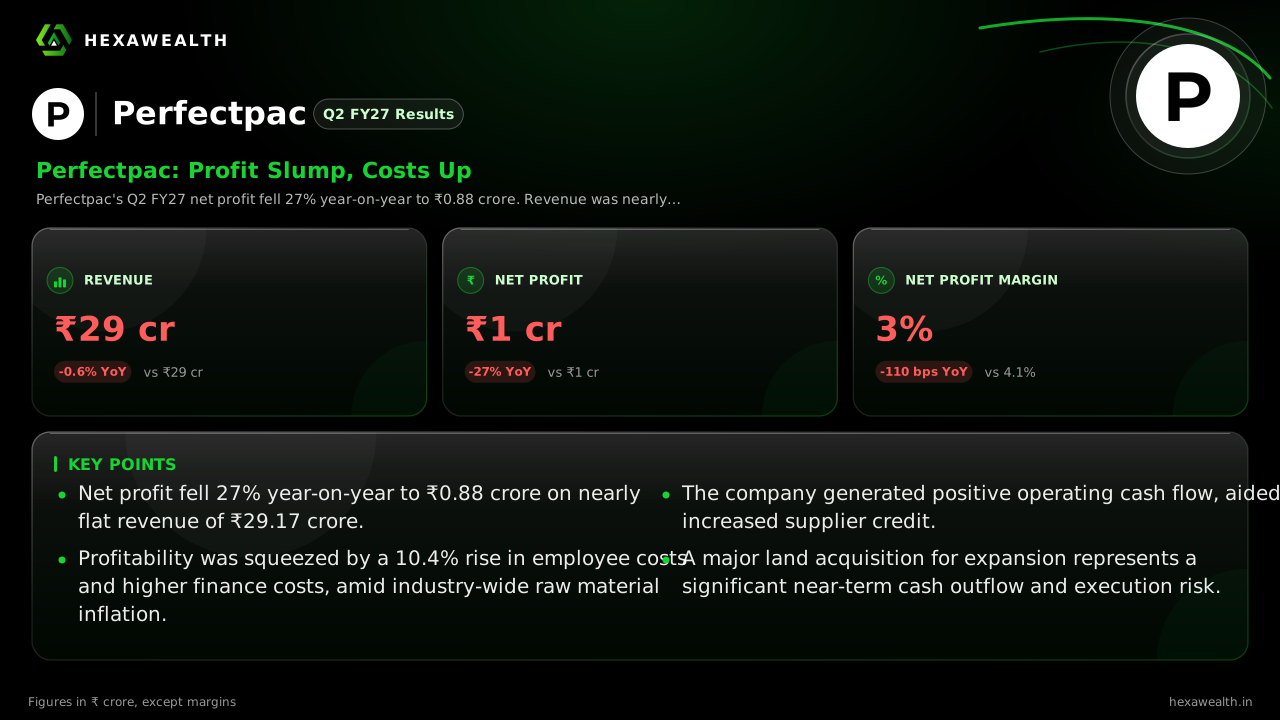
Perfectpac's Q2 FY27 net profit fell 27% year-on-year to ₹0.88 crore. Revenue was nearly flat, but a 10% jump in employee costs and higher interest expenses compressed the net profit margin to 3%.
For a corrugated box maker, the story is written in the gap between stable shipments and the runaway cost of making them. Perfectpac's September quarter shows that tension clearly, with sales holding firm but profits falling sharply as expenses climbed.
The numbers tell a story of margin pressure. Revenue was nearly unchanged at ₹29.17 crore, a slight 0.6% dip from last year. Net profit, however, fell 27% to ₹0.88 crore. The net profit margin contracted by 110 basis points to 3.0%.
Revenue & profit
Revenue (₹ Cr)
Net Profit (₹ Cr)
Net Profit Margin
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ1 FY27 (Jun 2026) |
|---|---|---|
| Revenue (₹ Cr) | 29.17 | 28.54 |
| Net Profit (₹ Cr) | 0.88 | 0.51 |
| Net Profit Margin | 3.0% | 1.8% |
Where the profit disappeared
A 10.4% year-on-year surge in employee benefit expenses was the largest identified cost increase, according to a report by Multibagg.ai. Material costs and finance costs also rose, while other income fell 68%. This combination turned a flat top line into a shrinking bottom line.
The cost surge is not a one-off but an industry-wide squeeze. The Hindu Businessline reported in October that kraft paper prices, which make up 75% of a box's cost, have jumped 25-35%. Geopolitical disruptions and freight rate hikes are pressuring raw material supply.
A cash cushion amid the strain
Despite the profit drop, the company generated positive operating cash flow of ₹3.93 crore for the half-year. This was supported by a sharp rise in trade payables, as noted by Scanx.trade, suggesting it is leveraging supplier credit to manage working capital as receivables grow.
The expansion overhang
Investors are also weighing a major capital commitment. In August, Perfectpac was allotted a 16,200 sqm industrial plot for ₹22.74 crore to build a new facility. An analysis by Flash Finance warned the land cost alone equals 58% of net worth, with payment due within 90 days, creating a severe near-term cash drain.
Key Points
- Net profit fell 27% year-on-year to ₹0.88 crore on nearly flat revenue of ₹29.17 crore.
- Profitability was squeezed by a 10.4% rise in employee costs and higher finance costs, amid industry-wide raw material inflation.
- The company generated positive operating cash flow, aided by increased supplier credit.
- A major land acquisition for expansion represents a significant near-term cash outflow and execution risk.
Hexa Perspective
The quarter confirms Perfectpac is caught in a classic packaging margin squeeze: input costs are rising faster than selling prices can adjust. The sequential profit recovery from a low Q1 base is encouraging but remains well below last year's level.
The critical question is how long the cost pressure lasts. With kraft paper inflation driven by global factors, relief may not be immediate. Meanwhile, the large land payment due soon will test the balance sheet. Investors are left weighing a stable, cash-generative core business against a costly expansion plan in a tough margin environment.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.