Prospect Consumer Products (PCL) Q4 FY26 Profit Plunges 62% Despite 56% Revenue Jump
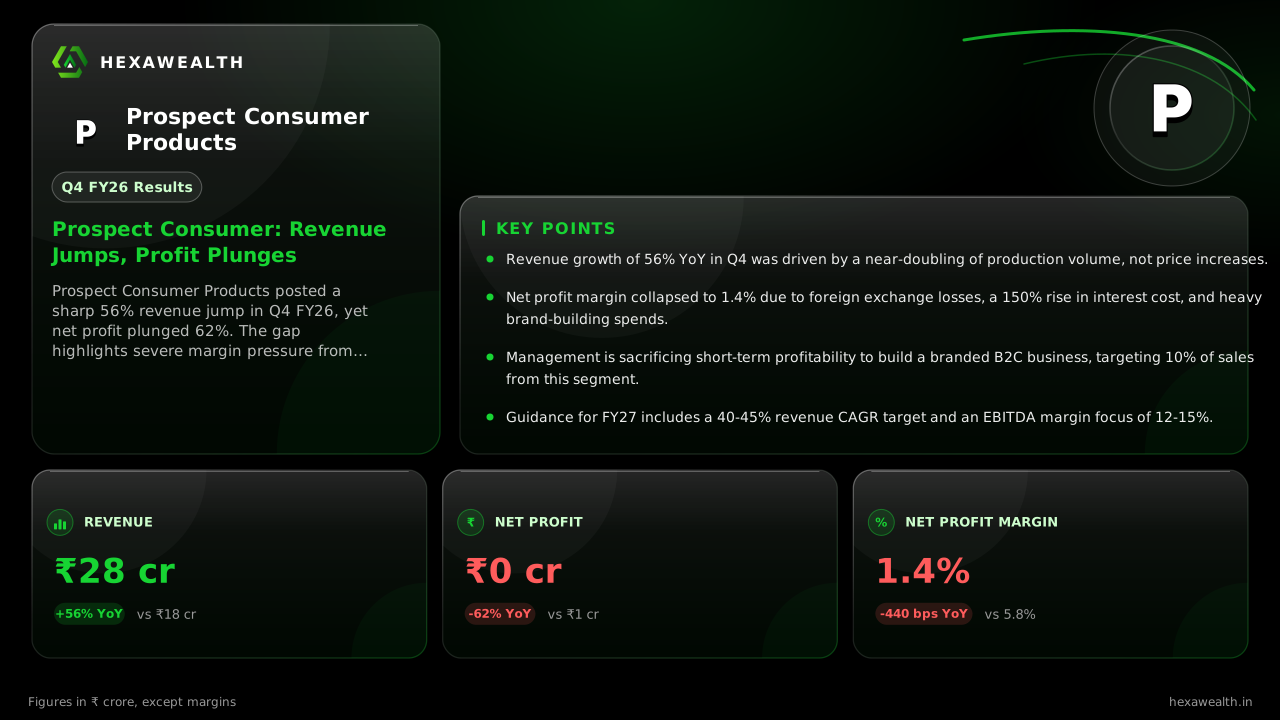
Prospect Consumer Products' Q4 FY26 saw revenue surge 56% year-on-year, but net profit collapsed 62% as costs from forex, interest, and brand-building bit deep.
Prospect Consumer Products posted a sharp 56% revenue jump in Q4 FY26, yet net profit plunged 62%. The gap highlights severe margin pressure from rising raw material costs, higher interest expenses, and aggressive spending on its new D2C brand.
For a cashew processor scaling rapidly, the tension between volume growth and profitability defines the journey. Prospect Consumer Products' March quarter laid it bare, with revenue soaring 56% year-on-year while net profit collapsed by 62%.
The numbers tell a story of expansion at a cost. Revenue reached ₹27.9 crore, but net profit slimmed to just ₹0.4 crore. The net profit margin compressed to 1.4%, down 440 basis points from last year and 560 points from the strong September quarter.
Revenue & profit
Revenue (₹ Cr)
Net Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ4 FY26 | Same quarter LYQ4 FY25 |
|---|---|---|
| Revenue (₹ Cr) | 27.9YoY +56% | 17.84 |
| Net Profit (₹ Cr) | 0.4YoY -62% | 1.04 |
| Net Profit Margin (%) | 1.4YoY -76% | 5.8 |
Why the bottom line vanished
Management, on the AlphaStreet earnings call, pointed to a perfect storm. A sharp rupee depreciation raised the average cost of imported raw cashews. Interest expense jumped 150% as the company utilized working capital debt to fund higher production. Aggressive marketing for the new DriFrutz brand and developing 24 stock-keeping units also pressured profits. The Arthneeti report notes the company is focusing on EBITDA, targeting 12-15%, with PAT expected around 5-7%.
The push beyond commodities
This spending is part of a deliberate pivot. The company wants to be an FMCG player, not just a commodity trader. Its B2C segment, including gifting and e-commerce, is targeted to reach 10% of revenue. Currently, it contributes a modest ₹50-60 lakh, as per the call. The bet is that brand-building now will yield pricing power and diversification later.
The costs that will not fall soon
Raw material costs, driven by global markets, remain a headwind. The Cashew Market report from Commodity Board notes firm kernel prices due to tight supply and higher raw nut costs. Interest costs will persist as the company plans to further scale capacity utilization from 2,500-3,000 tons to 3,500-4,000 tons this year, funded partly by debt.
Key Points
- Revenue growth of 56% YoY in Q4 was driven by a near-doubling of production volume, not price increases.
- Net profit margin collapsed to 1.4% due to foreign exchange losses, a 150% rise in interest cost, and heavy brand-building spends.
- Management is sacrificing short-term profitability to build a branded B2C business, targeting 10% of sales from this segment.
- Guidance for FY27 includes a 40-45% revenue CAGR target and an EBITDA margin focus of 12-15%.
Hexa Perspective
The quarter exposes the raw economics of scaling a commodity-linked business while funding a strategic shift. Volume growth is impressive, but profitability is hostage to currency swings and input costs. The investment case now hinges on execution. Can the DriFrutz brand gain enough traction to offset these pressures and deliver the promised 5-7% PAT margin? The next few quarters will test whether this costly build-out translates into sustainable premium returns or remains a drag on earnings.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.