All posts

Follow Us

LinkedInInstagramX
Quarterly ResultsArchiveLast updated 7 November 20263 min read

Parker Agrochem (PARKERAC) Q2 FY27 Swings to Loss as Operational Costs Spiral

The tank storage firm posted a Q2 FY27 net loss of ₹0.08 crore, a sharp reversal from profit, as total expenses jumped over 50% year-on-year.

By Abhinav Singhvi, Founder & CEO Hexawealth · Created 7 November 2026

Parker Agrochem Exports swung to a quarterly loss despite stable revenue, as a surge in operational expenses erased margins. The company faces a critical test to restore profitability amid port congestion and volatile demand.

For Parker Agrochem, the business of renting storage tanks at Kandla port depends on steady utilisation and controlled overheads. The September quarter saw that balance break, turning a modest revenue stream into a loss as costs ran far ahead of income.

The numbers show a company under operational stress. Revenue was ₹1.47 crore, down 2.6% from a year ago. Profit swung to a loss of ₹0.08 crore from a profit of ₹0.47 crore in Q2 FY26. The net profit margin collapsed to -5.4%, a drop of over 36 percentage points year-on-year.

Revenue & profit

Revenue (₹ Cr)

Profit (₹ Cr)

Net Profit Margin (%)

MetricCurrentQ2 FY27PreviousQ1 FY27Same quarter LYQ2 FY26
Revenue (₹ Cr)
1.47YoY -2.6%
1.66
1.51
Profit (₹ Cr)
-0.08YoY -117%
0.26
0.47
Net Profit Margin (%)
-5.4YoY -117%
15.8
30.9

Where the profit vanished

Total expenses surged 53.3% year-on-year to ₹1.61 crore. MarketsMojo reported that employee costs were stable, suggesting the spike came from other operational inefficiencies. This turned a ₹0.39 crore operating profit in Q1 into a ₹0.09 crore operating loss in Q2, one of the sharpest quarterly deteriorations in recent history.

The pressure reflects a tough environment at its home port. Research from GlobOil India and Procurement Resource indicates Kandla is congested, with shore tanks full and vessels waiting to discharge. When storage tanks are full, rental income is capped, but fixed costs continue.

A related-party lifeline

A potential stabiliser is a new five-year contract with Parker Agrochem Products Pvt. Ltd., a related party. Shareholders approved the deal in September, as reported by ScanX Trade. It could bring up to ₹6 crore annually in tank rentals starting October 2026.

That contract represents future security, not current relief. Management provided no forward guidance during its recent AGM, notes StockFin.ai. The immediate task is to restore basic operational discipline after a quarter where costs overwhelmed a ₹1.5 crore revenue base.

Key Points

  • The company swung to a net loss of ₹0.08 crore in Q2 FY27 from a profit of ₹0.26 crore in the prior quarter.
  • A 53% year-on-year surge in total expenses, not driven by wages, caused a severe margin collapse.
  • A newly approved five-year related-party storage contract offers future revenue visibility but does not address near-term cost pressures.
  • The stock trades at a significant discount to the sector, with a P/E of 6.2 against an industry average of 41.0.

Hexa Perspective

The quarter poses a straightforward question of operational control. Revenue has held in a ₹1.4-1.7 crore band for five quarters, but profit has swung wildly from 30% margins to a loss.

This volatility makes the business hard to value, which the 85% sector discount acknowledges. The new related-party contract should anchor revenue, but the cost structure that imploded this quarter needs fixing first. Investors are left weighing deep value against unproven stability.

Share or follow HexaWealth

Also read

Want this applied to your portfolio?

Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.
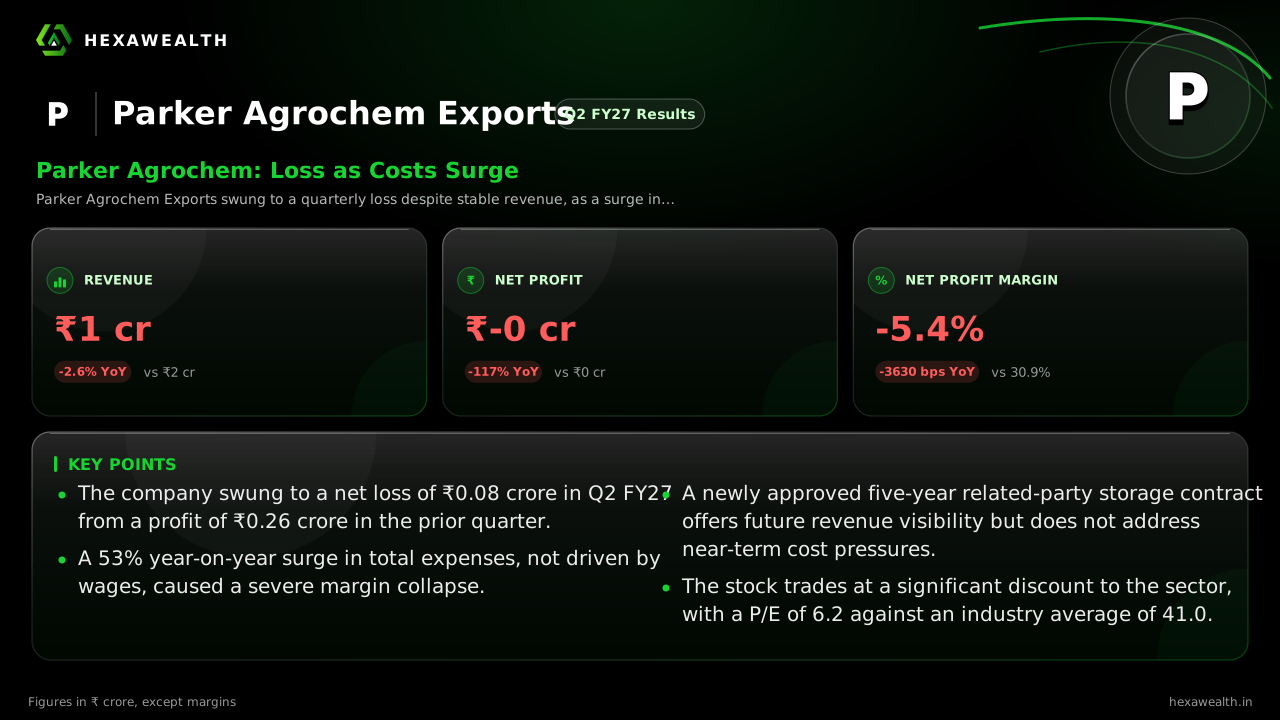
Parker Agrochem Exports (PARKERAC) Q2 FY27 results, revenue and profits.

Frequently asked questions

What were Parker Agrochem's Q2 FY27 results?
Parker Agrochem Exports reported a net loss of ₹0.08 crore for Q2 FY27 (quarter ended September 2026), on revenue of ₹1.47 crore. This was a sharp reversal from a net profit of ₹0.47 crore in the same quarter last year, driven by a 53% surge in total expenses.
Why did Parker Agrochem's Q2 FY27 profit turn into a loss?
Parker Agrochem's profit turned to a loss in Q2 FY27 primarily because total expenses jumped 53.3% year-on-year to ₹1.61 crore. Analysis from MarketsMojo suggests this margin collapse stemmed from operational inefficiencies, as employee costs remained stable.
What caused the drop in Parker Agrochem's Q2 revenue from Q1?
Parker Agrochem's revenue fell 11.4% sequentially to ₹1.47 crore in Q2 FY27 from ₹1.66 crore in Q1. The decline occurred amid reported congestion at Kandla port, where full storage tanks can limit new rental income.
Was the expense spike in Parker Agrochem's Q2 a one-off cost?
The Q2 expense surge does not appear to be a one-off. MarketsMojo reported employee costs were stable, indicating the 53% year-on-year rise in total expenses was due to broader operational inefficiencies rather than a singular event.
What guidance did Parker Agrochem management provide for Q2 FY27?
Parker Agrochem's management did not provide any forward-looking guidance during its Annual General Meeting in September 2026, as noted by StockFin.ai. The absence of commentary suggests limited visibility into near-term performance drivers.
What is the status of Parker Agrochem's storage tank contracts?
Parker Agrochem shareholders recently approved a new five-year related-party contract. As reported by ScanX Trade, the deal with Parker Agrochem Products Pvt. Ltd. could generate up to ₹6 crore annually in rentals from October 2026 to September 2031.
What is the demand environment at Kandla port for storage?
Demand for storage at Kandla port is high, but it has created congestion. Reports from GlobOil India indicate shore tanks are full, with vessels facing unloading delays. This environment caps new rental income for tank farm operators like Parker Agrochem.
Does Parker Agrochem have any new long-term contracts?
Yes. Parker Agrochem has a new five-year contract with related party Parker Agrochem Products Pvt. Ltd., approved in September 2026. ScanX Trade reported the deal has a maximum annual value of ₹6 crore for storage tank rentals.
Did Parker Agrochem declare a dividend with its Q2 FY27 results?
No, Parker Agrochem did not declare a dividend with its Q2 FY27 results. StockFin.ai noted that no dividend or capital return was proposed during the company's Annual General Meeting held in September 2026.
Did Parker Agrochem's Q2 results beat analyst estimates?
Available research does not cite specific analyst estimates for Parker Agrochem's Q2 FY27. The reported loss of ₹0.08 crore was characterised as a severe deterioration from prior profitable quarters by outlets like MarketsMojo.
Are any brokerages changing their rating on PARKERAC after Q2?
No specific brokerage rating changes were found following the Q2 results. A model-based analysis from Fairvalue-Calculator.com in November 2026 suggested the stock was undervalued, but this was not a direct reaction to the quarterly loss.
How did PARKERAC stock react to the Q2 FY27 results?
The stock's immediate reaction on the announcement date is not clear from the research. As of November 6, 2026, the stock price was ₹15.22, and it has declined 33.1% over the past year, reflecting broader underperformance.
Parker Agrochem Q2 FY27 results
Parker Agrochem Exports reported Q2 FY27 (September 2026) results showing a net loss of ₹0.08 crore on revenue of ₹1.47 crore. This marked a severe downturn from a profit of ₹0.47 crore in Q2 FY26, driven by a 53% jump in operating expenses.
Why did Parker Agrochem profits plunge in the recent quarter?
Parker Agrochem's profits plunged to a ₹0.08 crore loss in Q2 FY27 because total expenses skyrocketed by 53% year-on-year. Analysis points to operational inefficiencies as the core issue, eroding margins despite relatively stable revenue.