Mukka Proteins (MUKKA) Q2 FY27 Profit Slips 5% QoQ Even as Revenue Doubles
Mukka Proteins' Q2 revenue more than doubled year-on-year, but profit dipped sequentially as margin pressure and a heavy debt load weighed on the bottom line.
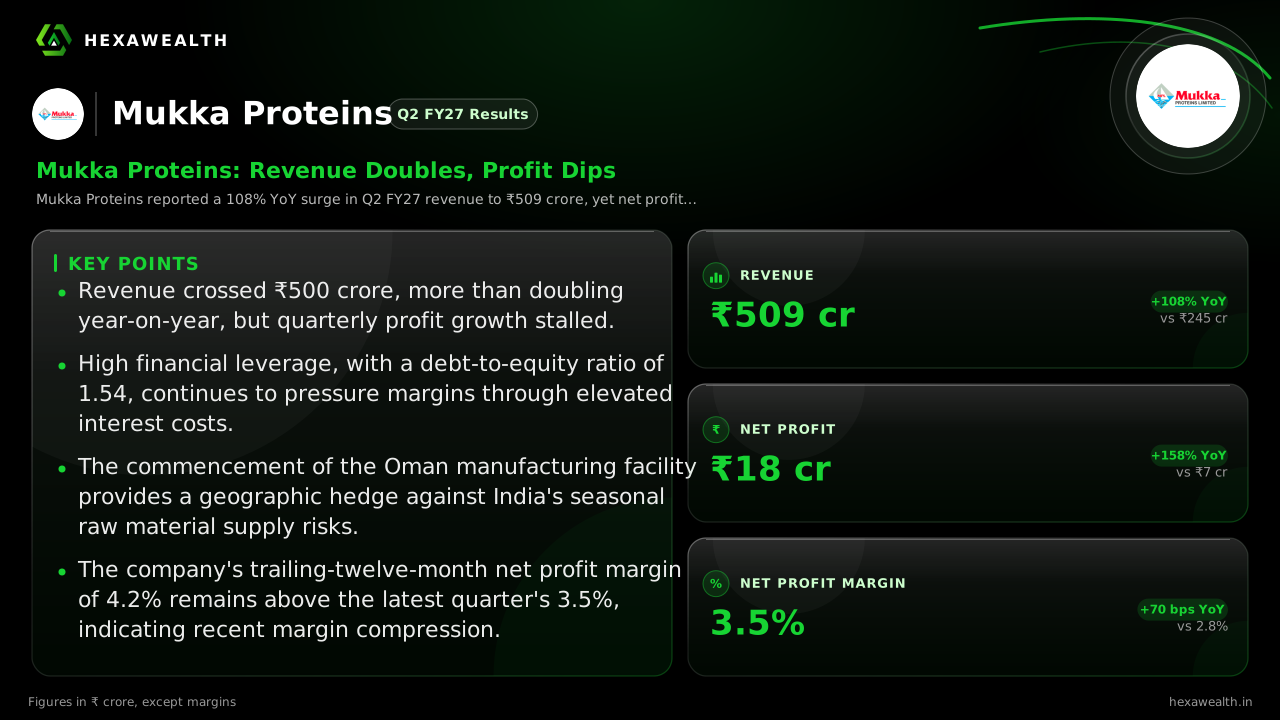
Mukka Proteins reported a 108% YoY surge in Q2 FY27 revenue to ₹509 crore, yet net profit fell 5% from the previous quarter. The fishmeal producer faces margin pressure from rising costs and high debt, even as new international capacity comes online.
For Mukka Proteins, a leading fishmeal and fish oil producer, the September quarter was a story of scale and strain. Revenue more than doubled from a year ago, yet profit slipped from the prior quarter as the costs of rapid expansion and high leverage began to show.
The numbers tell both sides of the story. Revenue reached ₹508.9 crore, up 108% from a weak Q2 last year and 4% from the June quarter. Net profit, however, declined 5% sequentially to ₹17.7 crore. The net profit margin dipped 30 basis points to 3.5%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 508.87YoY +108% | 489.65 | 244.58 |
| Profit (₹ Cr) | 17.73YoY +158% | 18.63 | 6.88 |
| Net Profit Margin | 3.5%YoY +25% | 3.8% | 2.8% |
The margin squeeze beneath the top-line surge
Strong global demand for aquafeed drove the revenue surge, as noted by Sahi Markets. Yet profitability was pinched. According to FlashFinance, operating profit margin fell 149 basis points quarter-on-quarter. Rising interest costs, up 4% QoQ, and a near five-fold jump in other income—which FlashFinance flagged as a one-off item—masked underlying pressure.
A balance sheet stretched for growth
The company's aggressive growth is funded heavily by debt. Borrowings stood at ₹779 crore at the end of FY26, resulting in a debt-to-equity ratio of 1.54. This high leverage, as highlighted by InvestorFeed, directly pressures profits through finance costs of ₹303.5 crore last year. The company is raising more capital, having allotted ₹47 crore in convertible warrants in Q2.
The geographic hedge now in play
A key strategic move is the new Oman facility. Its subsidiary, United Gulf Fishery Products LLC, began commercial production in October. Sahi Markets reports this is a structural hedge against seasonal fish catch volatility in India, aiming to provide year-round raw material supply and stabilize costs.
Key Points
- Revenue crossed ₹500 crore, more than doubling year-on-year, but quarterly profit growth stalled.
- High financial leverage, with a debt-to-equity ratio of 1.54, continues to pressure margins through elevated interest costs.
- The commencement of the Oman manufacturing facility provides a geographic hedge against India's seasonal raw material supply risks.
- The company's trailing-twelve-month net profit margin of 4.2% remains above the latest quarter's 3.5%, indicating recent margin compression.
Hexa Perspective
Mukka Proteins is executing a high-wire act: scaling revenue rapidly in a favorable market while managing the financial strain of that growth. The new Oman plant could ease raw material volatility, a critical risk. Yet, the path to sustained profitability hinges on converting top-line momentum into operating leverage, which remains challenged by its capital structure. Investors are weighing the promise of geographic diversification against the reality of a balance sheet stretched thin.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.