All posts

Follow Us

LinkedInInstagramX
Quarterly ResultsArchiveLast updated 7 November 20262 min read

Tata Chemicals (TATACHEM) Q2 FY27 Profit Slips into Loss as Global Costs Bite

The company's Q2 FY27 revenue grew 8%, but a severe margin squeeze in overseas soda ash operations pushed it to a consolidated loss.

By Abhinav Singhvi, Founder & CEO Hexawealth · Created 7 November 2026

Tata Chemicals reported an 8% rise in revenue for Q2 FY27, but escalating costs and weak pricing in its global soda ash business led to a consolidated net loss of ₹50 crore, highlighting a stark divergence between resilient domestic and pressured international operations.

For Tata Chemicals, the September quarter was a tale of two businesses. While its domestic operations in salt and bicarb delivered, its global soda ash unit faced a perfect storm of oversupply and spiking costs, turning a revenue gain into a loss.

The numbers show the strain. Revenue grew 7.7% year-on-year to ₹4,177 crore. Yet, profit swung to a loss of ₹50 crore from a ₹154 crore profit a year ago. The net profit margin fell 520 basis points to -1.2%.

Revenue & profit

Revenue (₹ Cr)

Profit (₹ Cr)

Net Profit Margin (%)

MetricCurrentQ2 FY27PreviousQ1 FY27Same quarter LYQ2 FY26
Revenue (₹ Cr)
4,177YoY +7.7%
4,255
3,877
Profit (₹ Cr)
-50YoY -132%
60
154
Net Profit Margin (%)
-1.2YoY -130%
1.4
4.0

Why the overseas business bled

The loss was concentrated in the international Industrial Essentials segment, which posted a ₹120 crore loss. According to the company's investor presentation, a global soda ash oversupply led to unremunerative pricing, especially for US exports to Southeast Asia. At the same time, input and fixed costs surged due to geopolitical disruptions and high energy prices, particularly in the UK. The temporary suspension of Kenya operations removed another profit stream.

The domestic anchor holds

In contrast, standalone India operations remained a source of strength. Investing.com reported standalone EBITDA rose 22% year-on-year to ₹292 crore, with margins improving. This resilience came from higher salt volumes and better realizations, partly offsetting the global weakness.

A squeeze with no quick fix

Management's outlook, as noted in the presentation, suggests the pressure is not fleeting. The global soda ash cycle is expected to remain challenging in the near to medium term, with oversupply limiting pricing power. Peers echo this caution; Multibagg.ai reported that GHCL expects soft realizations to persist for several quarters. With net debt rising slightly to ₹6,127 crore, the company has prioritised working capital optimisation and cost control.

Key Points

  • Consolidated profit turned to a ₹50 crore loss despite 8% revenue growth, driven by a severe margin squeeze in overseas soda ash operations.
  • The domestic business provided a counterbalance, with standalone EBITDA growing 22% on stronger volumes and realisations.
  • The global soda ash market remains oversupplied, with high energy and logistics costs expected to pressure margins for the foreseeable future.
  • Management is focusing on portfolio shift towards non-cyclical businesses and strict capital discipline amid the challenging cycle.

Hexa Perspective

This quarter underscores Tata Chemicals' bifurcated reality. The robust India business demonstrates the underlying strength of its essentials portfolio. However, the consolidated loss reveals how deeply exposed it remains to a global commodity cycle that shows no sign of turning. The path to recovery hinges on a rebalancing of global soda ash supply and demand, which is outside the company's control. Until then, investors are weighing the steady domestic cash flows against the persistent drag from international operations, with the stock's 27% one-year decline reflecting that uncertainty.

Share or follow HexaWealth

Also read

Want this applied to your portfolio?

Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.
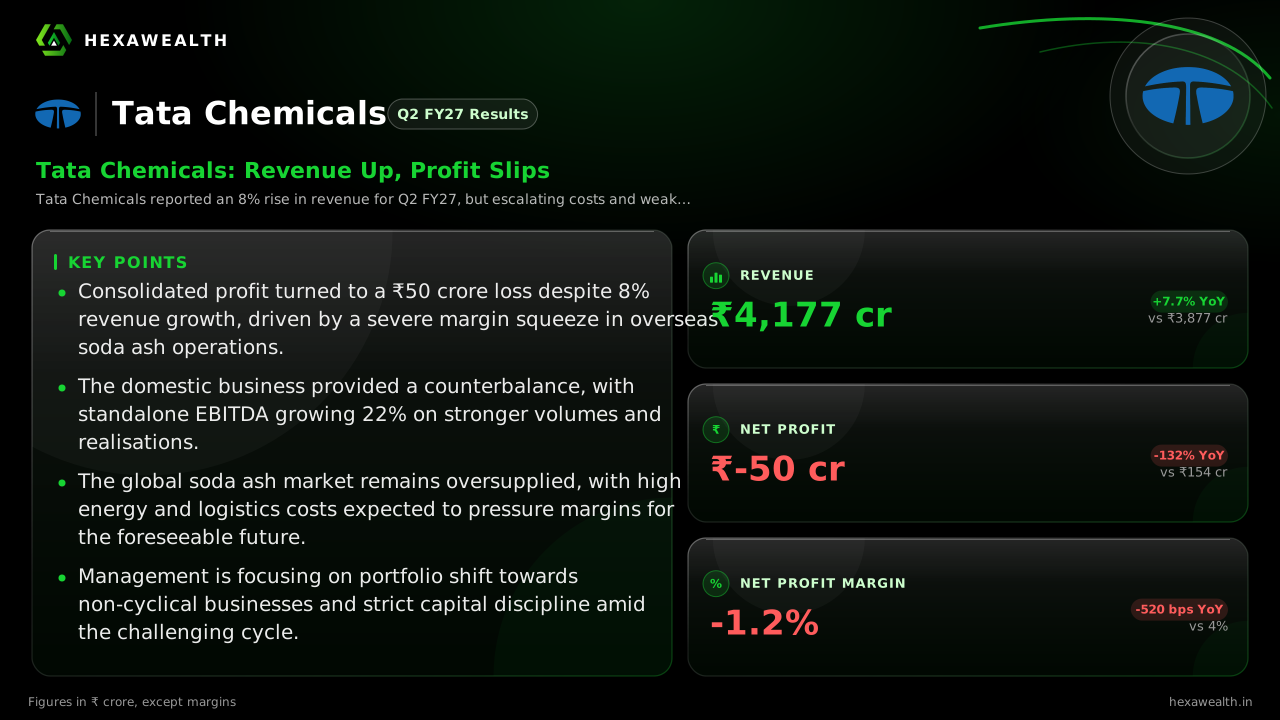
Tata Chemicals (TATACHEM) Q2 FY27 results, revenue and profits.

Frequently asked questions

What were Tata Chemicals' Q2 FY27 results?
For Q2 FY27 (quarter ended September 2026), Tata Chemicals reported consolidated revenue of ₹4,177 crore, an 8% year-on-year increase. However, the company posted a net loss of ₹50 crore, a sharp decline from a profit of ₹154 crore in the same quarter last year, due to severe margin pressure in its global operations.
Why did Tata Chemicals report a net loss in Q2 FY27 despite revenue growth?
Tata Chemicals' Q2 FY27 loss was caused by a severe margin squeeze in its overseas soda ash business. According to the company's investor presentation, unremunerative pricing in key export markets like Southeast Asia, coupled with sharply higher input and fixed costs from geopolitical disruptions, overwhelmed the revenue growth from higher volumes.
What was Tata Chemicals' net profit margin in Q2 FY27?
Tata Chemicals' consolidated net profit margin was -1.2% in Q2 FY27. This represents a decline of 520 basis points compared to the 4.0% margin achieved in the same quarter of the previous fiscal year (Q2 FY26).
How did Tata Chemicals' domestic business perform in Q2 FY27?
Tata Chemicals' standalone India business performed strongly in Q2 FY27. As per an Investing.com report, standalone EBITDA grew 22% year-on-year to ₹292 crore, driven by higher sales volumes in salt and improved realizations, providing a resilient counterbalance to the struggling international operations.
What caused the 23.2% YoY increase in depreciation for Tata Chemicals?
The 23.2% year-on-year rise in depreciation to ₹351 crore in Q2 FY27 is attributed to ongoing capacity expansion projects and currency impact on overseas assets. The company is progressing with multiple projects, including a precipitated silica plant in Cuddalore and salt plants in Mithapur and Valinokkam.
Why did Tata Chemicals' other income fall 31.2% YoY?
Tata Chemicals' other income fell 31.2% year-on-year to ₹95 crore in Q2 FY27. The company's investor presentation cited lower other income and joint-venture income as contributing factors to the steep decline in profit after tax for the quarter.
What is the update on Tata Chemicals' capacity expansion plans?
Tata Chemicals is advancing several expansion projects. Key plans include a 50 KTPA precipitated silica plant in Cuddalore, an 82.5 KTPA iodised salt plant in Mithapur targeted for Q1 FY28, a 210 KTPA salt plant in Valinokkam, and a 40 KTPA bicarbonate plant in Singapore, as per its investor presentation.
What is the status of Tata Chemicals' debt?
As of September 30, 2026, Tata Chemicals' consolidated net external debt (excluding leases) stood at ₹6,127 crore, a slight increase from ₹5,961 crore at the end of March 2026. The company has stated a focus on working capital optimization and debt reduction as key priorities in the current environment.
How did the stock react to Tata Chemicals' Q2 FY27 results?
On the day of the results, Tata Chemicals' stock was quoted at ₹607.45, down 1.36%. According to Investing.com, the shares were trading near their 52-week low, reflecting market caution over the consolidated loss and the challenging near-term outlook for its global business.
What is the global outlook for soda ash pricing?
The outlook for global soda ash pricing remains soft. Management's presentation describes a persistent oversupply in the market, limiting pricing power. Peer GHCL, as reported by Multibagg.ai, also expects soda ash realizations to remain subdued for the next few quarters due to global oversupply and weak industrial demand.
Tata Chemicals Q2 FY27 results August 2026
Tata Chemicals announced its Q2 FY27 results (for the quarter ended September 2026) on November 7, 2026. The company reported revenue of ₹4,177 crore, an 8% increase year-on-year, but posted a consolidated net loss of ₹50 crore due to severe margin pressure in its global soda ash operations.
Tata Chemicals Industrial Essentials posts Rs 190 crore EBIT loss
In Q2 FY27, Tata Chemicals' Industrial Essentials segment, which includes soda ash, reported an EBIT loss of ₹120 crore, deepening from a ₹70 crore loss in the prior quarter. This was due to lower realizations in the US, higher input costs, and the temporary suspension of Kenya operations.
ICICI Prudential MF cuts Tata Chemicals stake
ICICI Prudential Mutual Fund significantly reduced its stake in Tata Chemicals, disclosing a net sale of over 52.5 lakh shares between October 2025 and November 2026. This disposal lowered the fund's stake to 2.94% from 5.01%, as reported by ScanX.trade.