Orient Paper (ORIENTPPR) Q2 FY27 Loss Widens to ₹29 Crore as Revenue Slumps 19%
The paper maker's net loss deepened sequentially as its core business struggled with weak demand and a sharp drop in sales, overshadowing a slight year-on-year improvement.
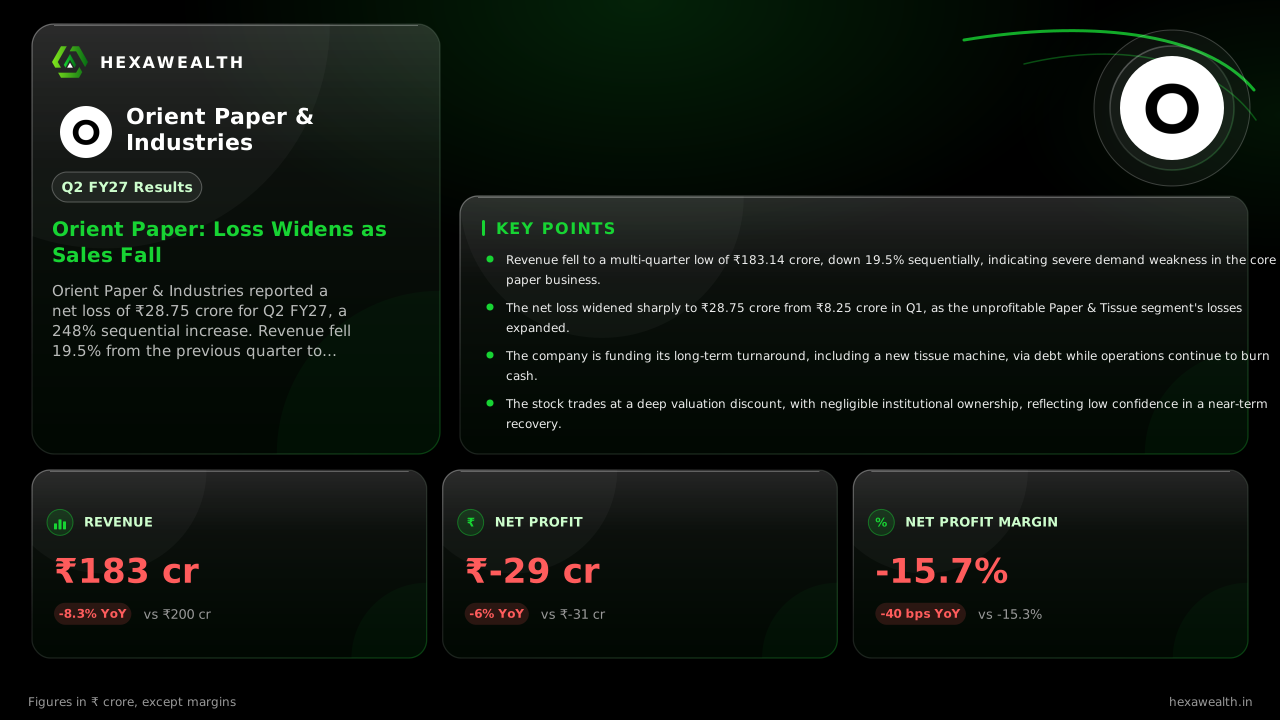
Orient Paper & Industries reported a net loss of ₹28.75 crore for Q2 FY27, a 248% sequential increase. Revenue fell 19.5% from the previous quarter to ₹183.14 crore, marking its lowest quarterly sales in recent periods.
For Orient Paper, the September quarter was a step back after a period of narrowing losses. The company's core paper business faced a sharp demand contraction, pulling revenue down to its lowest level in recent history and sending the bottom line deeper into the red.
The numbers show a business under significant pressure. Revenue fell 8.3% from a year ago and plunged 19.5% from the June quarter to ₹183.14 crore. The net loss widened to ₹28.75 crore, a 248% sequential deterioration, resulting in a net profit margin of -15.7%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ1 FY27 (Jun 2026) |
|---|---|---|
| Revenue (₹ Cr) | 183.14 | 227.61 |
| Profit (₹ Cr) | -28.75 | -8.25 |
| Net Profit Margin (%) | -15.7 | -3.6 |
Why the loss deepened
The steep revenue drop was the primary driver. According to a MarketsMojo report, this 19.5% sequential contraction to ₹183.14 crore represents the lowest quarterly sales in recent periods, signalling significant operational stress. The company's Paper & Tissue segment, its main business, remained the primary drag.
ScanX.Trade notes the segment's loss widened to ₹29.49 crore in Q2 FY27. While the small Chemicals segment stayed profitable, its contribution shrank dramatically year-on-year. This left the consolidated business without a profitable core to offset the paper division's struggles.
A costly turnaround plan
Management is not standing still. The company has launched Project Sankalp, targeting annualised savings of around ₹40 crore, as reported by Investor Feed. A major capacity expansion is also planned, with a new Tissue-4 machine adding 23,400 tonnes per annum by September 2028.
These initiatives aim for long-term efficiency but require funding during a cash-burn phase. The half-year cash flow statement, cited by Arthneeti.com, shows the company raised over ₹61 crore from long-term borrowings. This suggests capex is being debt-funded while operations are loss-making.
The market's verdict
With no verified analyst estimates to beat or miss, the market's reaction hinges on the stark operational reality. The stock has fallen 37.4% over the past year, trading at a steep 57% discount to the industry PE. Institutional interest is minimal, with FII holding at just 0.1% as of Q2 FY27, per StockFin.ai data.
The immediate outlook is clouded by industry-wide cost pressures. Reports from PrintWeek and industry bodies warn of sustained rises in kraft paper and packaging input costs, which could squeeze margins further if Orient Paper cannot pass them on to customers.
Key Points
- Revenue fell to a multi-quarter low of ₹183.14 crore, down 19.5% sequentially, indicating severe demand weakness in the core paper business.
- The net loss widened sharply to ₹28.75 crore from ₹8.25 crore in Q1, as the unprofitable Paper & Tissue segment's losses expanded.
- The company is funding its long-term turnaround, including a new tissue machine, via debt while operations continue to burn cash.
- The stock trades at a deep valuation discount, with negligible institutional ownership, reflecting low confidence in a near-term recovery.
Hexa Perspective
The quarter underscores a structural challenge: Orient Paper's core business is shrinking and unprofitable in a tough market. The modest year-on-year loss reduction is a faint silver lining, but the severe sequential deterioration is the more relevant trend.
The success of Project Sankalp's cost savings and the eventual contribution from new capacity are pivotal. Until then, the company remains vulnerable to further demand softness and input cost inflation, with its financials reliant on balance-sheet strength to fund the path to potential profitability.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.