Unilex Colours (UNILEX) Q2 FY27 Profit Rises 5.5% on Cost Cuts Despite Revenue Slump
The pigment maker's profit grew sequentially on lower expenses, masking a 6.8% drop in quarterly sales as other income fell sharply.
Unilex Colours posted a 5.5% QoQ rise in net profit to ₹7.07 crore for Q2 FY27, driven by a sharp drop in total expenses. This came despite a 6.8% decline in revenue, highlighting a focus on cost efficiency amid softer sales.
For a pigment maker, the quarter is a balance between sales volume and the cost of making color. Unilex Colours tipped that scale toward efficiency in Q2 FY27, lifting profit on lower sales.
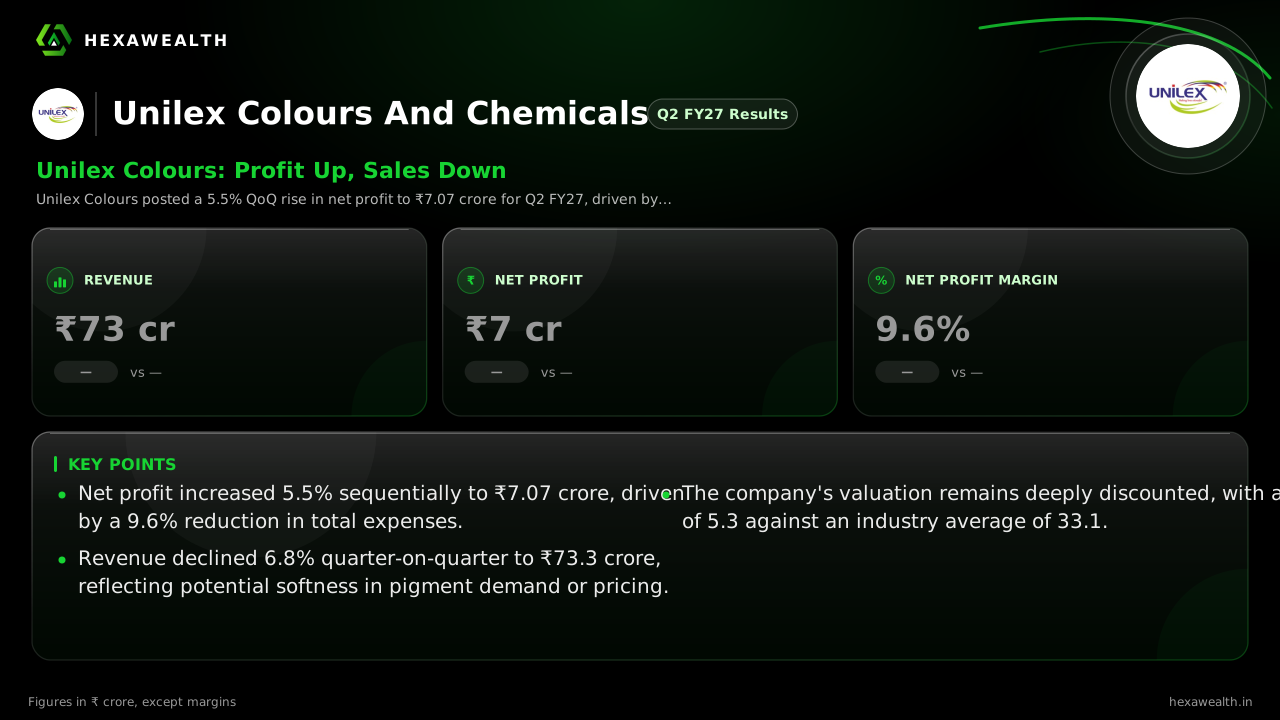
The numbers show a business tightening its belt. Revenue fell 6.8% quarter-on-quarter to ₹73.3 crore. Yet net profit rose 5.5% to ₹7.07 crore, pushing the net profit margin up 110 basis points to 9.6%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 |
|---|---|
| Period | Sep 2026 |
| Revenue (₹ Cr) | 73.3 |
| Profit (₹ Cr) | 7.07 |
| Net Profit Margin (%) | 9.6 |
Where the profit came from
Total expenses fell 9.6%, more than offsetting the revenue drop. This was the main driver, as other income also declined sharply by 22.4%. Employee costs rose 13.1%, but broader cuts elsewhere delivered savings.
The profit gain arrived against a muted demand backdrop. A report from Ken Research forecasts India's pigments market will grow at a 4.1% CAGR through 2032, but value growth lags volume due to price pressure. This suggests Unilex's revenue dip may reflect broader industry pricing challenges.
The market's muted read
With no active analyst coverage or published estimates, the stock's reaction offers the clearest signal. Shares closed at ₹32 on November 5, having lost 16.8% over the past year. The stock trades at a P/E of 5.3, an 84% discount to the industry average, indicating deep skepticism about growth.
Key Points
- Net profit increased 5.5% sequentially to ₹7.07 crore, driven by a 9.6% reduction in total expenses.
- Revenue declined 6.8% quarter-on-quarter to ₹73.3 crore, reflecting potential softness in pigment demand or pricing.
- The company's valuation remains deeply discounted, with a P/E of 5.3 against an industry average of 33.1.
Hexa Perspective
This quarter shows Unilex can protect its bottom line when sales weaken, a testament to cost control. The sustainability of that profit, however, hinges on reversing the top-line decline.
The broader pigment market is growing slowly with pricing headwinds. For the margin expansion to last, Unilex needs revenue to find a footing, either through volume or a richer product mix. Until then, the stock's deep discount reflects justified caution.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.