Olympia Industries (OLYMPTX) Q2 FY27 Profit Rises 13% Despite a 14% Revenue Drop
The trade distributor squeezed out a profit gain on sharply lower overheads, but cash flow turned negative as it cut inventory and receivables.
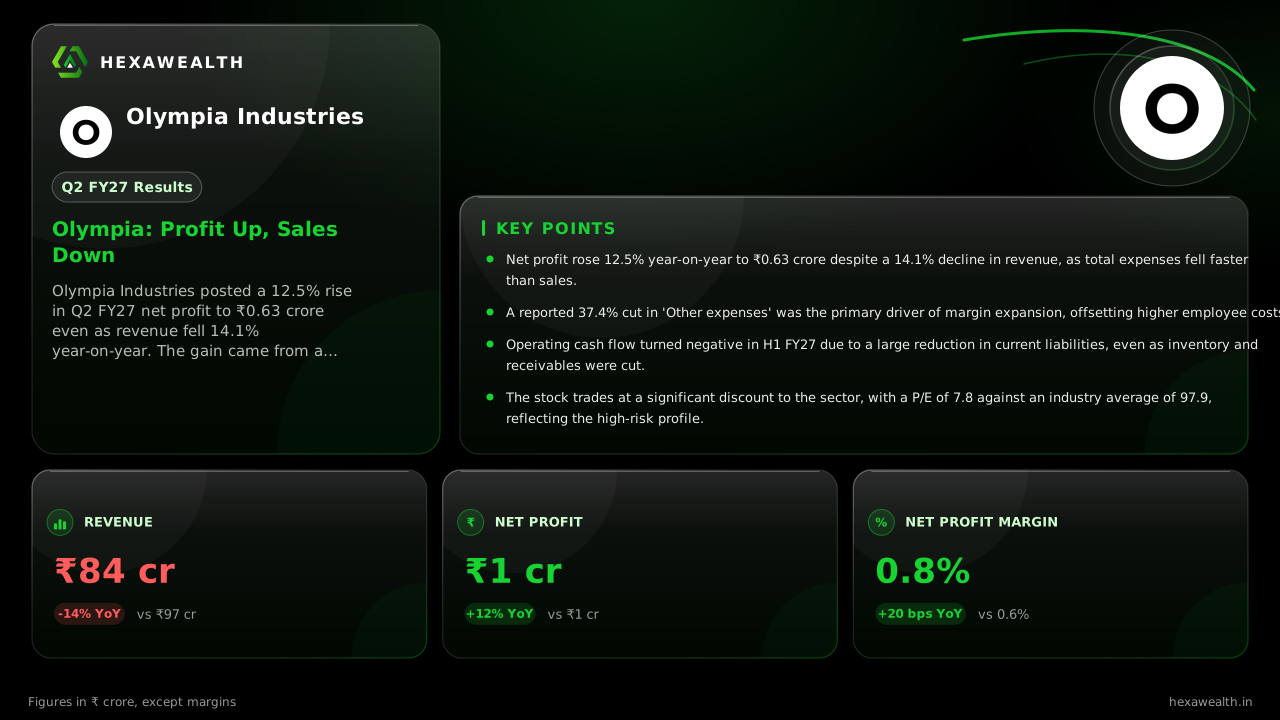
Olympia Industries posted a 12.5% rise in Q2 FY27 net profit to ₹0.63 crore even as revenue fell 14.1% year-on-year. The gain came from a steep 37% cut in other expenses, though operating cash flow turned negative.
For a distributor like Olympia Industries, the top line is the pulse of trade activity. This quarter, that pulse weakened, with revenue dropping 14% from last year and 16% from the prior quarter. Yet, net profit still managed a 12.5% year-on-year gain, a result of aggressive cost containment rather than business growth.
The numbers tell a story of contraction with a silver lining. Revenue for the September 2026 quarter stood at ₹83.51 crore, down from ₹97.27 crore a year ago. Profit, however, inched up to ₹0.63 crore. The net profit margin expanded by 20 basis points to 0.8%, a small but meaningful improvement in a thin-margin business.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 83.51YoY -14% | 99.01 | 97.27 |
| Profit (₹ Cr) | 0.63YoY +12% | 0.62 | 0.56 |
| Net Profit Margin (%) | 0.8YoY +33% | 0.6 | 0.6 |
Where the profit came from
Profit growth was entirely driven by costs falling faster than sales. According to a scanx.trade report, total expenses dropped 14.2% year-on-year. The key lever was a 37.4% plunge in 'Other expenses', which outweighed an 18% rise in employee costs. This suggests a deliberate pullback on discretionary overheads and perhaps strategic pricing initiatives.
The cash flow catch
This cost discipline, however, came with a liquidity trade-off. Flash Finance reported operating cash flow for the first half of FY27 turned negative at -₹0.25 crore, a sharp reversal from +₹19.06 crore a year earlier. The company significantly reduced inventories and trade receivables, a multibagg.ai analysis noted, but this was offset by a larger drop in current liabilities. The cash balance remains thin at just ₹5.46 lakh.
A market waiting for growth
With revenue declining sequentially from a strong Q1, the immediate question is demand. The company has not provided formal guidance, but reports suggest the focus is on the upcoming festive quarter for a recovery. Institutional interest remains minimal, with a MarketsMojo analysis showing mutual funds hold just 0.05% of the company, a sign of lingering scepticism about the business model's sustainability at this scale.
Key Points
- Net profit rose 12.5% year-on-year to ₹0.63 crore despite a 14.1% decline in revenue, as total expenses fell faster than sales.
- A reported 37.4% cut in 'Other expenses' was the primary driver of margin expansion, offsetting higher employee costs.
- Operating cash flow turned negative in H1 FY27 due to a large reduction in current liabilities, even as inventory and receivables were cut.
- The stock trades at a significant discount to the sector, with a P/E of 7.8 against an industry average of 97.9, reflecting the high-risk profile.
Hexa Perspective
The quarter presents a paradox of improved profitability atop a shrinking business. The margin gain is a clear positive, showing management can protect the bottom line when the top line softens. Yet, it is not a repeatable strategy if sales continue to decline.
The negative cash flow underscores the fragility. The balance sheet is carrying ₹44.96 crore in borrowings against a market cap of just ₹16 crore, making consistent cash generation critical. Investors are left weighing the efficiency gains against the need for sustainable revenue growth and a cleaner balance sheet.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.