NCC Q2 FY27 Profit Falls 13% Sequentially Despite Record Q2 Revenue
NCC's revenue grew 32% year-on-year to a record high, but profit fell 13% from the previous quarter as rising costs squeezed margins.
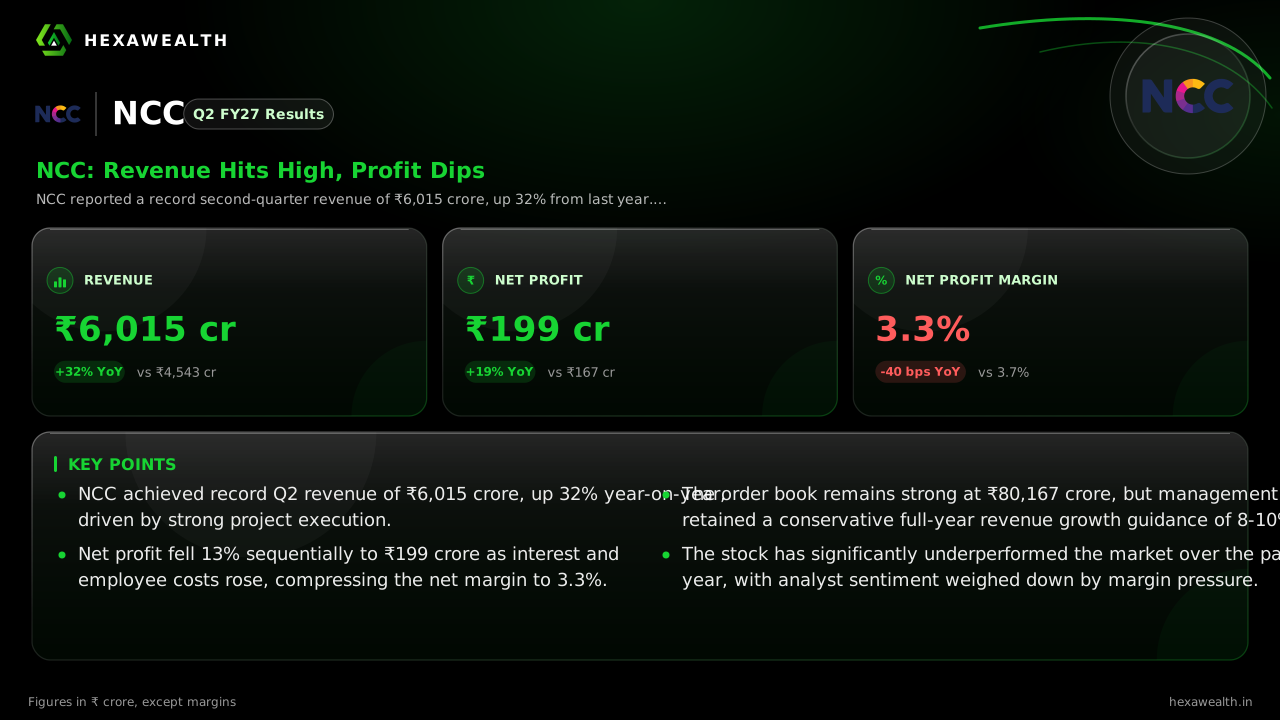
NCC reported a record second-quarter revenue of ₹6,015 crore, up 32% from last year. However, net profit fell 13% sequentially to ₹199 crore, pressured by higher interest and employee costs that compressed margins.
For infrastructure giant NCC, the September quarter delivered a powerful top line but a weaker bottom line. The company posted its highest-ever second-quarter revenue, yet profit fell from the prior quarter as rising costs took a bite.
The numbers tell a story of two diverging trends. Revenue rose 32% year-on-year and 3.5% sequentially to ₹6,015 crore. In contrast, net profit declined 13% from the June quarter to ₹199 crore, even as it grew 19% from last year.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 6,015YoY +32% | 5,812 | 4,543 |
| Profit (₹ Cr) | 199YoY +19% | 229 | 167 |
| Net Profit Margin | 3.3%YoY -11% | 3.9% | 3.7% |
Where the growth came from
Strong execution across a diversified project portfolio drove the record revenue. According to the company's earnings call, new orders worth ₹4,838 crore were booked, mainly from the buildings, water, and railway divisions. The consolidated order book stood at a robust ₹80,167 crore, providing 3.5 times revenue visibility.
The costs that squeezed profit
Revenue growth did not translate to the bottom line. The net profit margin contracted by 60 basis points sequentially to 3.3%. A report from MarketsMojo attributed this to elevated interest costs, which surged 6.7% quarter-on-quarter to ₹211 crore, and rising employee expenses.
Higher debt levels and interest rates are driving the finance charge increase. Depreciation also rose as new capital assets, like a Tunnel Boring Machine, were put to use. These fixed costs are pressuring profitability even as the company executes more work.
The outlook and market read
Management retained its full-year guidance, expecting 8-10% revenue growth and an EBITDA margin of 8.5-9%. They noted that major Jal Jeevan Mission backlogs are expected to be substantially completed by March 2027, which should improve cash flows.
The stock, however, reflects the margin concerns. It closed at ₹122.84 on November 6, down over 33% in the past year. MarketsMojo rated the stock a 'Sell', citing the bearish technical trend and flat financial performance despite attractive valuation multiples.
Key Points
- NCC achieved record Q2 revenue of ₹6,015 crore, up 32% year-on-year, driven by strong project execution.
- Net profit fell 13% sequentially to ₹199 crore as interest and employee costs rose, compressing the net margin to 3.3%.
- The order book remains strong at ₹80,167 crore, but management retained a conservative full-year revenue growth guidance of 8-10%.
- The stock has significantly underperformed the market over the past year, with analyst sentiment weighed down by margin pressure.
Hexa Perspective
The quarter highlights a classic infrastructure tension: strong revenue visibility from a large order book, but profitability held hostage by rising capital costs. The ₹80,167 crore backlog secures the top line, but the margin squeeze from higher interest and depreciation is real and likely to persist.
The path to a re-rating depends on whether operational leverage can finally kick in. This requires either a moderation in borrowing costs, a shift in the project mix toward higher-margin work, or a significant acceleration in collections to reduce working capital debt. Until then, the stock's deep discount to the industry likely reflects these valid profitability concerns.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.