(NBIFIN) Q2 FY27 NBI Finance Profit Growth Stalls as Costs Outpace Revenue
NBI Industrial Finance's Q2 profit grew a modest 3.6% year-on-year, trailing a 7.6% revenue rise as higher employee costs and taxes squeezed margins.
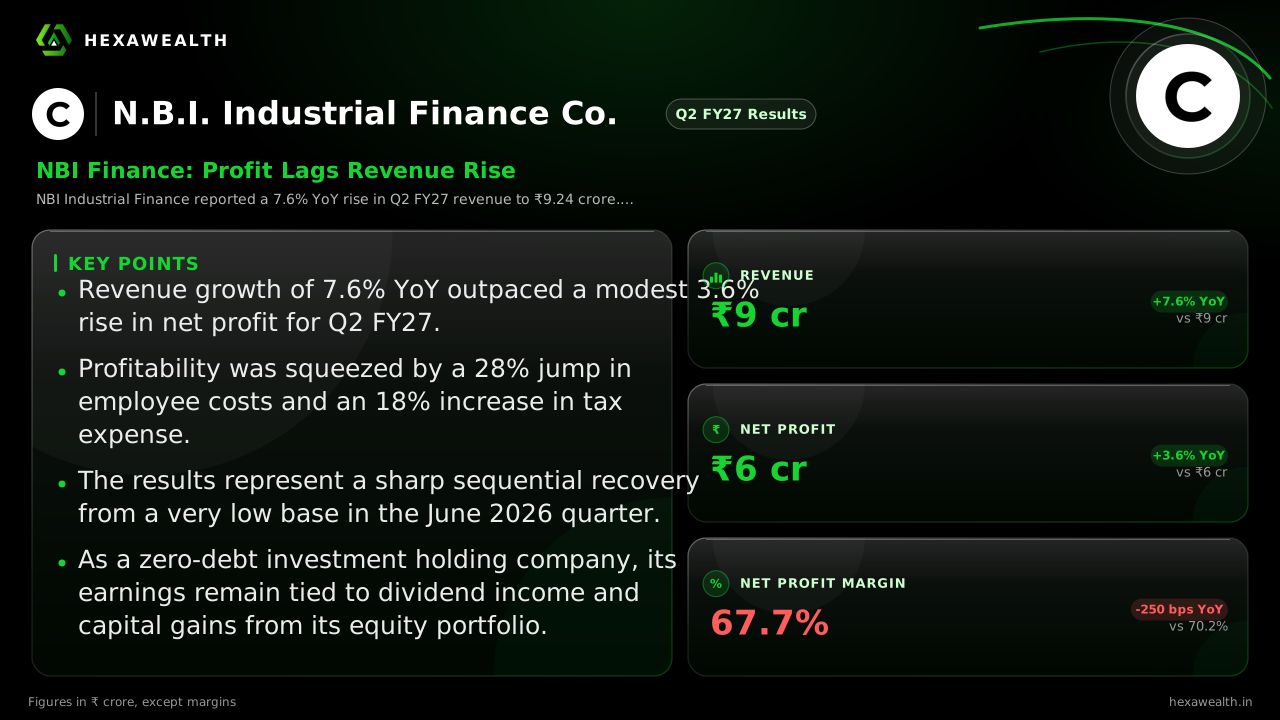
NBI Industrial Finance reported a 7.6% YoY rise in Q2 FY27 revenue to ₹9.24 crore. However, profit growth was limited to 3.6% as employee costs surged 28% and the tax expense jumped, compressing the net profit margin.
For a century-old investment house like NBI Industrial Finance, quarterly earnings are a direct read on its concentrated equity portfolio. The September quarter saw revenue recover sharply from a weak June period, but profitability told a different story.
Revenue rose 7.6% year-on-year to ₹9.24 crore, while profit grew a slower 3.6% to ₹6.25 crore. The net profit margin contracted 250 basis points to 67.7%, as costs grew faster than the top line. The quarter-on-quarter jumps of 326% in revenue and 463% in profit are a rebound from an unusually low base in Q1.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ1 FY27 (Jun 2026) |
|---|---|---|
| Revenue (₹ Cr) | 9.24 | 2.17 |
| Profit (₹ Cr) | 6.25 | 1.11 |
| Net Profit Margin (%) | 67.7 | 50.9 |
Where the profit gain was lost
A 28.3% year-on-year surge in employee costs was a primary drag, according to the company's filings. The tax expense also rose 18.1% YoY and jumped 443% sequentially, reflecting the higher profit before tax. This cost pressure meant that for every rupee of additional revenue, less than half flowed to the bottom line.
The company's income is tied to dividends and occasional sales from its long-term holdings in blue-chips like Shree Cement. A report from StockScans notes it operates as a patient, concentrated portfolio with zero debt. This structure makes earnings volatile and dependent on market cycles and dividend payouts from its key investments.
A quiet quarter for guidance
Management did not hold an earnings call or provide forward-looking commentary this quarter, reports Arthneeti. The outlook therefore hinges on the performance of its underlying investments. Shree Cement, a major holding, reported an 18% revenue rise in its own Q2, though it faced margin pressure from higher fuel costs.
Broader NBFC sector reports, like one from ETBFSI, highlight strong credit growth but warn of rising funding costs. For a pure investment holding company like NBI, these macro shifts affect portfolio valuations more directly than lending margins.
Key Points
- Revenue growth of 7.6% YoY outpaced a modest 3.6% rise in net profit for Q2 FY27.
- Profitability was squeezed by a 28% jump in employee costs and an 18% increase in tax expense.
- The results represent a sharp sequential recovery from a very low base in the June 2026 quarter.
- As a zero-debt investment holding company, its earnings remain tied to dividend income and capital gains from its equity portfolio.
Hexa Perspective
The quarter shows the inherent tension in NBI's model: revenue can bounce with market tides, but profit is vulnerable to fixed-cost creep. With a net profit margin still below last year's level, the path to sustained earnings growth requires either larger portfolio realizations or disciplined cost control.
The stock's valuation at a P/E of 81.2, a 294% premium to the industry, prices in stability that its quarterly volatility challenges. Investors are effectively paying for the quality of its long-term holdings and its pristine balance sheet, betting that occasional margin squeezes won't derail the compounding of its asset base over time.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.