National Plastic Technologies (NATPLASTI) Q2 FY27 Posts Record Revenue but Faces Margin Squeeze
The company's Q2 FY27 sales surged 44% to a new high, yet profitability is under pressure from costs and competitive pricing.
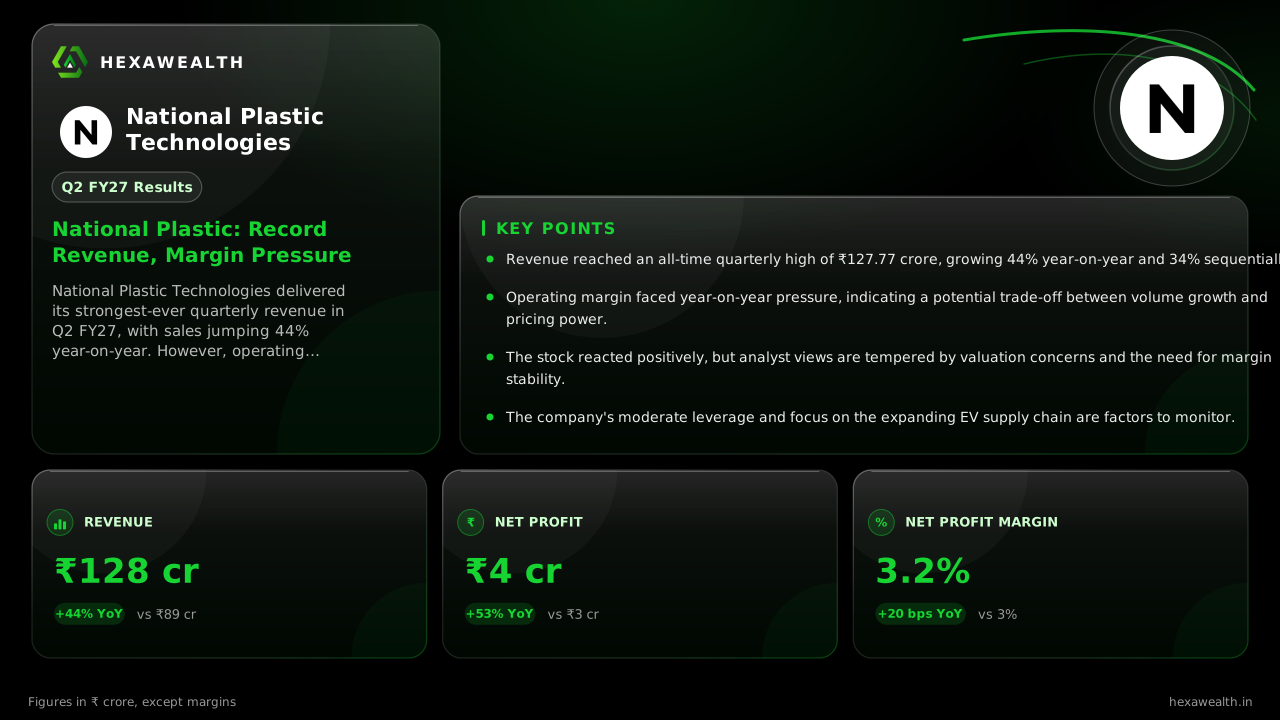
National Plastic Technologies delivered its strongest-ever quarterly revenue in Q2 FY27, with sales jumping 44% year-on-year. However, operating margins contracted, highlighting a trade-off between rapid growth and profitability.
For a manufacturer riding India's auto and consumer durable boom, the test is whether sales growth translates into healthier profits. National Plastic Technologies' September quarter delivered a record top line but left that question open.
Revenue soared to ₹127.77 crore, a 44% jump from a year ago and a 34% surge from the June quarter. Profit followed, rising 53% year-on-year to ₹4.15 crore. The company's net profit margin improved slightly to 3.2% from 2.7% last quarter.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ1 FY27 (Jun 2026) |
|---|---|---|
| Revenue (₹ Cr) | 127.77 | 95.19 |
| Profit (₹ Cr) | 4.15 | 2.56 |
| Net Profit Margin | 3.2% | 2.7% |
The Growth and the Squeeze
The revenue acceleration reflects strong demand in its core automotive market. Reports from MarketsMojo note the company has begun supplying components for electric two-wheelers, tapping into a high-growth segment. This demand, however, is coming with a cost.
Operating margin, excluding other income, contracted by 66 basis points compared to last year, as per MarketsMojo. This suggests that to secure this volume, the company may be facing competitive pricing or that rising input costs are outpacing its ability to pass them on. Profit growth outpaced revenue due to operating leverage, but the underlying margin trend is a watchpoint.
A Market of Two Minds
The stock surged nearly 8% on the results day, significantly outperforming the broader market, as noted by MarketsMojo. This shows investor enthusiasm for the clear growth inflection. Yet, analysts express caution. The same report highlights an elevated PEG ratio of 2.75, implying the stock price may already reflect aggressive future growth expectations that need to be met.
Furthermore, the company carries a debt-to-equity ratio of 0.86, which Univest.in flags as a key risk. While interest costs rose 20% sequentially, they were controlled relative to the revenue surge. Managing this leverage while funding growth will be crucial.
Key Points
- Revenue reached an all-time quarterly high of ₹127.77 crore, growing 44% year-on-year and 34% sequentially.
- Operating margin faced year-on-year pressure, indicating a potential trade-off between volume growth and pricing power.
- The stock reacted positively, but analyst views are tempered by valuation concerns and the need for margin stability.
- The company's moderate leverage and focus on the expanding EV supply chain are factors to monitor.
Hexa Perspective
The quarter establishes a new revenue run-rate for National Plastic Technologies, validating its position in a robust auto ancillary cycle. The central tension is between this demonstrated growth and the pressure on unit economics.
For the momentum to sustain, the company must either demonstrate an ability to improve margins in the coming quarters or prove that this level of sales growth is durable enough to drive profit expansion despite thinner margins. The market's current optimism is betting on the latter, but the margin trend is the metric that will confirm or challenge that bet.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.