(KAMATS) Q2 FY27 Kamat Hotels Swings Back to Loss as Revenue Drops 32% Sequentially
The hotel chain posted a ₹1.77 crore net loss in Q2 FY27 as revenue fell sharply, reversing the prior quarter's profit amid seasonal weakness.
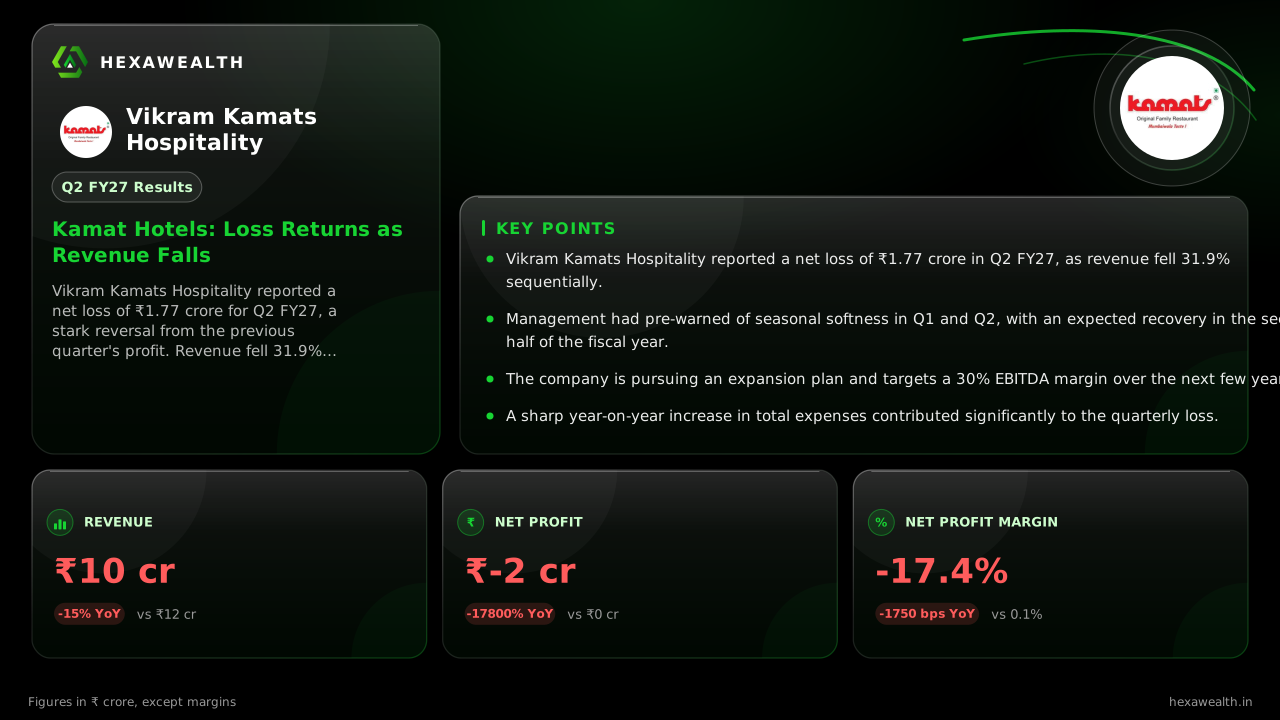
Vikram Kamats Hospitality reported a net loss of ₹1.77 crore for Q2 FY27, a stark reversal from the previous quarter's profit. Revenue fell 31.9% sequentially and 15.1% year-on-year to ₹10.19 crore.
For Kamat Hotels, the September quarter is a seasonal test of its recent turnaround. After a profitable June quarter, the hotelier's revenue fell sharply, pushing it back into a loss and highlighting the volatility still inherent in its recovery.
The numbers show a clear step back. Revenue dropped to ₹10.19 crore, down 32% from the prior quarter and 15% from a year ago. This led to a net loss of ₹1.77 crore, a dramatic reversal from the ₹0.34 crore profit in Q1. The net profit margin fell to -17.4%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ1 FY27 (Jun 2026) |
|---|---|---|
| Revenue (₹ Cr) | 10.19 | 14.97 |
| Profit (₹ Cr) | -1.77 | 0.34 |
| Net Profit Margin (%) | -17.4 | 2.3 |
Why the Quarter Softened
Management had flagged this seasonal pattern. On the Q1 earnings call, executives noted Q1 and Q2 are typically soft before a recovery in the second half, as reported by Stockwatch.live. The quarter's performance aligned with that caution, rather than missing internal expectations.
A key pressure was a significant rise in total expenses, which grew nearly 15% year-on-year despite lower revenue. This squeezed margins, with depreciation and interest costs also ticking up. The company did book higher other income, but it was not enough to offset the operational weakness.
The Path to a Sustained Turnaround
The core challenge is turning occupancy into pricing power. A Finance.yahoo.com summary of the earnings call noted that while occupancy improved, average daily rate growth was a modest 3%. This limits revenue upside even as fixed costs remain.
Management's focus is now on the stronger second half and a multi-year margin target. They aim for 30% EBITDA margins in 2-3 years, up from an estimated 23.8% this quarter. A ₹168 crore investment into a subsidiary, approved by the board, will fund an expansion of about 400 keys over the next 12-15 months.
Key Points
- Vikram Kamats Hospitality reported a net loss of ₹1.77 crore in Q2 FY27, as revenue fell 31.9% sequentially.
- Management had pre-warned of seasonal softness in Q1 and Q2, with an expected recovery in the second half of the fiscal year.
- The company is pursuing an expansion plan and targets a 30% EBITDA margin over the next few years.
- A sharp year-on-year increase in total expenses contributed significantly to the quarterly loss.
Hexa Perspective
This quarter underscores that Kamat Hotels' journey to consistent profitability is not linear. The business remains highly sensitive to seasonal demand swings, and its ability to push room rates is still developing. The planned expansion injects growth potential, but it also introduces execution risk and near-term costs for new properties. Investors are weighing the promised second-half rebound and long-term margin targets against the evident quarterly volatility. The stock's steep decline over the past year reflects this ongoing uncertainty.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.