Oil Country Tubular (OILCOUNTUB) Q2 FY27's Revenue Jumps 150% but Losses Persist
The company's September quarter saw a massive revenue rebound, yet structural costs kept it in the red despite a significant narrowing of losses year-on-year.
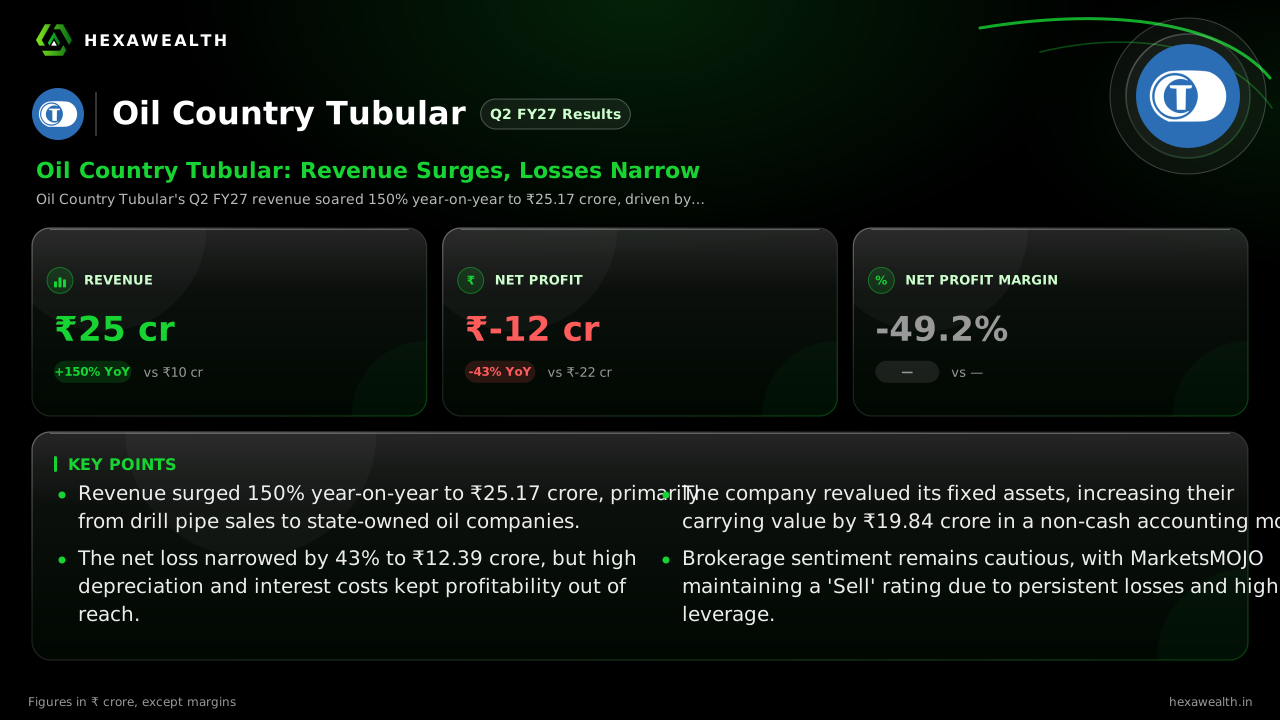
Oil Country Tubular's Q2 FY27 revenue soared 150% year-on-year to ₹25.17 crore, driven by strong drill pipe sales. However, the company reported a net loss of ₹12.39 crore, a 43% improvement from last year's deep loss, as high fixed costs continued to weigh on profitability.
For Oil Country Tubular, a specialist in pipes for oil and gas drilling, the September quarter brought a powerful top-line rebound after a weak start to the fiscal year. Revenue more than doubled from a year ago, yet the company remained firmly in the red, highlighting a persistent struggle with its cost structure.
The numbers tell a story of progress without profitability. Revenue for Q2 FY27 stood at ₹25.17 crore, a massive 150% jump from the same quarter last year and a 44% sequential increase. The net loss, while still substantial at ₹12.39 crore, narrowed by 43% year-on-year, marking the smallest quarterly loss in over a year.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 25.17YoY +150% | 17.44 | 10.05 |
| Profit (₹ Cr) | -12.39YoY +43% | -15.11 | -21.57 |
| Net Profit Margin (%) | -49.2 | - | - |
The source of the surge
This revenue surge was almost entirely driven by the company's core Drill Pipe and Allied Products segment, as reported by arthneeti.com. The performance suggests a pickup in order execution from key state-owned customers like ONGC and Oil India, who dominate its order book under 'Make in India' procurement rules.
Why profit remains elusive
Despite the revenue windfall, the bottom line stayed negative. The primary culprit is a heavy fixed-cost base, with depreciation and employee expenses consuming a large portion of income. While operating profit turned positive at ₹3.84 crore, according to Univest, interest expense nearly doubled sequentially and total expenses rose 16% quarter-on-quarter.
The company's financial health remains fragile. MarketsMOJO noted the firm has reported four consecutive quarters of losses and carries a high debt-to-EBITDA ratio. This prompted the agency to downgrade the stock to 'Strong Sell' just days before the results, though it later upgraded it to 'Sell' on improved technical indicators.
The revaluation and the road ahead
In a significant non-operational move, the board approved a revaluation of land, buildings, and plant & machinery in October. This increased the carrying value of these assets by ₹19.84 crore, as reported by scanx.trade. While this boosts the balance sheet, it does not generate cash or improve operational efficiency.
Management has not provided specific forward guidance. The outlook hinges on sustaining this higher revenue run-rate to absorb fixed costs. The global OCTG market is projected to grow, with Asia Pacific being the fastest-growing region, according to Fairfield Market Research. This offers a supportive backdrop if the company can secure consistent orders.
Key Points
- Revenue surged 150% year-on-year to ₹25.17 crore, primarily from drill pipe sales to state-owned oil companies.
- The net loss narrowed by 43% to ₹12.39 crore, but high depreciation and interest costs kept profitability out of reach.
- The company revalued its fixed assets, increasing their carrying value by ₹19.84 crore in a non-cash accounting move.
- Brokerage sentiment remains cautious, with MarketsMOJO maintaining a 'Sell' rating due to persistent losses and high leverage.
Hexa Perspective
The quarter shows Oil Country Tubular can generate significant revenue when orders flow, a positive shift from its insolvency-era struggles. However, the path to profitability is steep. The business model carries immense operating leverage; fixed costs are so high that even a ₹25 crore revenue quarter yields a deep loss.
Investors are weighing a technical upgrade against unyielding fundamentals. For the stock to sustain gains, the company must prove this revenue level is repeatable and not a one-off order spike. Until losses turn to profits, the story remains one of speculative recovery, not sustainable turnaround.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.