Organic Coatings (ORGCOAT) Q2 FY27' Losses Deepen Despite Doubled Revenue
The printing inks maker saw revenue more than double year-on-year, but a sharp rise in material costs pushed its quarterly loss wider.
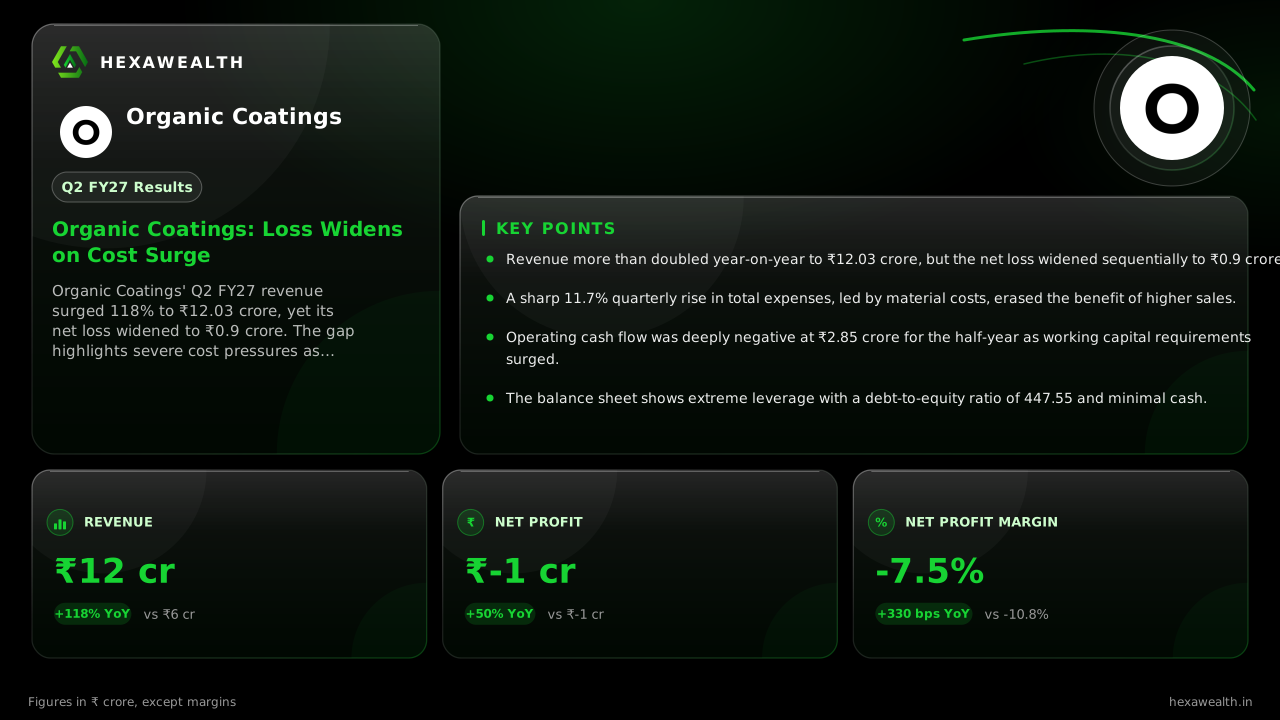
Organic Coatings' Q2 FY27 revenue surged 118% to ₹12.03 crore, yet its net loss widened to ₹0.9 crore. The gap highlights severe cost pressures as material expenses soared, consuming cash and straining its balance sheet.
For Organic Coatings, a surge in sales has become a story of vanishing cash. The printing inks maker more than doubled its revenue year-on-year, yet its losses grew deeper as costs raced ahead.
The September quarter revenue jumped 118% to ₹12.03 crore. Sequentially, sales grew 7.2%. The net loss, however, widened to ₹0.9 crore from a ₹0.36 crore loss in the prior quarter. Profitability moved in opposite directions: the net loss margin improved year-on-year but deteriorated sharply from the June quarter.
Revenue & profit
Revenue (₹ Cr)
Net Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 12.03YoY +118% | 11.22 | 5.53 |
| Net Profit (₹ Cr) | -0.90YoY -50% | -0.36 | -0.60 |
| Net Profit Margin (%) | -7.5YoY +31% | -3.2 | -10.8 |
Where the sales gains went
Total expenses rose 11.7% quarter-on-quarter to ₹12.95 crore, outpacing revenue growth. According to a Multibagg.ai analysis, the cost of materials consumed was the largest expense, reaching ₹10.37 crore for the quarter. This suggests the company is selling more but buying its raw materials at higher prices, eroding any potential profit.
The financial strain is visible in cash flows. The company reported a ₹2.85 crore operating cash outflow for the half-year, notes Multibagg.ai. Trade receivables absorbed ₹6.41 crore as sales expanded, leaving cash reserves at a thin ₹6.49 lakh by September end.
A balance sheet under pressure
With consistent losses, shareholder equity has nearly vanished. The debt-to-equity ratio stands at an extreme 447.55, indicating liabilities dwarf the company's net worth. This high leverage sustains interest costs, which rose 8% quarter-on-quarter to ₹0.19 crore.
The market reaction has been muted, with the stock largely unchanged around ₹22.50 following the results. MarketsMojo.com categorizes the stock as 'Extreme Risk', citing negative shareholder equity and persistent operational losses that revenue growth cannot mask.
Key Points
- Revenue more than doubled year-on-year to ₹12.03 crore, but the net loss widened sequentially to ₹0.9 crore.
- A sharp 11.7% quarterly rise in total expenses, led by material costs, erased the benefit of higher sales.
- Operating cash flow was deeply negative at ₹2.85 crore for the half-year as working capital requirements surged.
- The balance sheet shows extreme leverage with a debt-to-equity ratio of 447.55 and minimal cash.
Hexa Perspective
The quarter reveals a business caught in a growth trap. While demand for printing inks appears robust, Organic Coatings lacks pricing power or cost control to convert that demand into profit. The cash consumed by receivables and inventory suggests growth is being financed, not funding itself.
For the trend to reverse, the company needs material costs to fall or selling prices to rise significantly. Until then, even strong revenue increases will likely deepen the cash crunch, making financial stability the more pressing concern than top-line growth.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.