Orient Press (ORIENTLTD) Q2 FY27 Loss Narrows Sequentially as Sales Slip 20% Year-on-Year
The packaging firm's net loss improved from the previous quarter, but a sharp drop in printing revenue and a struggling flexible packaging segment kept it in the red.
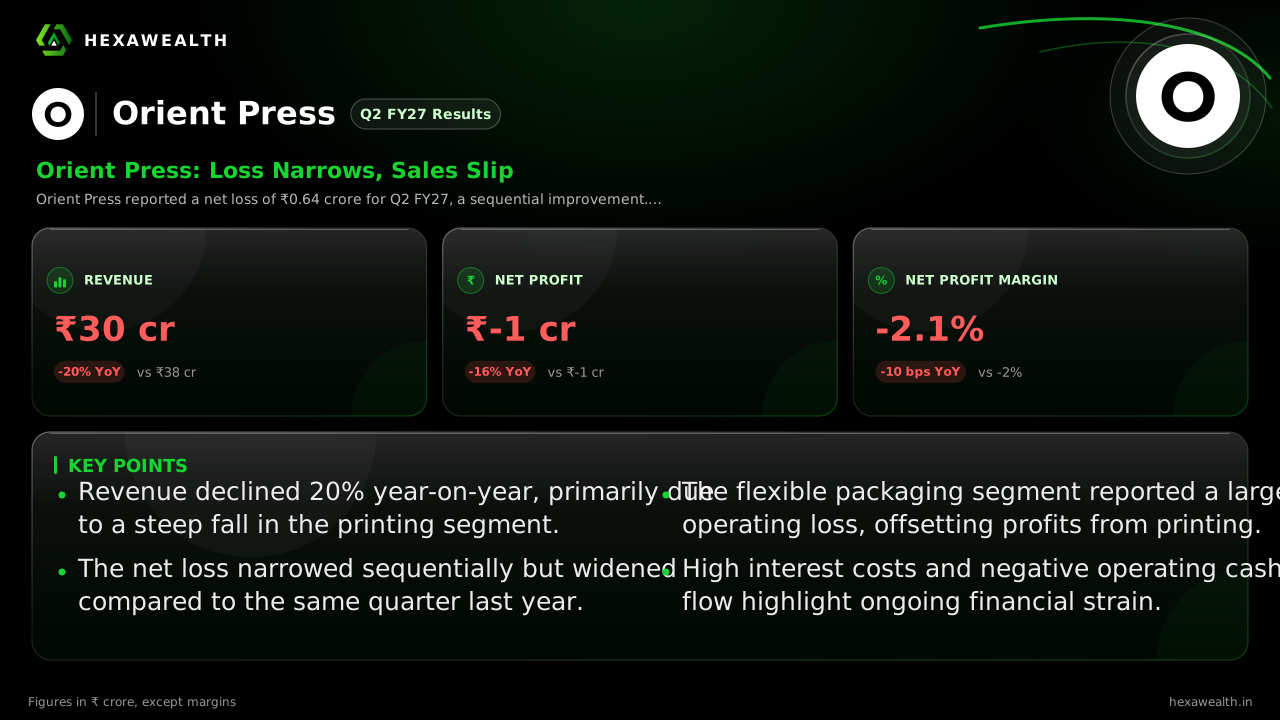
Orient Press reported a net loss of ₹0.64 crore for Q2 FY27, a sequential improvement. Revenue, however, fell 20% year-on-year to ₹30.03 crore, driven by a steep decline in its printing segment.
For Orient Press, the September quarter presented a mixed recovery. While the company managed to narrow its losses from the dismal June quarter, it did so against a backdrop of significantly weaker sales compared to last year, highlighting persistent demand challenges.
The numbers show a quarter pulled in two directions. Revenue of ₹30.03 crore was up 39.5% from the previous quarter but down 20.2% from a year ago. The net loss of ₹0.64 crore was an improvement from the ₹1.25 crore loss in Q1, yet it was still deeper than the ₹0.76 crore loss in Q2 FY26.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 30.03YoY -20% | 21.53 | 37.61 |
| Profit (₹ Cr) | -0.64YoY +16% | -1.25 | -0.76 |
| PAT Margin (%) | -2.1YoY -5% | -5.8 | -2.0 |
The Segment Split Behind the Slide
A sharp 32% year-on-year drop in the printing segment's revenue was the primary driver of the overall top-line contraction, according to a report by ScanX. While this segment still managed a positive operating profit, the flexible packaging division reported a significant operating loss of ₹2.62 crore for the quarter. This indicates the core packaging business remains a substantial drag on profitability.
The company's reliance on non-operating income to support its bottom line grew more pronounced. Other income fell 41% year-on-year to ₹1.08 crore, yet it still accounted for over 60% of the total operating profit, as noted by MarketsMojo. This underscores the weakness in the underlying business economics.
A Tight Financial Position
Financing this operation remains a burden. Interest costs rose 9% sequentially to ₹1.58 crore, consuming nearly all operating profit. The interest cover ratio stands at a precarious 0.81. Furthermore, operating cash flow turned negative for the half-year, with ScanX reporting a ₹1.45 crore outflow driven by payments to trade creditors, signaling working capital stress.
MarketsMojo points out that institutional investors remain absent, with promoter holding inching up to 73.97%. The firm maintains a 'Strong Sell' rating on the stock, citing fundamental weaknesses.
Key Points
- Revenue declined 20% year-on-year, primarily due to a steep fall in the printing segment.
- The net loss narrowed sequentially but widened compared to the same quarter last year.
- The flexible packaging segment reported a large operating loss, offsetting profits from printing.
- High interest costs and negative operating cash flow highlight ongoing financial strain.
Hexa Perspective
The quarter reveals a business caught between a cyclical low and structural challenges. The sequential revenue bounce is a positive step, but it comes from a deeply depressed base and remains well below historical levels.
The real concern is the profitability of the core packaging operations. Until the flexible packaging segment can stem its losses or the printing division regains its volume, the company will remain dependent on non-operating income and vulnerable to its debt burden. The path to sustained profitability requires not just a demand recovery, but a material improvement in segment-level economics.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.