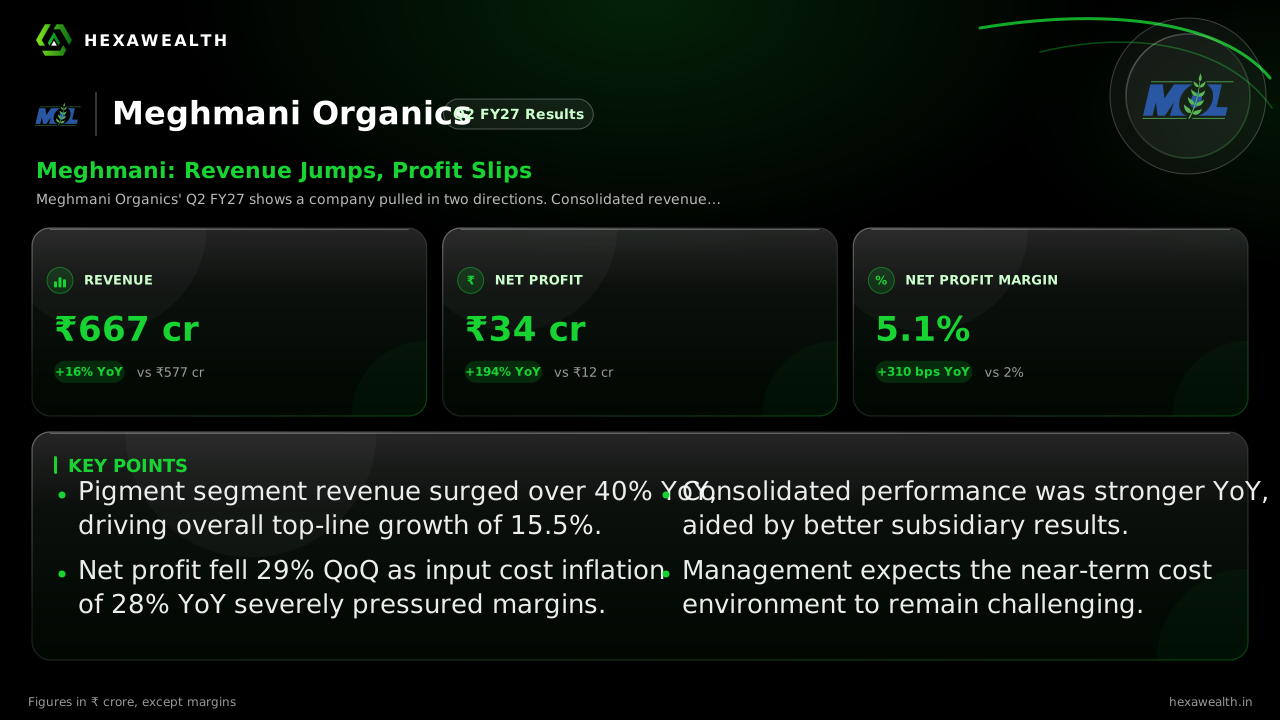
Meghmani Organics posted a 16% YoY revenue rise in Q2 FY27, but profit fell sharply from the previous quarter as input costs surged and realisations stayed flat.
Meghmani Organics' Q2 FY27 shows a company pulled in two directions. Consolidated revenue rose 16% year-on-year, yet net profit dropped 29% sequentially. The pigment segment surged, but rising costs and a flat agrochemical business squeezed profitability.
For Meghmani Organics, the September quarter was a story of two diverging lines. A strong rebound in pigment sales lifted the top line, but the operating story was one of costs rising faster than prices. The result was a quarter where revenue growth masked a significant sequential squeeze on profitability.
The numbers tell the split story. Consolidated revenue rose 15.5% year-on-year to ₹667 crore. Yet net profit fell 29.4% from the previous quarter to ₹34 crore. The net profit margin contracted sharply to 5.1%, down 380 basis points from Q1 FY27's 8.9%.
Revenue & profit
Revenue (₹ Cr)
Net Profit (₹ Cr)
Net Profit Margin
Metric
CurrentQ2 FY27 (Sep '26)
PreviousQ1 FY27 (Jun '26)
Revenue (₹ Cr)
667.0
542.8
Net Profit (₹ Cr)
34.0
48.2
Net Profit Margin
5.1%
8.9%
A Pigment-Led Top Line
Revenue growth was driven entirely by the pigments business. According to a scanx.trade report, standalone pigment revenue jumped 40.4% year-on-year to ₹161.5 crore. Production rose 13% and segment profit more than tripled.
This surge offset a 12.6% decline in the larger agrochemicals segment. The crop protection business, which still makes up 75% of revenue, saw flat production and falling profitability. The company's overall growth was a pigment story.
The Cost Crunch That Ate Profits
While pigments sold more, they did not sell for more. Management, cited in a Tradealone report, said realisations were broadly flat. Meanwhile, input and logistics costs rose sharply.
The cost of materials consumed surged 28.3% year-on-year, according to scanx.trade. This far outpaced the 18% standalone revenue growth, compressing margins. Total expenses rose 31% quarter-on-quarter, explaining the profit drop despite higher sales.
A Glimmer in Consolidation
A consolidated view offers a slightly brighter picture. Subsidiaries like Kilburn Chemicals performed better, driving a 40% year-on-year jump in consolidated EBITDA to ₹73.1 crore, as per Arthneeti. This helped the year-on-year profit comparison look robust, up 194% from a low base.
However, working capital showed strain. Trade receivables ballooned to ₹84.67 crore from ₹65.25 crore at the start of the fiscal year, per scanx.trade. This tied up cash even as the company reduced debt.
Key Points
Pigment segment revenue surged over 40% YoY, driving overall top-line growth of 15.5%.
Net profit fell 29% QoQ as input cost inflation of 28% YoY severely pressured margins.
Consolidated performance was stronger YoY, aided by better subsidiary results.
Management expects the near-term cost environment to remain challenging.
“
Hexa Perspective
The quarter reveals Meghmani navigating a tough pricing environment. The pigment win is positive but operates at just 51% capacity. The core agrochemicals business is stagnant, and cost pressures are acute.
The path forward hinges on whether the company can pass on costs or if raw material prices ease. With a trailing P/E of 32.4, well above the industry average, the stock already prices in a recovery that this quarter's margin squeeze delays.
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.
Frequently asked questions
What were Meghmani Organics' Q2 FY27 results?
Meghmani Organics reported consolidated revenue of ₹667 crore for Q2 FY27, a 15.5% increase year-on-year. Net profit was ₹34 crore, which was a 194% jump from the year-ago quarter but a 29.4% decline from the previous quarter (Q1 FY27).
Why did Meghmani Organics' revenue grow 15.5% YoY in Q2 FY27?
Revenue growth was driven by a strong performance in the pigments segment. According to a scanx.trade report, standalone pigment revenue jumped 40.4% year-on-year to ₹161.5 crore. This growth offset a decline in the larger agrochemicals segment.
What caused the 29.4% QoQ drop in net profit for Meghmani Organics in Q2 FY27?
Profit fell quarter-on-quarter due to a severe margin squeeze. Input and logistics costs surged, with the cost of materials consumed rising 28.3% YoY per scanx.trade, while product realisations remained broadly flat. This compressed the net profit margin by 380 basis points.
Did the pigments or agrochemicals segment drive Meghmani Organics' Q2 FY27 revenue growth?
The pigments segment was the sole driver. Its revenue jumped 40.4% YoY to ₹161.5 crore, while the agrochemicals (crop protection) segment revenue declined 12.6% YoY to ₹496.7 crore, as reported by scanx.trade.
Why did Meghmani Organics' net profit margin contract 380 bps QoQ in Q2 FY27?
The margin contraction was due to a sharp rise in costs outpacing revenue. Management commentary in a Tradealone report cited elevated input and logistics costs with flat realisations. Total expenses rose 31% sequentially, severely impacting profitability.
What is the status of Meghmani Organics' working capital in Q2 FY27?
Working capital showed signs of stress. According to scanx.trade, trade receivables increased sharply to ₹84.67 crore as of September 2026 from ₹65.25 crore in March 2026. This rise, coupled with higher inventory, resulted in negative working capital changes for the half-year.
What guidance did Meghmani Organics management provide for FY27?
Management has reiterated an annual target of ₹550-600 crore in revenue from the pigments business segment, as noted by SAHI. They acknowledged a challenging near-term cost environment and are focusing on product mix optimization and operational efficiencies.
What are Meghmani Organics' key capacity expansion plans for FY27?
The company is planning a Multi-Purpose Product (MPP) plant for crop protection in Dahej, as per an Arthneeti report. It will manufacture high-value new-age insecticides with a capacity of 5,000 MTPA. Otherwise, management has indicated no plans for heavy capital expenditure in the next 1-2 years.
Did Meghmani Organics Q2 FY27 results beat or miss analyst estimates?
Available reports do not cite specific analyst estimates for comparison. The results showed a strong year-on-year profit jump but a significant sequential decline in profit and margins, indicating performance was mixed relative to the previous quarter's high watermark.
How did Meghmani Organics stock price react to the Q2 FY27 results announcement?
The stock closed at ₹55.66 on November 4, 2026, the results date. Specific intraday reaction data is not provided in the research, but the stock has declined 22.6% over the past year, reflecting broader challenges.
Meghmani Organics Q2 profit drop
Meghmani Organics' Q2 FY27 net profit was ₹34 crore, a 29.4% drop from the ₹48.19 crore profit in Q1 FY27. The decline was caused by a sharp increase in input and logistics costs which compressed margins, even as revenue grew.
Meghmani Organics Q2 FY27 results
Meghmani Organics announced its Q2 FY27 results on November 14, 2026. Consolidated revenue was ₹667 crore, up 15.5% year-on-year. Net profit was ₹34 crore, a 194% increase from the year-ago quarter but a 29% decline from the previous quarter.